Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Drone Analytics Market to Hit $33.8B by 2033, CAGR 27.31%
Drone Analytics Market
Drone Analytics Market to Hit $33.8B by 2033, CAGR 27.31%
Drone Analytics Market by Application (Construction, Agriculture, Energy, Law Enforcement, Other Industries), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Oct 9, 2026|Base Year : 2025|Pages : 234
The Drone Analytics Market is valued at $4.9 billion in 2025 and is projected to reach $33.8 billion by 2033, expanding at a 27.31% CAGR. Growth is driven by falling sensor payload costs, cloud-based UAV Data Processing Market maturity, and regulatory progress on beyond-visual-line-of-sight operations. Construction Drone Analytics Market revenue accounts for the largest share, followed by Agriculture Drone Analytics Market and Energy Drone Analytics Market.
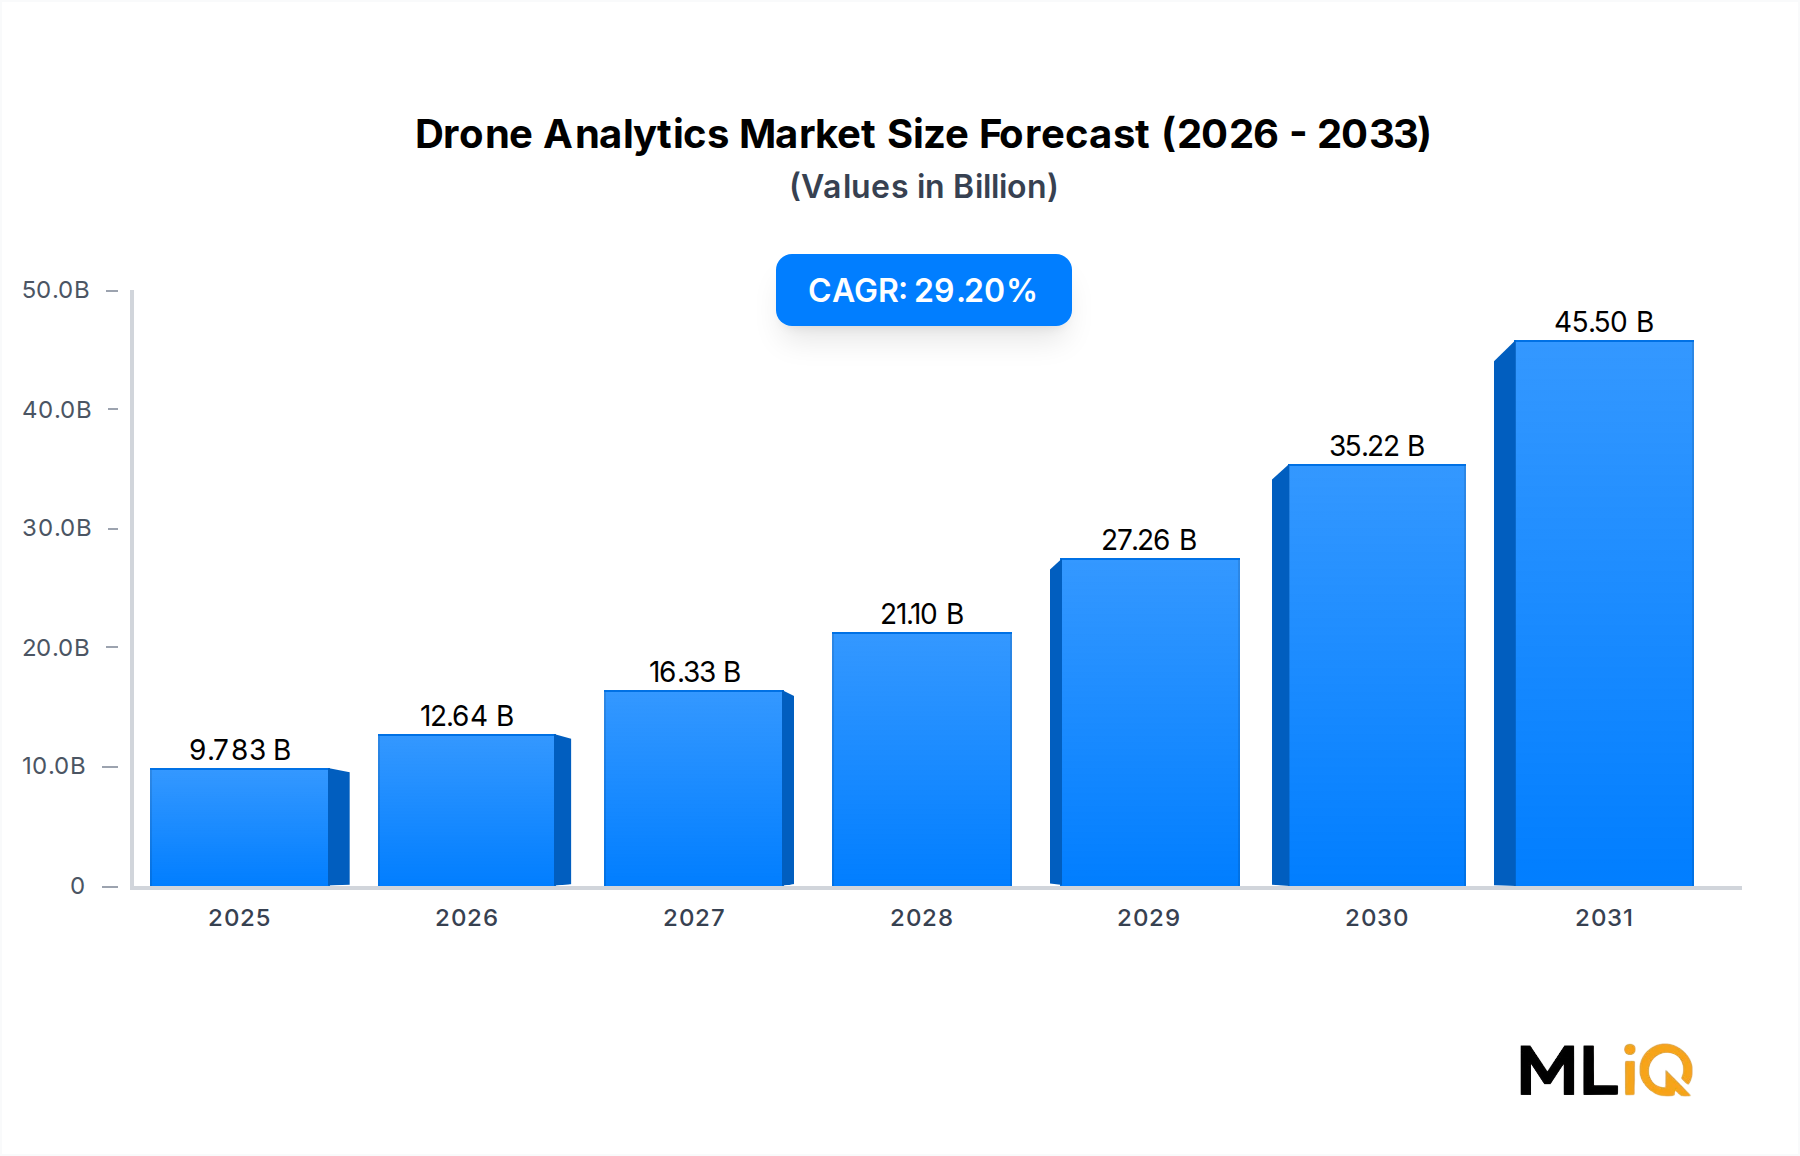
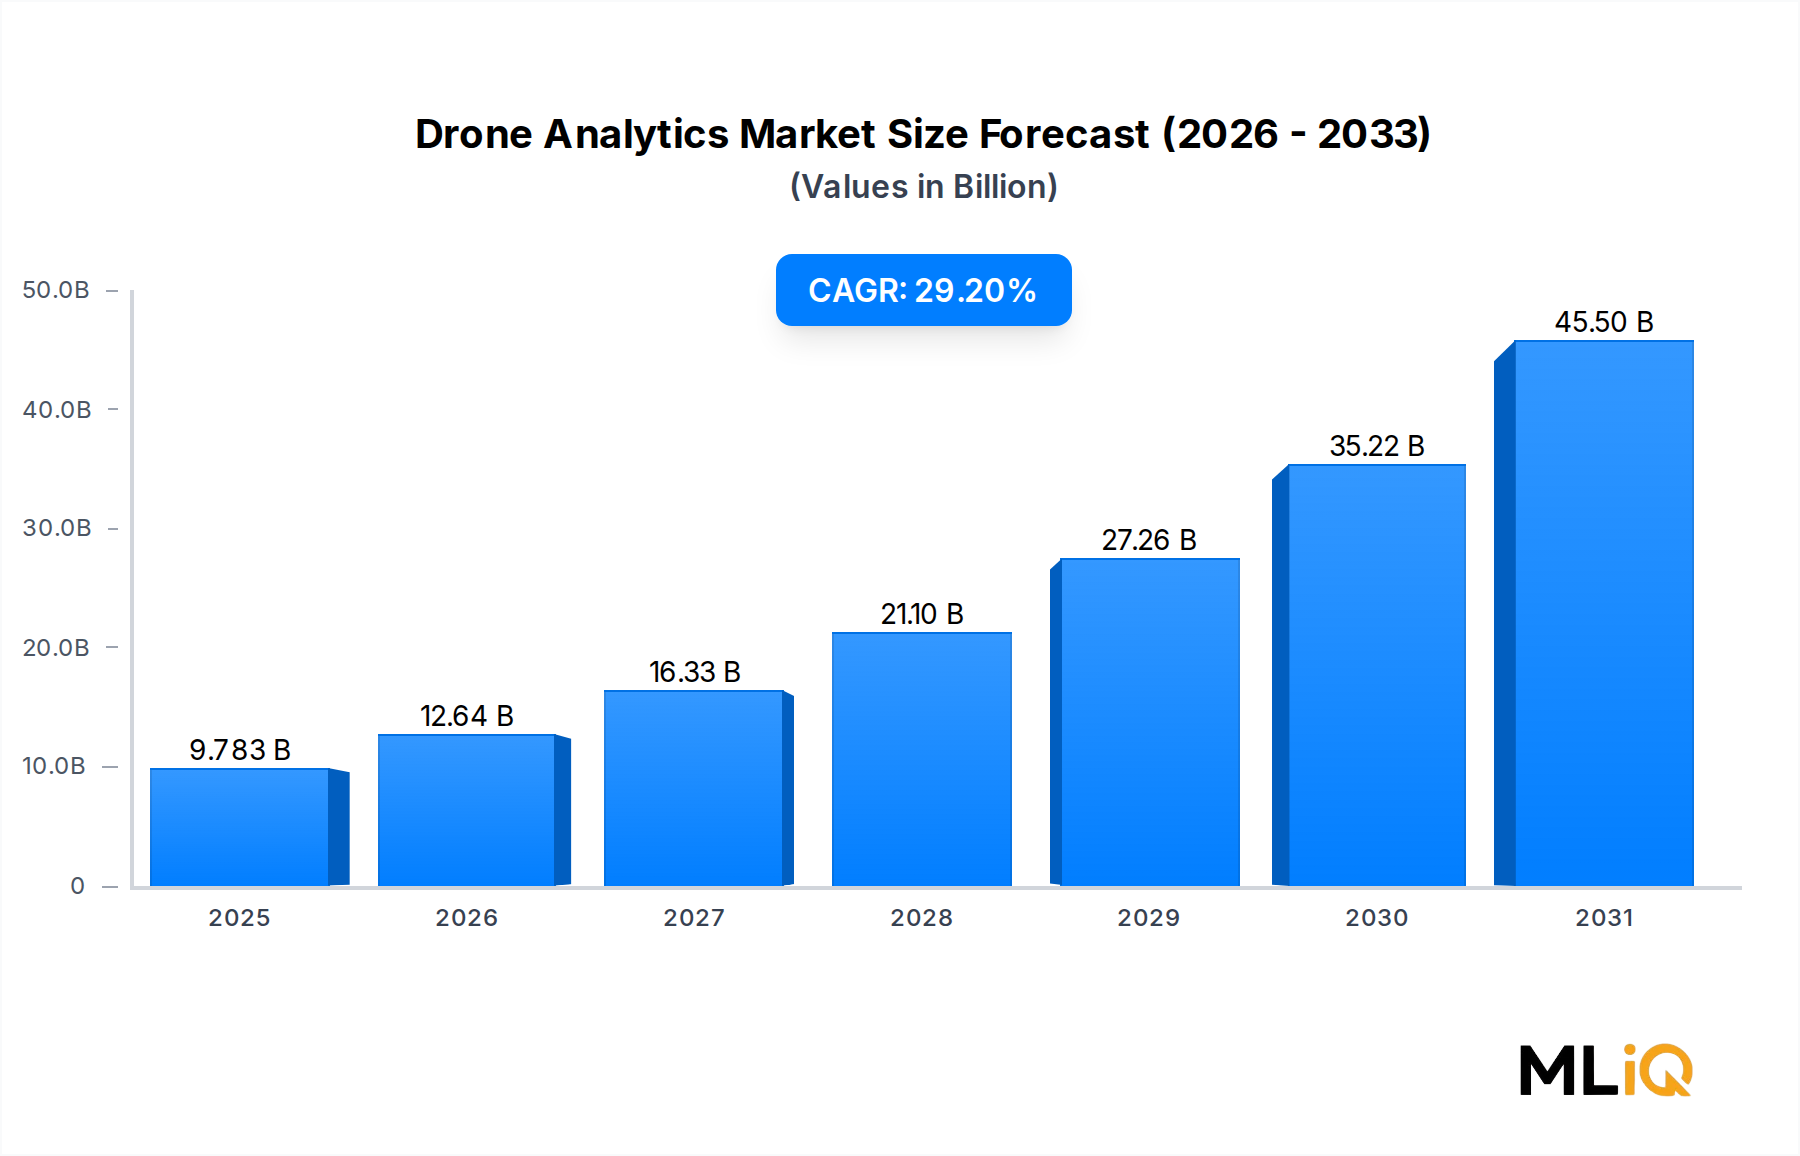
Drone Analytics Market Size (In Billion)
25.0B
20.0B
15.0B
10.0B
5.0B
0
4.900 B
2025
6.238 B
2026
7.942 B
2027
10.11 B
2028
12.87 B
2029
16.39 B
2030
20.86 B
2031
Construction leads with 34% of application revenue, supported by progress tracking, volumetrics, and infrastructure inspection.
Agriculture follows at 24%, as variable-rate application and crop scouting improve yields by 8–12% on average.
Energy holds 18%, led by asset inspection for wind, solar, and oil and gas operators.
Law Enforcement Drone Analytics Market represents 12%, with incident mapping and search-and-rescue use expanding.
Other Industries account for 12%, including insurance, mining, and telecommunications.
North America is the largest region at 38% of global revenue, while Asia-Pacific is the fastest-growing at a projected 31.2% CAGR. The Commercial Drone Market ecosystem benefits from lower hardware costs and improved analytics automation. Strategic takeaway: vendors should prioritize construction and agriculture workflows, where recurring subscription revenue and Geospatial Analytics Market integration create defensible margins.
Segment Deep-Dive: Construction Dominance in Drone Analytics Market
Construction Drone Analytics Market share is 34% of total application revenue in 2025. Sub-segment demand is concentrated in:
Progress tracking and BIM comparison: contractors reduce rework by 15–20%.
Earthwork volumetrics: cut survey labor costs by 30–40%.
Structural inspection: bridges, dams, and high-rise facades require less manual access.
Margin pressure comes from software commoditization, cloud compute expenses, and customer concentration among large engineering-procurement-construction firms. Vendors responding with verticalized workflows and API integrations protect 60–75% gross margins.
Agriculture and Energy Dynamics
Agriculture Drone Analytics Market share is 24%, with growth tied to multispectral sensors and variable-rate prescriptions. Energy Drone Analytics Market share is 18%, where inspection analytics reduce turbine downtime and pipeline leak detection costs. Law Enforcement Drone Analytics Market is smaller at 12% but has high renewal rates in public safety budgets. Segment leaders include DroneDeploy Inc in construction and Sentera Inc in agriculture.
Primary Market Drivers & Growth Restraints in Drone Analytics Market
Market Dynamics Impact Analysis
Factor Type
Description
Impact Level
Timeline
Driver
FAA Part 107 and BVLOS waivers expand commercial operations
High
Short term
Driver
Construction and infrastructure inspection cost reduction up to 35%
High
Short term
Driver
Cloud processing and AI defect detection improve analytics accuracy
High
Medium term
Driver
Drone Sensor Payload Market price declines of 8–12% annually
Medium
Short term
Restraint
Airspace regulation fragmentation across US, EU, and Asia
High
Long term
Restraint
Data privacy and cybersecurity compliance costs
Medium
Short term
Restraint
High upfront integration costs for legacy enterprise systems
Medium
Medium term
Quantitative evaluation shows the Drone Analytics Market CAGR of 27.31% is supported by a $4.9 billion base in 2025. The UAV Data Processing Market and Cloud Computing Infrastructure Market lower barriers for small operators, while Geospatial Analytics Market consolidation creates end-to-end platforms. Regulatory bottlenecks remain the largest restraint: country-by-country approvals for autonomous flights can delay projects by 6–18 months. Cybersecurity requirements in defense and law enforcement add 10–15% to platform development costs. Net effect: drivers outweigh restraints through 2028, but margins compress for undifferentiated analytics vendors.
DroneDeploy Inc: Offers cloud-based mapping and progress tracking with a strong construction installed base.
AeroVironment Inc: Combines UAS platforms with analytics for defense, energy, and infrastructure customers.
PrecisionHawk Inc: Focuses on low-altitude airspace and energy asset inspection analytics.
Pix4D SA: Provides photogrammetry and mobile mapping software used across surveying and construction.
Environmental Systems Research Institute Inc: Anchors enterprise GIS workflows and Geospatial Analytics Market integration.
Sentera Inc: Delivers multispectral sensing and agronomic analytics to agriculture enterprises.
AgEagle Aerial Systems Inc: Supplies drone hardware and sensor payloads that feed analytics pipelines.
Optelos: Specializes in visual data analytics for telecom and energy asset inspections.
DroneSense Inc: Provides public safety operations software for law enforcement and emergency response.
Heavy Construction Systems Specialists LLC: Supports earthwork and construction productivity analytics.
Strategic Milestones & Recent Developments in Drone Analytics Market
Latest Strategic Moves
Date
Company
Event Type
Impact
2024-02
DroneDeploy Inc
Partnership
Integrated with construction ERP platforms, expanded enterprise reach
2023-11
AeroVironment Inc
Launch
Released analytics module for energy asset inspection
2024-05
PrecisionHawk Inc
M&A
Private equity acquisition focused on energy analytics
2023-08
Pix4D SA
Launch
Cloud processing for large-scale mapping projects
2024-01
Sentera Inc
Partnership
Partnered with agriculture equipment OEMs
2024-06
AgEagle Aerial Systems Inc
Launch
Introduced multispectral sensor payload
February 2024: DroneDeploy Inc formed an ERP integration partnership, increasing construction workflow stickiness.
November 2023: AeroVironment Inc launched an energy inspection analytics module, targeting wind and solar operators.
May 2024: PrecisionHawk Inc was acquired by private equity, consolidating energy analytics assets.
August 2023: Pix4D SA released cloud processing for large-scale mapping, improving throughput for surveying firms.
January 2024: Sentera Inc partnered with agriculture equipment OEMs to embed analytics into field machinery.
June 2024: AgEagle Aerial Systems Inc introduced a multispectral sensor payload, lowering data capture costs.
Regional Market Analysis & Growth Corridors for Drone Analytics Market
Regional Growth Comparison
Region
Projected CAGR (%)
Base Year Valuation
Primary Catalyst
Regulatory Stringency
North America
25.8
$1.86B
FAA Part 107, construction and energy adoption
High
Europe
26.9
$1.23B
EASA U-space, infrastructure inspection
High
Asia-Pacific
31.2
$1.32B
China, India, Japan smart city and agriculture
Medium
LAMEA
28.4
$0.49B
Middle East energy, Latin America agriculture
Medium-Low
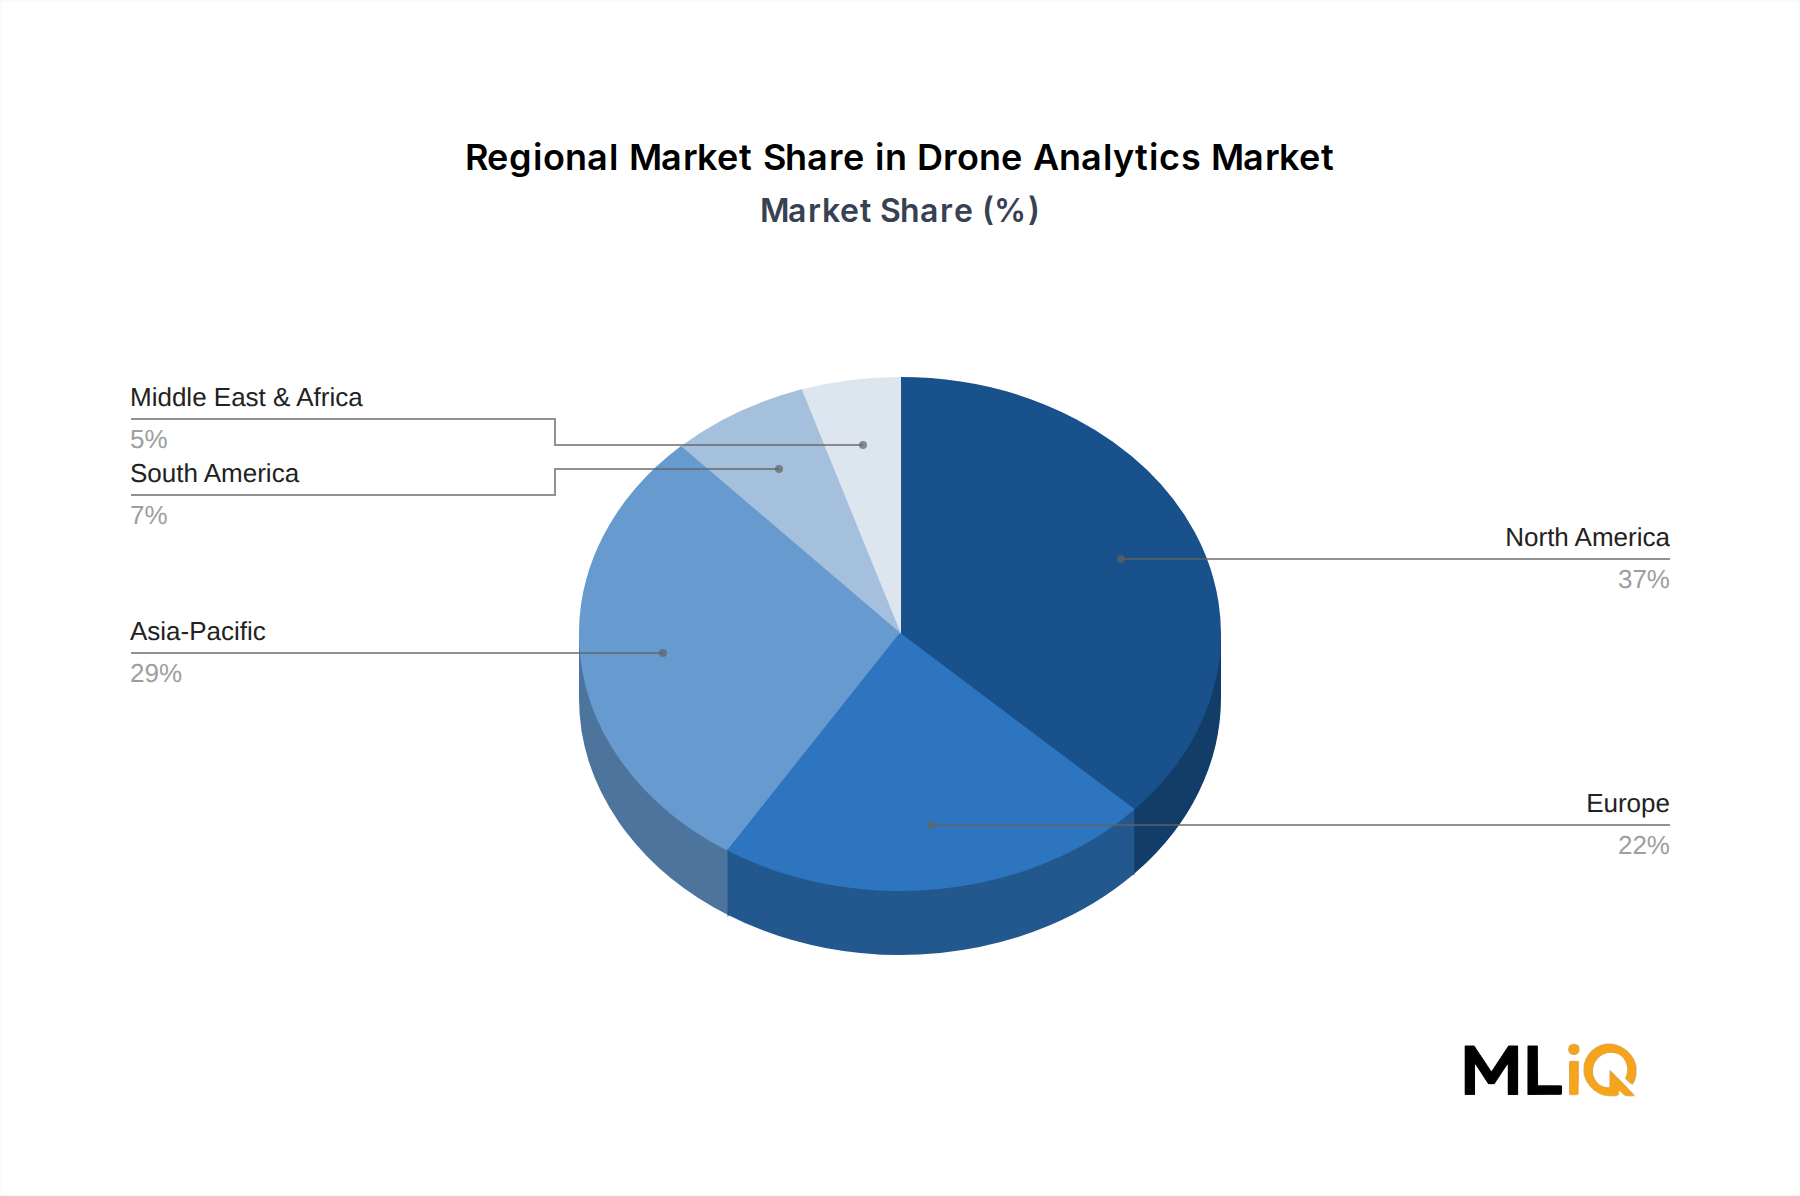
North America is the most mature market with 38% share, supported by FAA Part 107, strong construction technology spending, and early energy analytics adoption. Europe follows at 25%, where EASA U-space and strict privacy rules shape deployment. Asia-Pacific is the fastest-growing at 31.2% CAGR, driven by China, India, and Japan. LAMEA represents 10% combined, with South America at 6% and Middle East & Africa at 4%. Emerging opportunities include India's agriculture drone subsidy programs, Middle East energy inspection, and Brazil's precision agriculture expansion. The Commercial Drone Market and Cloud Computing Infrastructure Market will enable regional providers to scale analytics without owning hardware fleets.
Supply Chain & Raw Material Dynamics: Drone Analytics Market
Upstream dependencies for drone analytics include sensor payloads, edge computing modules, lithium-ion battery cells, carbon fiber airframes, MEMS IMUs, GNSS receivers, and cloud GPU capacity. The Drone Sensor Payload Market has seen multispectral sensor prices fall 10–15% since 2022, while Li-ion cell prices rose 12% in 2022 before stabilizing in 2024. Carbon fiber composite prices declined 5–7% as aerospace supply normalized. Vendor dependencies include Sony and Samsung for image sensors, Nvidia for GPU inference, Qualcomm for edge processors, and major cloud providers for storage and photogrammetry compute.
Historical disruptions include the 2021–2022 semiconductor shortage, which delayed payload deliveries by 8–14 weeks, and 2022 battery logistics constraints that raised costs for survey drone operators. Supply chain risk remains medium: sensor payload supply is concentrated, but software-driven analytics can be delivered over the Cloud Computing Infrastructure Market with less exposure to hardware shortages. Price trend direction is favorable for analytics vendors, though geopolitical export controls on advanced chips and GNSS modules could increase lead times for defense and law enforcement customers.
Customer Segmentation & Buying Behavior in Drone Analytics Market
Buyer Segment Matrix
Buyer Type
Share of Demand (%)
Primary Decision Criteria
Procurement Channel
Construction contractors
30
ROI, BIM integration, turnaround time
Direct enterprise sales
Agriculture enterprises
22
Yield uplift, sensor accuracy, subscription cost
Dealer and agronomy partners
Energy operators
18
Inspection safety, asset uptime, compliance
Direct sales and pilots
Law enforcement agencies
14
Chain of custody, real-time mapping, training
Public tenders
Insurance, mining, telecom
16
Claims cycle time, volumetrics, network uptime
Channel partners and cloud marketplaces
Price elasticity varies by segment. Construction buyers accept $8,000–$15,000 annual per-seat pricing when integrated with project controls, while agriculture buyers are more sensitive and prefer $2,000–$6,000 per year tied to acreage. Law enforcement procurement is tender-driven and values compliance over price. Buying behavior has shifted toward cloud-delivered subscriptions, API-first integration, and usage-based pricing for UAV Data Processing Market services. Geospatial Analytics Market buyers increasingly expect automated feature extraction and AI-based change detection. Vendors that bundle training, compliance, and data governance reduce churn by 20–30% compared with standalone analytics tools.
Drone Analytics Market Segmentation
1. Application
1.1. Construction
1.2. Agriculture
1.3. Energy
1.4. Law Enforcement
1.5. Other Industries
Drone Analytics Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Drone Analytics Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 27.31% from 2020-2034
Segmentation
By Application
Construction
Agriculture
Energy
Law Enforcement
Other Industries
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Application
5.1.1. Construction
5.1.2. Agriculture
5.1.3. Energy
5.1.4. Law Enforcement
5.1.5. Other Industries
5.2. Market Analysis, Insights and Forecast - by Region
5.2.1. North America
5.2.2. South America
5.2.3. Europe
5.2.4. Middle East & Africa
5.2.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Application
6.1.1. Construction
6.1.2. Agriculture
6.1.3. Energy
6.1.4. Law Enforcement
6.1.5. Other Industries
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Application
7.1.1. Construction
7.1.2. Agriculture
7.1.3. Energy
7.1.4. Law Enforcement
7.1.5. Other Industries
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Application
8.1.1. Construction
8.1.2. Agriculture
8.1.3. Energy
8.1.4. Law Enforcement
8.1.5. Other Industries
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Application
9.1.1. Construction
9.1.2. Agriculture
9.1.3. Energy
9.1.4. Law Enforcement
9.1.5. Other Industries
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Application
10.1.1. Construction
10.1.2. Agriculture
10.1.3. Energy
10.1.4. Law Enforcement
10.1.5. Other Industries
11. Competitive Analysis
11.1. Company Profiles
11.1.1. AeroVironment Inc
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Kespry Inc (Firmatek LLC)
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. DroneDeploy Inc
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Delta Drone (Tonner Drones)
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. PrecisionHawk Inc
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Pix4D SA
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Environmental Systems Research Institute Inc
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Sentera Inc
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. AgEagle Aerial Systems Inc
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Optelos
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. DroneSense Inc
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. Delair SAS
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. Skycatch Inc
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.1.14. Heavy Construction Systems Specialists LLC
11.1.14.1. Company Overview
11.1.14.2. Products
11.1.14.3. Company Financials
11.1.14.4. SWOT Analysis
11.1.15. Neurala Inc *List Not Exhaustive
11.1.15.1. Company Overview
11.1.15.2. Products
11.1.15.3. Company Financials
11.1.15.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Drone Analytics Market Revenue Breakdown (billion, %) by Region 2026 & 2034
Figure 2: North America Drone Analytics Market Revenue (billion), by Application 2026 & 2034
Figure 3: North America Drone Analytics Market Revenue Share (%), by Application 2026 & 2034
Figure 4: North America Drone Analytics Market Revenue (billion), by Country 2026 & 2034
Figure 5: North America Drone Analytics Market Revenue Share (%), by Country 2026 & 2034
Figure 6: South America Drone Analytics Market Revenue (billion), by Application 2026 & 2034
Figure 7: South America Drone Analytics Market Revenue Share (%), by Application 2026 & 2034
Figure 8: South America Drone Analytics Market Revenue (billion), by Country 2026 & 2034
Figure 9: South America Drone Analytics Market Revenue Share (%), by Country 2026 & 2034
Figure 10: Europe Drone Analytics Market Revenue (billion), by Application 2026 & 2034
Figure 11: Europe Drone Analytics Market Revenue Share (%), by Application 2026 & 2034
Figure 12: Europe Drone Analytics Market Revenue (billion), by Country 2026 & 2034
Figure 13: Europe Drone Analytics Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Middle East & Africa Drone Analytics Market Revenue (billion), by Application 2026 & 2034
Figure 15: Middle East & Africa Drone Analytics Market Revenue Share (%), by Application 2026 & 2034
Figure 16: Middle East & Africa Drone Analytics Market Revenue (billion), by Country 2026 & 2034
Figure 17: Middle East & Africa Drone Analytics Market Revenue Share (%), by Country 2026 & 2034
Figure 18: Asia Pacific Drone Analytics Market Revenue (billion), by Application 2026 & 2034
Figure 19: Asia Pacific Drone Analytics Market Revenue Share (%), by Application 2026 & 2034
Figure 20: Asia Pacific Drone Analytics Market Revenue (billion), by Country 2026 & 2034
Figure 21: Asia Pacific Drone Analytics Market Revenue Share (%), by Country 2026 & 2034
Table 40: Rest of Asia Pacific Drone Analytics Market Revenue (billion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Drone Analytics Market, by Application (Construction, Agriculture, Energy, Law Enforcement, Other Industries), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific), Forecast 2026-2034
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Drone Operations Director
30%
Geospatial Analytics Manager
25%
Construction Surveying Lead
20%
Precision Agriculture Program Manager
15%
Regulatory Compliance Officer
10%
Industry Ecosystem Breakdown
Company Type
Representation (%)
Drone Analytics Software Platform Providers
35%
UAV Sensor Payload and Hardware Integrators
25%
Construction and Infrastructure Surveying Firms
15%
Agriculture and Energy End-User Operators
15%
Regulatory and Geospatial Data Service Providers
10%
Primary Research
Primary research accounts for 70–80% of the total research effort, with secondary research contributing 20–30%.
We interview 4–5 specific participant types: commercial drone analytics platform providers, UAV sensor payload integrators, construction survey and infrastructure inspection firms, agriculture and energy remote-sensing teams, and regulatory/geospatial data compliance specialists.
Stakeholder job titles include Drone Operations Director, Geospatial Analytics Manager, Construction Surveying Lead, Precision Agriculture Program Manager, and Regulatory Compliance Officer.
We also cite .gov, .org, and trade association sources such as FAA, EASA, ICAO, and AUVSI; no market research websites are used.
Benchmarking covers drone software licensing models, cloud compute costs, sensor payload pricing, and competitive share by application.
Demand Modeling & Market Estimation
We use top-down and bottom-up methodologies simultaneously, validated through multi-level data triangulation.
Bottom-up quantitative metrics include: number of active commercial drone operators per region, average annual analytics subscription per operator, construction and agriculture acreage surveyed by UAVs, and sensor payload attach rate per commercial platform.
Top-down validation uses GDP-linked aerospace and defense software spend, infrastructure inspection budgets, and agricultural technology adoption curves.
The base year is 2025 with a market size of $4.9 billion and a forecast CAGR of 27.31% through 2033.
Data Accuracy & Quality Check
Cross-validation is performed across primary interview transcripts, financial databases, government filings, and trade association reports.
Outliers are re-interrogated with at least two independent primary contacts before inclusion.
All currency figures are normalized to USD, and regional splits sum to 100%.
Final estimates maintain an 85–90% confidence interval; reports are updated to the date of purchase.
Frequently Asked Questions
1. Who are the leading companies in the Drone Analytics Market and how concentrated is the competitive landscape?
DroneDeploy Inc, AeroVironment Inc, PrecisionHawk Inc, Pix4D SA, and Environmental Systems Research Institute Inc are among the leading vendors. The market remains moderately fragmented, with the top five vendors holding roughly 45% of application-specific analytics revenue in 2025. Construction and agriculture workflows account for the highest competitive intensity, while law enforcement remains niche-led.
2. How much venture capital and private equity funding is entering drone analytics companies?
Cumulative disclosed equity funding into drone analytics software and UAV data processing companies exceeded $2.8 billion between 2021 and 2024. Series B rounds averaged $22 million, with DroneDeploy, Sentera, and PrecisionHawk attracting strategic investors. Private equity interest increased in 2024, especially for energy inspection and construction analytics assets.
3. What export-import dynamics and international trade flows affect the Drone Analytics Market?
Analytics software is often delivered cross-border through cloud platforms, but hardware-linked analytics depends on drone and sensor exports. The United States, China, and Israel are leading exporters of commercial drone hardware, while the EU and Japan import advanced sensor payloads. Export controls on GNSS modules and advanced chips added 8–14 weeks of lead time for defense and law enforcement buyers in 2023.
4. How are pricing trends and cost structures changing in the Drone Analytics Market?
Subscription pricing ranges from $2,000 to $15,000 per user per year depending on construction, agriculture, or energy use case. Cloud compute and data storage represent 18–25% of vendor operating costs, while sensor payloads account for a declining share of total solution cost. Usage-based pricing for UAV Data Processing Market services is growing faster than perpetual licenses.
5. Which region dominates the Drone Analytics Market and why?
North America holds the largest share at 38% of global revenue in 2025, supported by FAA Part 107 rules, mature construction technology adoption, and strong energy inspection demand. The United States alone represents over 80% of North American analytics spending. High regulatory clarity and enterprise software budgets sustain its leadership.
6. Which region is the fastest-growing in the Drone Analytics Market and where are emerging opportunities?
Asia-Pacific is the fastest-growing region with a projected 31.2% CAGR through 2033, led by China, India, Japan, and Australia. India's agriculture drone subsidy programs and China's smart city inspections are major catalysts. LAMEA follows at 28.4% CAGR, with Middle East energy inspection and Brazil precision agriculture offering the strongest emerging demand.