Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Ammunition Market Size $16.9B by 2033, CAGR 3%
Ammunition Market
Ammunition Market Size $16.9B by 2033, CAGR 3%
Ammunition Market by Type (Small Caliber Ammunition, Medium Caliber Ammunition, Large Caliber Ammunition), by Application (Non-lethal, Lethal), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Oct 8, 2026|Base Year : 2025|Pages : 234
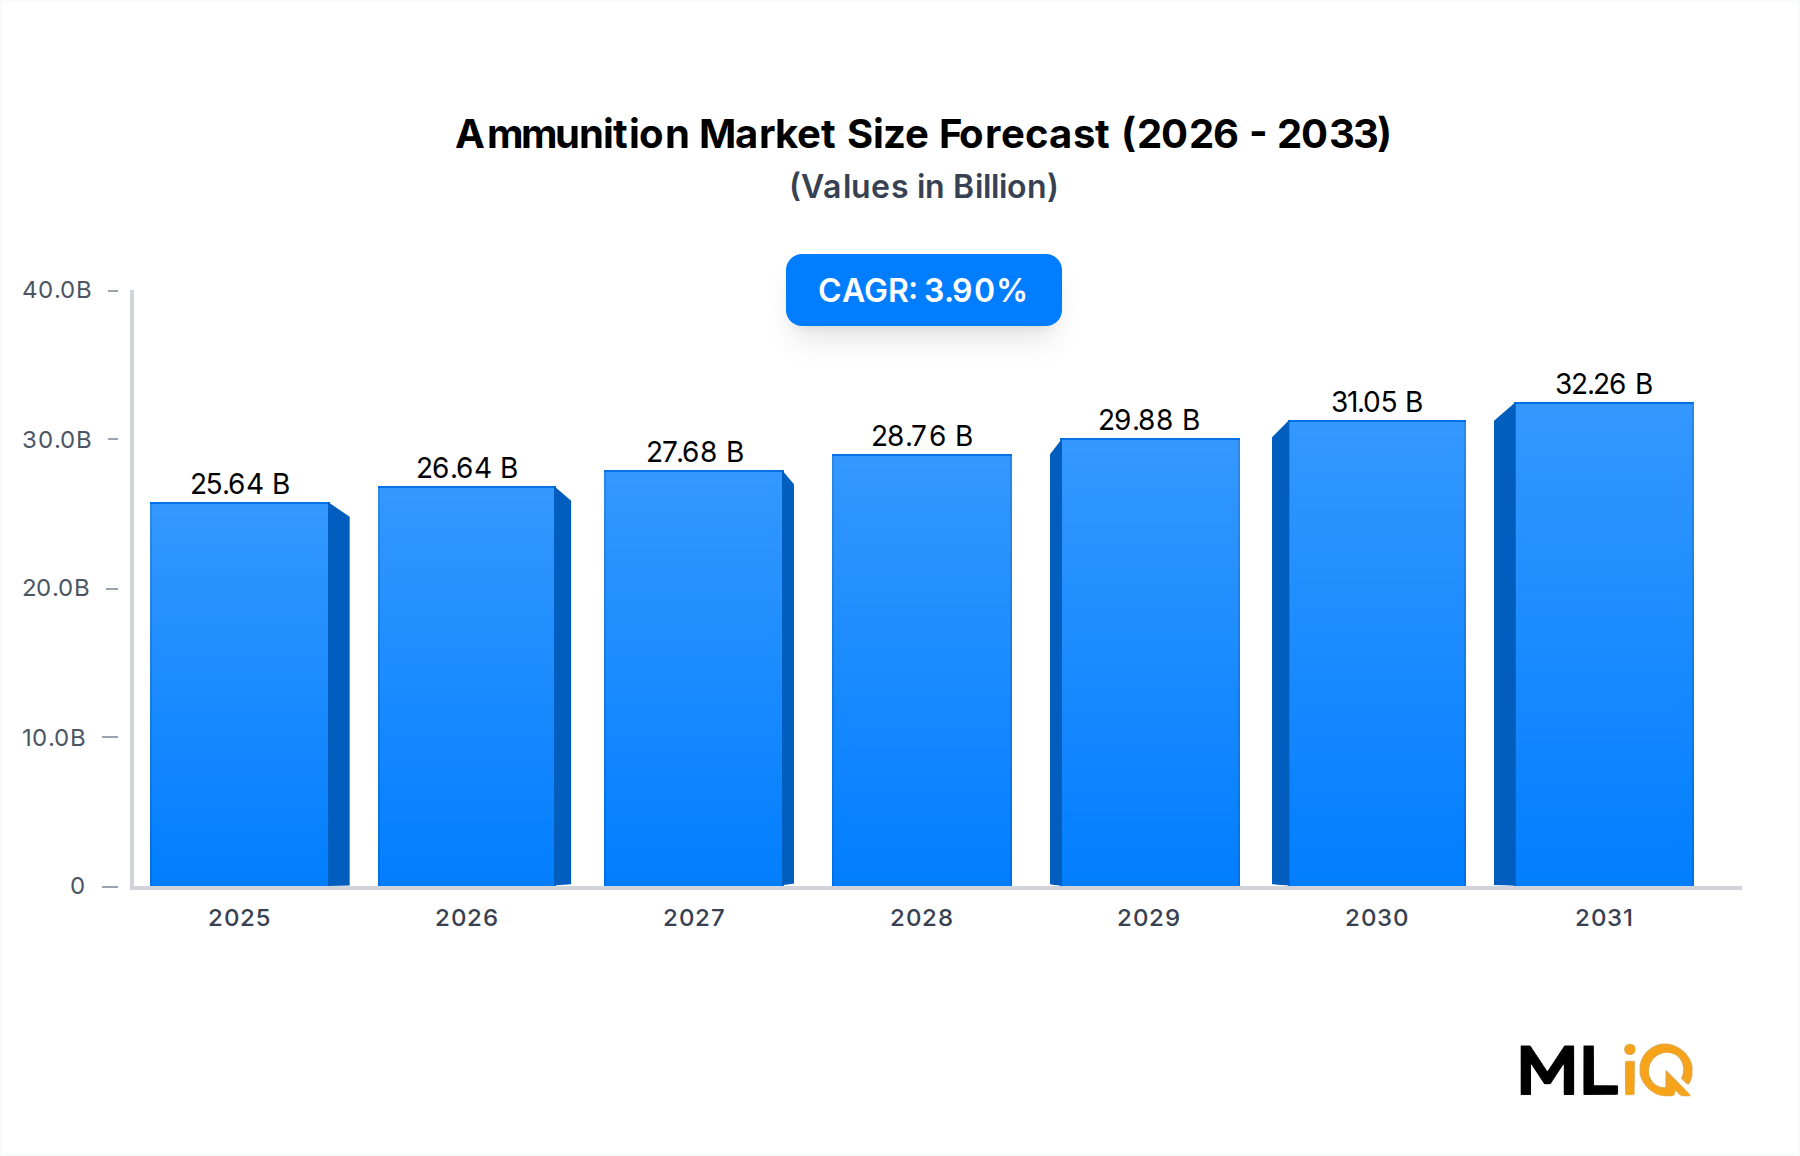
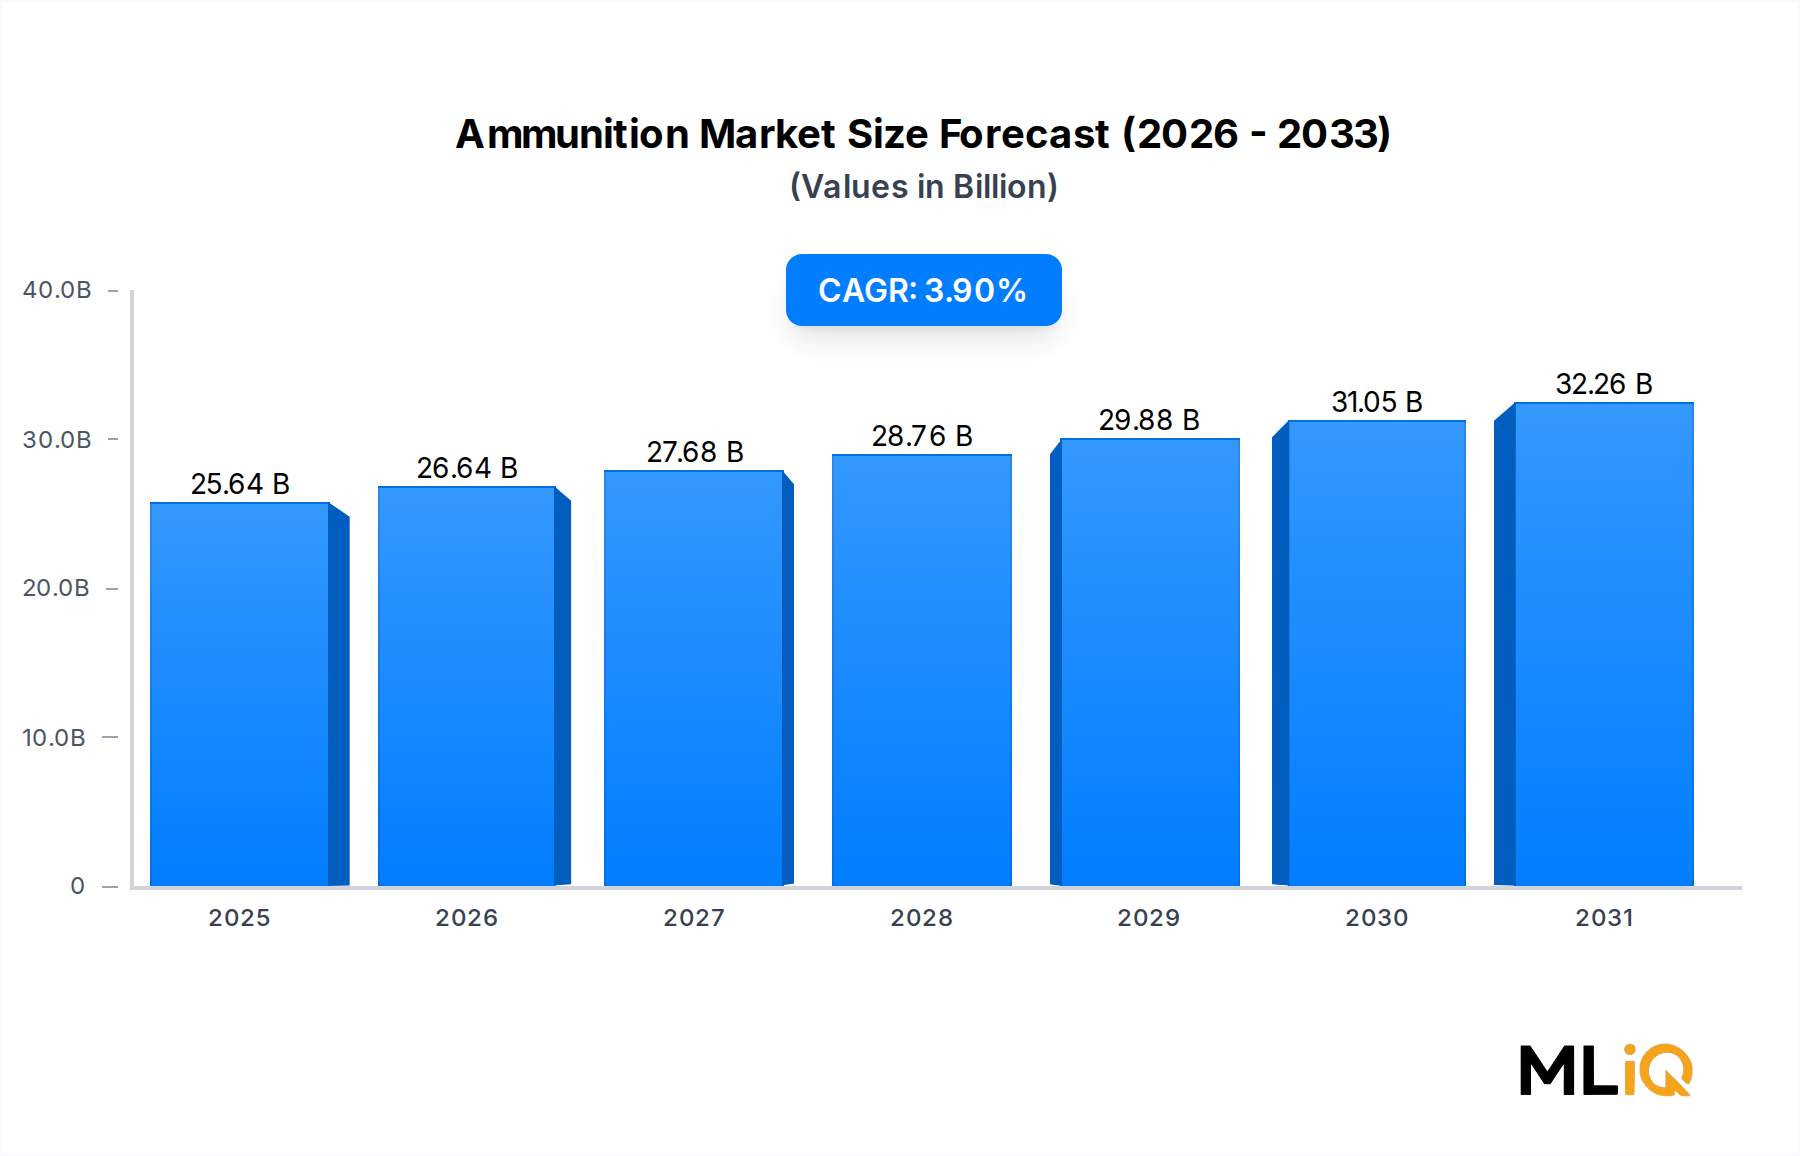
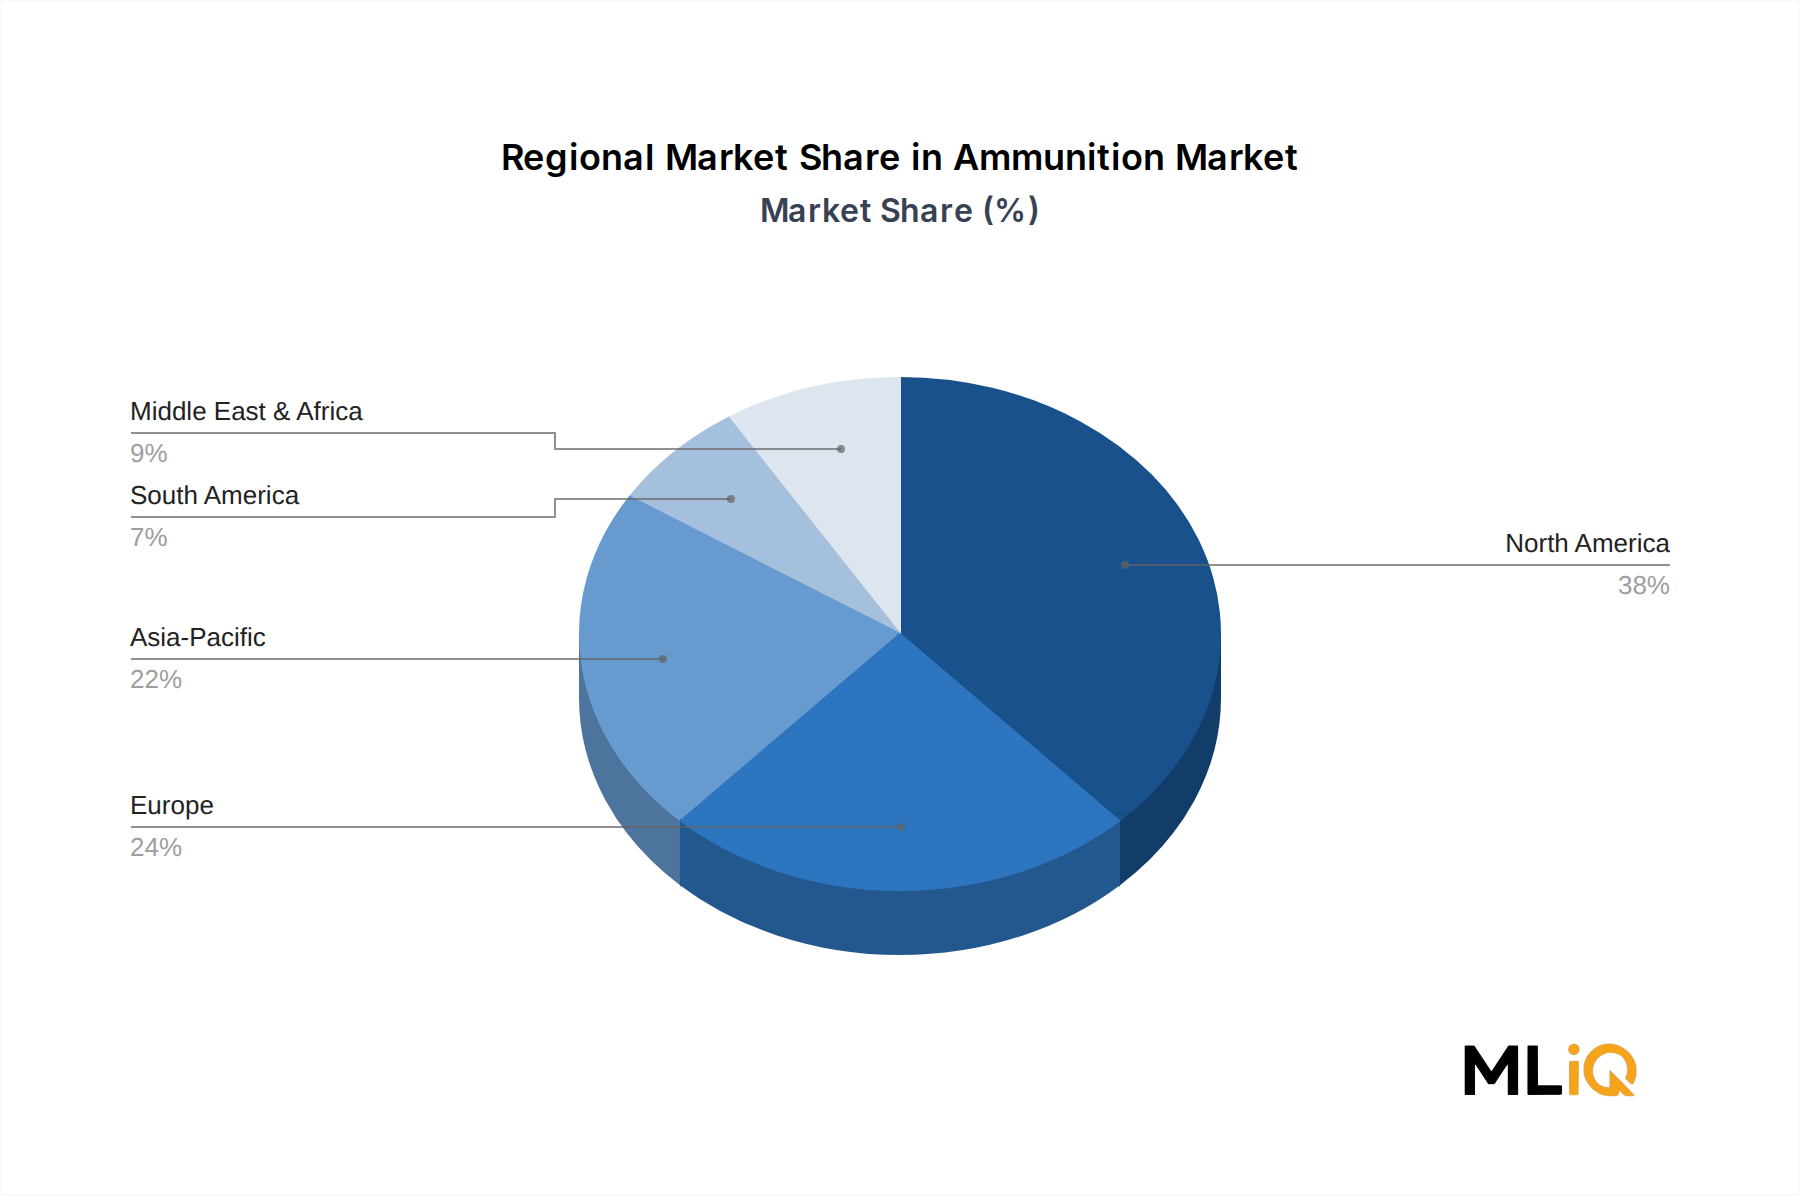
The global ammunition market is projected to grow from $12.93 billion in 2024 to $16.9 billion by 2033, registering a CAGR of 3%. This growth is underpinned by escalating military modernization programs, rising geopolitical tensions, and increased defense budgets worldwide. North America remains the largest market, accounting for 35% of global revenue, driven by the U.S. Department of Defense's procurement initiatives. The Small Caliber Ammunition Market dominates with a 45% share, fueled by high-volume training and law enforcement demand. Europe and Asia-Pacific are emerging as key growth corridors, with CAGRs of 3.2% and 3.5% respectively, due to NATO stockpile replenishment and China's military expansion.
Ammunition Market Size (In Billion)
20.0B
15.0B
10.0B
5.0B
0
13.32 B
2025
13.72 B
2026
14.13 B
2027
14.55 B
2028
14.99 B
2029
15.44 B
2030
15.90 B
2031
Key trends include the shift toward polymer-cased ammunition, which reduces weight and cost, and the integration of smart ammunition technologies. The market faces restraints such as stringent regulations and raw material price volatility. However, opportunities abound in less-lethal ammunition and advanced precision-guided munitions.
Segment Deep-Dive: Small Caliber Ammunition Dominance in Ammunition Market
Segment Analysis Matrix
Segment
CAGR (2025-2033)
Market Share (2024)
Key Demand Driver
Small Caliber Ammunition
2.8%
45%
Military training, law enforcement, civilian sport shooting
Medium Caliber Ammunition
3.2%
30%
Infantry weapons, armored vehicle cannons
Large Caliber Ammunition
4.1%
25%
Artillery systems, naval guns, tank munitions
Small Caliber Ammunition: The Revenue Backbone
The Small Caliber Ammunition Market accounted for 45% of global revenue in 2024, valued at $5.82 billion.
Dominated by 5.56mm, 7.62mm, and 9mm calibers, used in assault rifles, machine guns, and pistols.
Growth is steady at 2.8% CAGR, driven by sustained military and law enforcement consumption.
The Large Caliber Ammunition Market is the fastest-growing at 4.1% CAGR, propelled by artillery modernization (e.g., 155mm howitzers) and naval rearmament.
Margin pressures persist due to rising copper and steel costs, but scale efficiencies in large caliber production mitigate some impact.
Primary Market Drivers & Growth Restraints in Ammunition Market
Market Dynamics Impact Analysis
Factor Type
Description
Impact Level
Timeline
Driver
Rising geopolitical tensions and conflicts (e.g., Ukraine, Middle East)
High
Short term
Driver
Military modernization programs (e.g., Next Generation Squad Weapon)
High
Long term
Driver
Increasing defense budgets globally, exceeding $2.2 trillion in 2023
High
Medium term
Restraint
Stringent regulations (ITAR, UN Arms Trade Treaty)
Medium
Long term
Restraint
Raw material price volatility (copper, lead, propellants)
Medium
Short term
Restraint
Supply chain disruptions and production capacity constraints
Medium
Short term
The Military Ammunition Market is primarily driven by geopolitical instability. The war in Ukraine has led to a 30% increase in NATO ammunition production targets by 2025. The U.S. Army's Next Generation Squad Weapon program is expected to drive demand for 6.8mm ammunition. However, export controls and environmental regulations on lead ammunition pose challenges. The Defense Ammunition Market is also influenced by stockpile replenishment cycles, which are typically 5-7 years.
BAE Systems PLC: A global leader in large caliber ammunition, supplying artillery and naval gun systems. The company invested in expanding its production capacity in the UK and U.S. to meet rising demand.
Rheinmetall AG: Dominates the European medium and large caliber market, with recent contracts for 120mm mortar ammunition and modernization of Bundeswehr systems.
General Dynamics Corporation: Key supplier of small caliber ammunition to the U.S. military, operating the Lake City Army Ammunition Plant. The company is a major player in the Commercial Ammunition Market through its subsidiary.
Northrop Grumman Corporation: Focuses on precision-guided munitions and advanced lethal systems, including the Lethal Ammunition Market for next-generation weapons.
Nammo AS: Innovator in polymer-cased ammunition, partnering with MAC LLC to develop lightweight solutions for military applications.
Elbit Systems Ltd: Provides smart ammunition and artillery systems, with a strong presence in the Non-lethal Ammunition Market through less-lethal solutions.
Strategic Milestones & Recent Developments in Ammunition Market
Latest Strategic Moves
Date
Company
Event Type
Impact
Jan 2022
Rheinmetall AG
Contract
€27 million for 120mm mortar ammunition and modernization
Dec 2021
Indian Government
EOI
Purchase of 1,966 rounds of 155mm Terminally Guided Munitions
Apr 2021
Polish Armaments Group
Contract
>PLN 350 million for 122mm rockets and 120mm mortar ammunition
Feb 2021
Nammo
Partnership
Collaboration with MAC LLC for polymer-cased ammunition
January 2022: Rheinmetall AG secured a contract worth €27 million to deliver 120mm mortar ammunition and modernize Bundeswehr mortar systems, enhancing European artillery capabilities.
December 2021: The Indian government issued an Expression of Interest to purchase 1,966 rounds of 155mm Terminally Guided Munitions, boosting precision artillery.
April 2021: Polish Armaments Group received two contracts worth PLN 350 million to supply 122mm Feniks FHD rockets and 120mm RAK-HE-1 mortar ammunition.
February 2021: Nammo partnered with MAC LLC to develop polymer-cased ammunition, targeting weight reduction and cost savings for military and defense applications.
Regional Market Analysis & Growth Corridors for Ammunition Market
Regional Growth Comparison
Region
Projected CAGR (%)
Base Year Valuation ($B)
Primary Catalyst
Regulatory Stringency
North America
2.8%
4.53
Military modernization, stockpile replenishment
High
Europe
3.2%
3.23
NATO defense spending, Ukraine conflict
High
Asia-Pacific
3.5%
3.23
China military expansion, India modernization
Medium
LAMEA
3.0%
1.94
Regional conflicts, increasing defense budgets
Low to Medium
North America remains the largest market, with a 2.8% CAGR, driven by the U.S. Department of Defense's ammunition procurement and the Law Enforcement Ammunition Market.
Europe is the fastest-growing region at 3.2% CAGR, fueled by NATO members increasing stockpiles and Germany's €100 billion defense fund.
Asia-Pacific follows closely at 3.5% CAGR, with China and India investing in indigenous ammunition production. The Commercial Ammunition Market in the U.S. is mature, while Asia-Pacific shows potential.
LAMEA (Latin America, Middle East & Africa) grows at 3.0% CAGR, with demand from conflict zones and security forces.
Customer Segmentation & Buying Behavior in Ammunition Market
Military and Defense: Accounts for 70% of demand, with procurement driven by government contracts, long-term agreements, and urgent operational needs. Decision-making prioritizes reliability, interoperability, and cost per round.
Law Enforcement: Represents 15% of the market, with agencies increasingly adopting Non-lethal Ammunition Market products for crowd control. Buying behavior is influenced by budget cycles and training requirements.
Civilian/Commercial: Holds 15% share, dominated by hunting and sport shooting. Price elasticity is high, with consumers sensitive to price fluctuations and regulatory changes.
Procurement channels are shifting toward digital platforms for commercial ammunition, while military purchases remain through traditional defense acquisition processes. Recent cycles show a preference for bulk purchasing and multi-year contracts to secure supply.
Investment, M&A & Funding Activity in Ammunition Market
M&A Activity: The ammunition sector has seen increased consolidation, with companies like Northrop Grumman acquiring smaller precision munition developers. In 2023, Rheinmetall acquired a Spanish ammunition manufacturer to expand European capacity.
Private Equity/Venture Capital: Investments are flowing into advanced materials (polymer casings) and smart ammunition startups. Nammo's partnership with MAC LLC is an example of strategic funding in innovative ammunition technologies.
Strategic Partnerships: Collaborations between defense contractors and tech firms are rising to integrate guidance systems into large caliber rounds. The Large Caliber Ammunition Market is attracting capital for precision-guided artillery.
High-growth sub-segments include Non-lethal Ammunition Market and Medium Caliber Ammunition Market, with CAGRs of 4.5% and 3.2% respectively. Acquirers are targeting companies with proprietary technologies in these areas.
Ammunition Market Segmentation
1. Type
1.1. Small Caliber Ammunition
1.2. Medium Caliber Ammunition
1.3. Large Caliber Ammunition
2. Application
2.1. Non-lethal
2.2. Lethal
Ammunition Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Ammunition Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 3% from 2020-2034
Segmentation
By Type
Small Caliber Ammunition
Medium Caliber Ammunition
Large Caliber Ammunition
By Application
Non-lethal
Lethal
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Type
5.1.1. Small Caliber Ammunition
5.1.2. Medium Caliber Ammunition
5.1.3. Large Caliber Ammunition
5.2. Market Analysis, Insights and Forecast - by Application
5.2.1. Non-lethal
5.2.2. Lethal
5.3. Market Analysis, Insights and Forecast - by Region
5.3.1. North America
5.3.2. South America
5.3.3. Europe
5.3.4. Middle East & Africa
5.3.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Type
6.1.1. Small Caliber Ammunition
6.1.2. Medium Caliber Ammunition
6.1.3. Large Caliber Ammunition
6.2. Market Analysis, Insights and Forecast - by Application
6.2.1. Non-lethal
6.2.2. Lethal
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Type
7.1.1. Small Caliber Ammunition
7.1.2. Medium Caliber Ammunition
7.1.3. Large Caliber Ammunition
7.2. Market Analysis, Insights and Forecast - by Application
7.2.1. Non-lethal
7.2.2. Lethal
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Type
8.1.1. Small Caliber Ammunition
8.1.2. Medium Caliber Ammunition
8.1.3. Large Caliber Ammunition
8.2. Market Analysis, Insights and Forecast - by Application
8.2.1. Non-lethal
8.2.2. Lethal
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Type
9.1.1. Small Caliber Ammunition
9.1.2. Medium Caliber Ammunition
9.1.3. Large Caliber Ammunition
9.2. Market Analysis, Insights and Forecast - by Application
9.2.1. Non-lethal
9.2.2. Lethal
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Type
10.1.1. Small Caliber Ammunition
10.1.2. Medium Caliber Ammunition
10.1.3. Large Caliber Ammunition
10.2. Market Analysis, Insights and Forecast - by Application
10.2.1. Non-lethal
10.2.2. Lethal
11. Competitive Analysis
11.1. Company Profiles
11.1.1. BAE Systems PLC
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Rheinmetall AG
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Elbit Systems Ltd
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Nexter Group
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. General Dynamics Corporation
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Nammo AS
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. RUAG Group
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Singapore Technologies Engineering Ltd
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Denel SOC Ltd
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Northrop Grumman Corporation
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. MESKO SA
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. CBC Global Ammunition
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. Indian Ordnance Factories
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.1.14. Saab AB
11.1.14.1. Company Overview
11.1.14.2. Products
11.1.14.3. Company Financials
11.1.14.4. SWOT Analysis
11.1.15. Hanwha Corporation
11.1.15.1. Company Overview
11.1.15.2. Products
11.1.15.3. Company Financials
11.1.15.4. SWOT Analysis
11.1.16. ARSENAL JSCo
11.1.16.1. Company Overview
11.1.16.2. Products
11.1.16.3. Company Financials
11.1.16.4. SWOT Analysis
11.1.17. ASELSAN A
11.1.17.1. Company Overview
11.1.17.2. Products
11.1.17.3. Company Financials
11.1.17.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Ammunition Market Revenue Breakdown (billion, %) by Region 2026 & 2034
Figure 2: North America Ammunition Market Revenue (billion), by Type 2026 & 2034
Figure 3: North America Ammunition Market Revenue Share (%), by Type 2026 & 2034
Figure 4: North America Ammunition Market Revenue (billion), by Application 2026 & 2034
Figure 5: North America Ammunition Market Revenue Share (%), by Application 2026 & 2034
Figure 6: North America Ammunition Market Revenue (billion), by Country 2026 & 2034
Figure 7: North America Ammunition Market Revenue Share (%), by Country 2026 & 2034
Figure 8: South America Ammunition Market Revenue (billion), by Type 2026 & 2034
Figure 9: South America Ammunition Market Revenue Share (%), by Type 2026 & 2034
Figure 10: South America Ammunition Market Revenue (billion), by Application 2026 & 2034
Figure 11: South America Ammunition Market Revenue Share (%), by Application 2026 & 2034
Figure 12: South America Ammunition Market Revenue (billion), by Country 2026 & 2034
Figure 13: South America Ammunition Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Ammunition Market Revenue (billion), by Type 2026 & 2034
Figure 15: Europe Ammunition Market Revenue Share (%), by Type 2026 & 2034
Figure 16: Europe Ammunition Market Revenue (billion), by Application 2026 & 2034
Figure 17: Europe Ammunition Market Revenue Share (%), by Application 2026 & 2034
Figure 18: Europe Ammunition Market Revenue (billion), by Country 2026 & 2034
Figure 19: Europe Ammunition Market Revenue Share (%), by Country 2026 & 2034
Figure 20: Middle East & Africa Ammunition Market Revenue (billion), by Type 2026 & 2034
Figure 21: Middle East & Africa Ammunition Market Revenue Share (%), by Type 2026 & 2034
Figure 22: Middle East & Africa Ammunition Market Revenue (billion), by Application 2026 & 2034
Figure 23: Middle East & Africa Ammunition Market Revenue Share (%), by Application 2026 & 2034
Figure 24: Middle East & Africa Ammunition Market Revenue (billion), by Country 2026 & 2034
Figure 25: Middle East & Africa Ammunition Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Asia Pacific Ammunition Market Revenue (billion), by Type 2026 & 2034
Figure 27: Asia Pacific Ammunition Market Revenue Share (%), by Type 2026 & 2034
Figure 28: Asia Pacific Ammunition Market Revenue (billion), by Application 2026 & 2034
Figure 29: Asia Pacific Ammunition Market Revenue Share (%), by Application 2026 & 2034
Figure 30: Asia Pacific Ammunition Market Revenue (billion), by Country 2026 & 2034
Figure 31: Asia Pacific Ammunition Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Ammunition Market Revenue billion Forecast, by Type 2020 & 2034
Table 46: Rest of Asia Pacific Ammunition Market Revenue (billion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
We conduct 70-80% primary research through interviews with industry executives, procurement managers, and technical experts.
Key company types interviewed: Small Caliber Ammunition Manufacturers, Large Caliber Artillery Shell Producers, Polymer-Cased Ammunition Developers, Ammunition Component Suppliers, Ammunition Loading Equipment Providers.
Stakeholder job titles: Director of Ammunition Procurement, Defense Program Manager, Ordnance Systems Engineer, Military Logistics Officer.
Primary research ensures granular insights into pricing, demand drivers, and supply chain dynamics.
Data triangulation validates primary findings with published reports and regulatory filings.
Demand Modeling & Market Estimation
We employ both top-down and bottom-up methodologies simultaneously.
Bottom-up calculation uses quantitative metrics: number of active military personnel, annual military training ammunition consumption per soldier, defense budget allocation for ammunition procurement, number of law enforcement agencies and their ammunition expenditure.
Top-down approach analyzes global defense spending and ammunition share.
Multi-level data triangulation ensures accuracy, with estimated data accuracy level of 85-90%.
Data Accuracy & Quality Check
Every report is updated to the date of purchase.
Cross-verification with multiple sources, including company financials and government contracts.
Quality checks include outlier detection and consistency analysis.
Final validation by senior analysts ensures reliability.
Frequently Asked Questions
1. How are ammunition prices trending and what is driving cost structure changes?
Ammunition prices have risen 5-7% annually since 2022 due to higher raw material costs (copper, lead, propellants) and increased demand. Cost structure is shifting toward advanced materials like polymer casings, which can reduce weight and cost by up to 20%. Manufacturers are investing in automation to offset labor cost increases.
2. What is the current size of the ammunition market and what is its projected CAGR through 2033?
The global ammunition market was valued at $12.93 billion in 2024 and is projected to reach $16.9 billion by 2033, growing at a CAGR of 3%. This growth is driven by military modernization programs and rising defense budgets in North America and Asia-Pacific. The market is expected to see steady demand from law enforcement and civilian sectors.
3. Which segments and product types dominate the ammunition market?
Small caliber ammunition holds the largest share, accounting for approximately 45% of the market in 2024, driven by high-volume consumption in military and law enforcement training. Large caliber ammunition is the fastest-growing segment, with a CAGR of 4.1%, due to increased artillery and tank modernization. By application, lethal ammunition dominates, representing over 85% of the market.
4. What are the primary growth drivers and demand catalysts for ammunition?
Key drivers include escalating geopolitical tensions, military modernization programs (e.g., U.S. Army's Next Generation Squad Weapon), and rising defense expenditure globally, which exceeded $2.2 trillion in 2023. Additionally, the war in Ukraine has accelerated ammunition stockpile replenishment, with NATO members committing to increase production capacity by 30% by 2025. These factors collectively boost demand for small, medium, and large caliber ammunition.
5. How do export-import dynamics shape the global ammunition trade?
The United States is the largest exporter of ammunition, with exports valued at over $3 billion in 2023, followed by Russia and China. Import flows are concentrated in conflict zones and allied nations; for instance, European countries increased imports by 40% in 2023 to replenish stocks. Trade is regulated by ITAR and international arms agreements, impacting supply chain strategies.
6. Who are the main end-users of ammunition and how are their demand patterns evolving?
The primary end-users are military and defense forces, accounting for about 70% of global demand, followed by law enforcement (15%) and civilian markets (15%). Military demand is surging due to training and combat operations, while law enforcement agencies are adopting less-lethal ammunition, growing at 4.5% annually. Civilian demand remains stable, influenced by hunting and sport shooting trends.