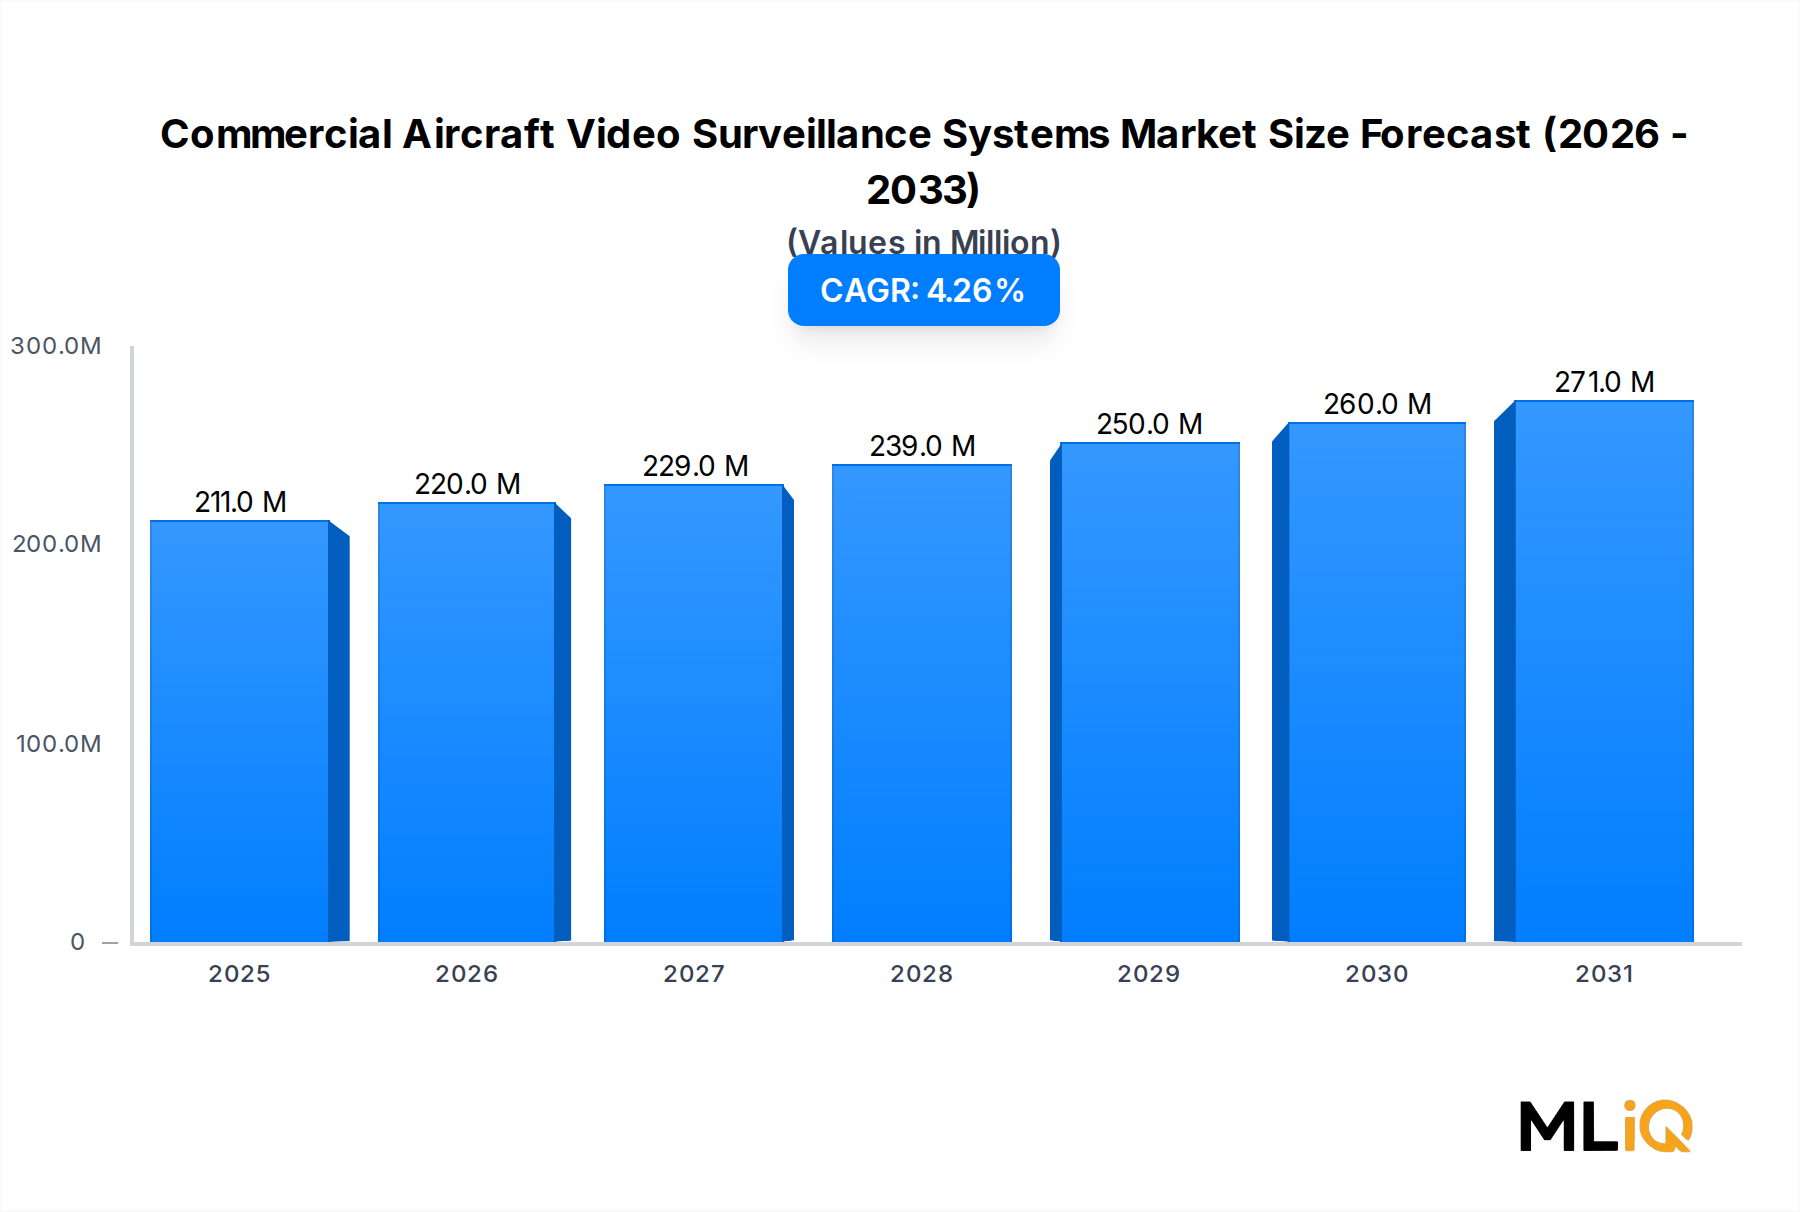
The Commercial Aircraft Video Surveillance Systems Market exhibits distinct regional performance profiles shaped by fleet size, regulatory maturity, airline investment capacity, and aircraft delivery pipelines.
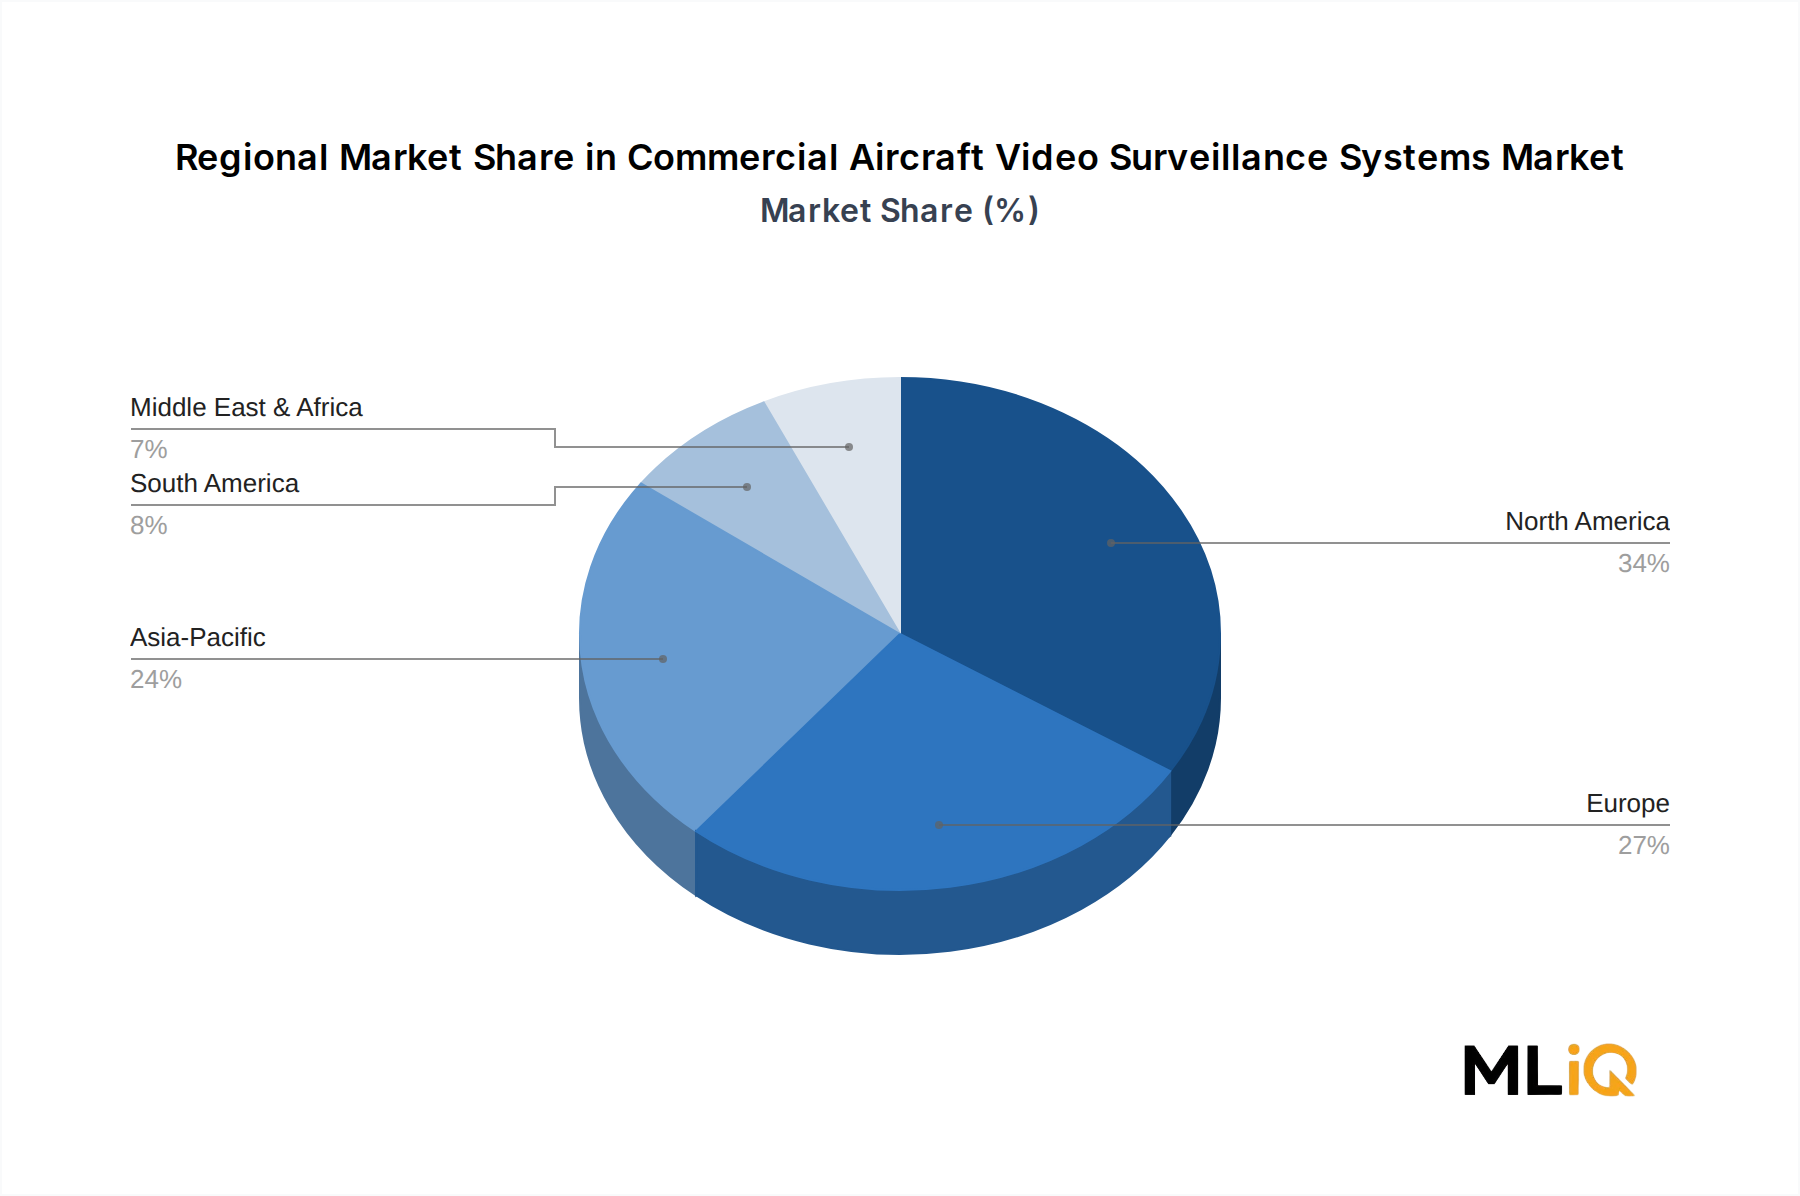
North America represents the most mature regional market, accounting for an estimated 32–35% of global revenue. The United States drives the bulk of this share, underpinned by one of the world's largest commercial fleets and a dense network of major carriers and low-cost operators investing in fleet modernization. While the FAA has not yet enacted binding cabin surveillance mandates equivalent to EASA's cockpit door requirements, voluntary adoption driven by airline security policies and post-pandemic operational restructuring is sustaining demand. Canada and Mexico contribute incrementally through regional carrier programs and MRO-driven retrofit activities. The North American market is growing at approximately 3.5% CAGR, reflecting its relative saturation compared to emerging regions.
Europe is the regulatory epicenter of the market, with EASA mandates having directly catalyzed cockpit door surveillance procurement since 2020. The United Kingdom, Germany, France, and the Nordics collectively house major carriers operating dense narrowbody and widebody fleets. European market growth is estimated at 4.0% CAGR, marginally below the global average, as a significant portion of compliance-driven procurement has already occurred in the initial mandate implementation cycle.
Asia Pacific is the fastest-growing regional market, projected to expand at 5.5–6.0% CAGR through the forecast horizon. China, India, and ASEAN nations are adding commercial aircraft at rates well above the global average. China's domestic aviation fleet is expected to double by 2040 according to CAAC projections, while India's fleet is scaling rapidly under government-backed regional connectivity initiatives such as UDAN. Japan and South Korea maintain mature aviation markets with ongoing fleet renewal programs. The convergence of fleet growth and evolving local regulatory frameworks is creating a sustained multi-year demand cycle.
The Middle East and Africa region, anchored by Gulf Cooperation Council carriers including Emirates, Qatar Airways, and Etihad, represents a high-value but volume-concentrated market. GCC carriers operate modern widebody fleets with strong surveillance system penetration, while African markets remain underpenetrated, offering longer-term growth optionality as aviation infrastructure investment accelerates. Regional CAGR is estimated at approximately 4.8%.
South America, led by Brazil and Argentina, presents a moderate growth profile at approximately 3.8% CAGR, constrained by airline financial fragility and slower fleet renewal cycles, though low-cost carrier expansion across the continent is creating incremental retrofit demand.