The Marine Propulsion Engine Market exhibits pronounced regional variation in growth rates, technology preferences, and demand drivers, reflecting differences in maritime trade intensity, regulatory environments, and shipbuilding capacity.
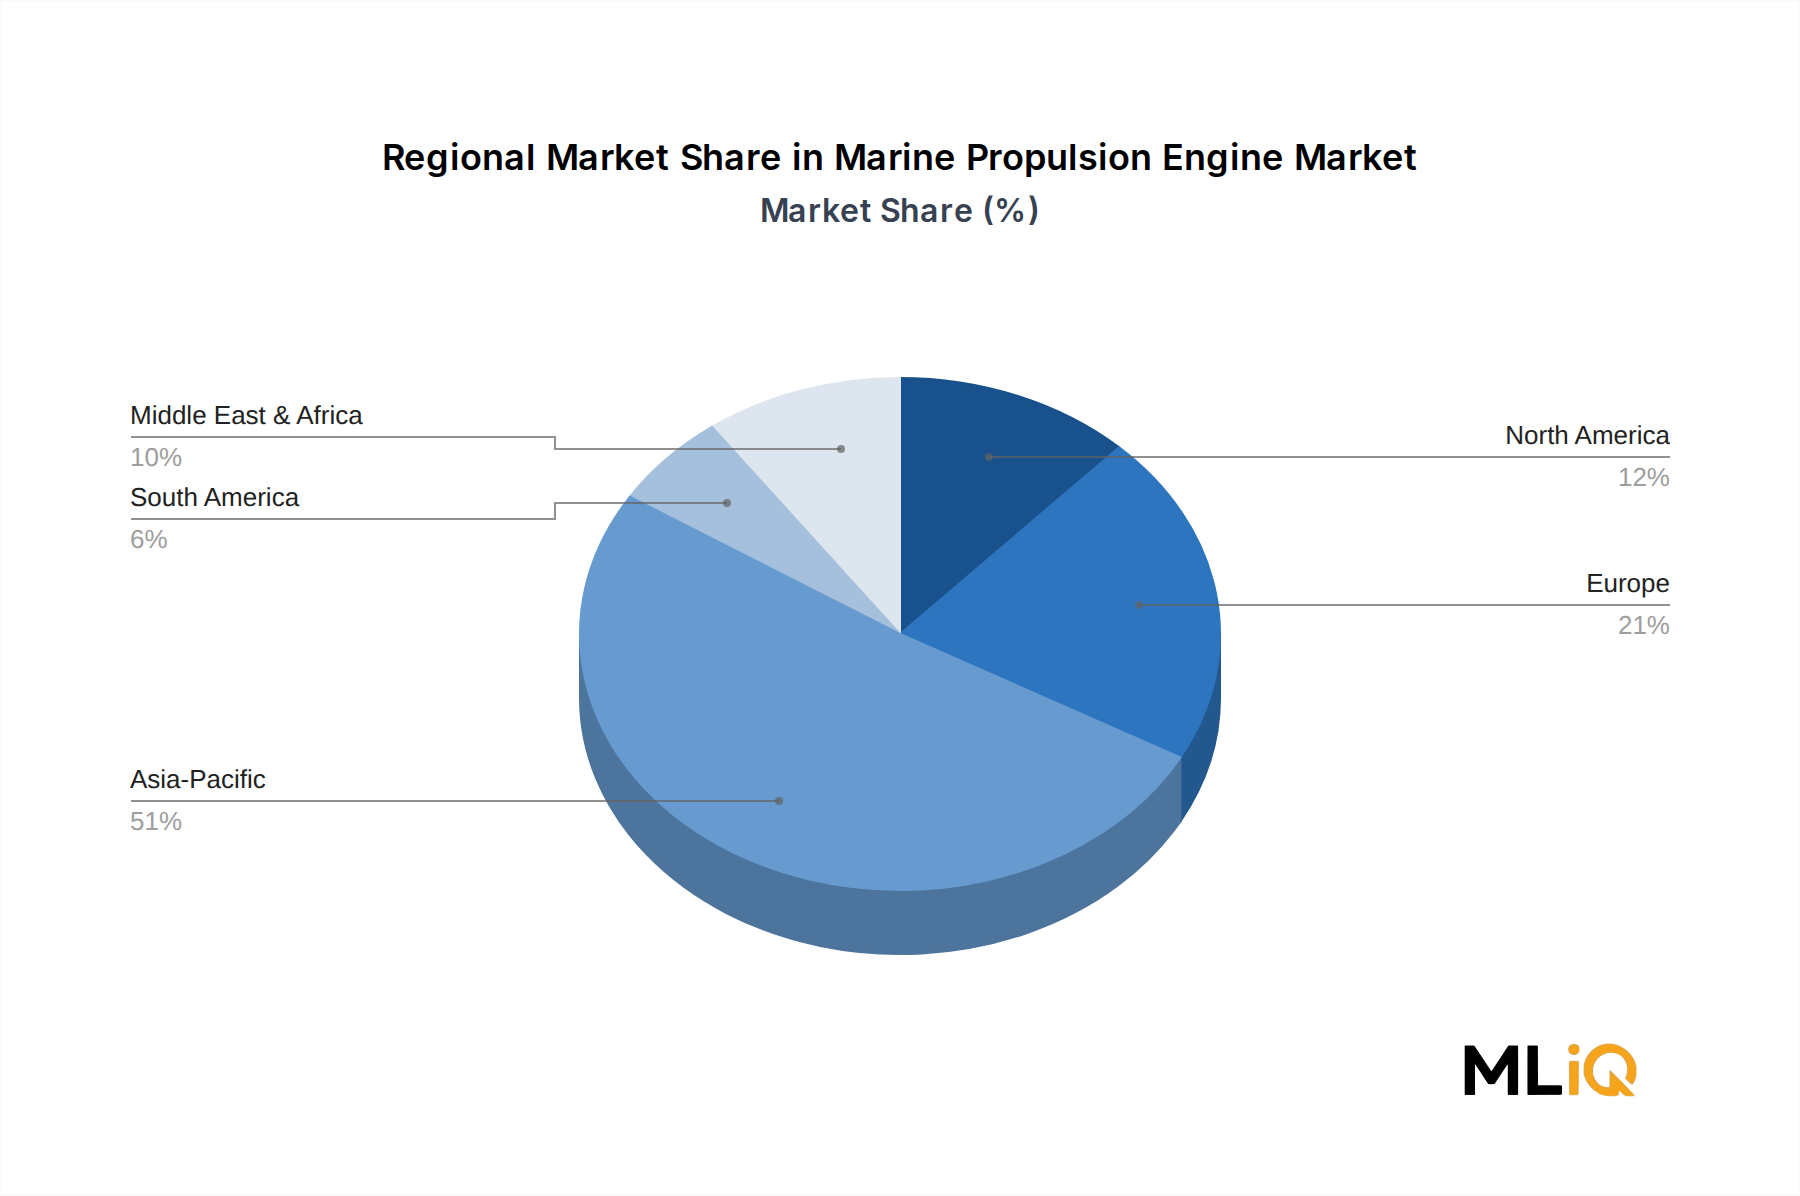
Asia Pacific — Largest Revenue Share: Asia Pacific dominates global market revenue with an estimated share exceeding 45% of total value, anchored by China, South Korea, and Japan — the world's three largest shipbuilding nations by gross tonnage output. China alone accounts for more than 40% of global newbuild orders by compensated gross tonnage as of 2023. Regional CAGR is estimated at approximately 4.5%, slightly above the global average, driven by robust domestic shipbuilding subsidies, expanding LNG trade infrastructure, and growing ASEAN intraregional container traffic.
Europe — Technology Innovation Hub: Europe represents the second largest market by revenue, commanding approximately 25% share, led by Norway, Germany, Greece (as a vessel-owning nation), and Finland. The region is characterized by above-average adoption of LNG, methanol, and hybrid propulsion solutions, supported by stringent EU maritime emissions regulations and the EU Emissions Trading System (ETS) extension to shipping effective January 2024. Regional CAGR is projected at 3.8%, reflecting a more mature fleet base but sustained retrofit and newbuild activity.
North America — Steady Demand from Inland and Offshore: North America accounts for approximately 15% of global marine propulsion revenue, driven by Jones Act shipping, inland waterway barge fleets on the Mississippi-Ohio river system, and offshore supply vessel demand in the Gulf of Mexico. The United States is a significant consumer of medium-speed diesel and gas engines in both commercial and Coast Guard applications. Regional CAGR is estimated at 3.5%, supported by offshore wind service vessel procurement along the Atlantic coast.
Middle East & Africa — Fastest-Growing Region: The Middle East & Africa region, while currently representing approximately 8–9% of global revenue, is the fastest-growing market with an estimated regional CAGR of 5.2%. The GCC nations are driving demand through offshore energy expansion, port infrastructure investment, and newbuild tanker procurement tied to sustained crude oil export volumes. Saudi Arabia's Vision 2030 maritime development program and the UAE's port expansion initiatives are key policy catalysts.
South America — Emerging Growth Market: South America contributes approximately 5–6% of global market revenue, with Brazil as the primary market driven by Petrobras-linked offshore vessel demand and cabotage trade expansion. Regional CAGR is estimated at 4.0%, broadly in line with the global average, with Argentina and Chile contributing modest incremental volumes from fisheries and naval procurement segments.