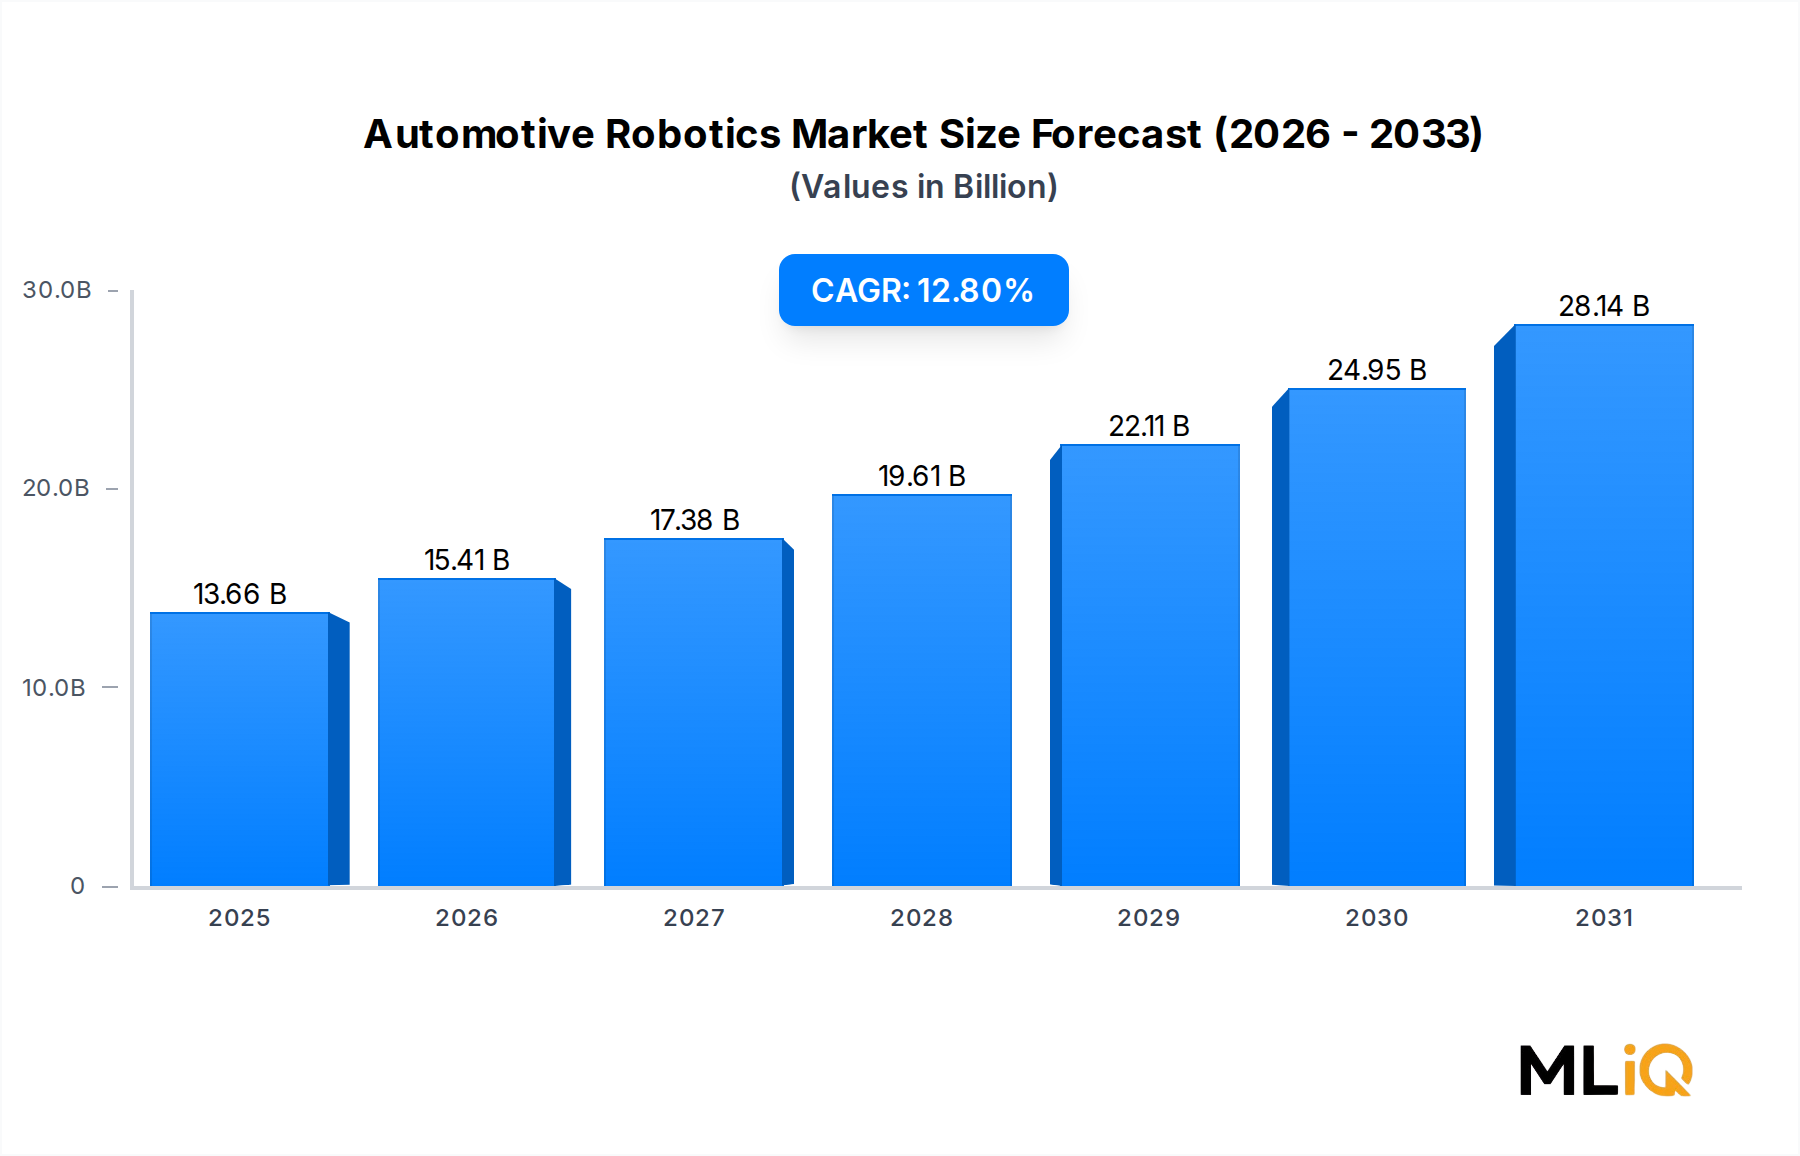
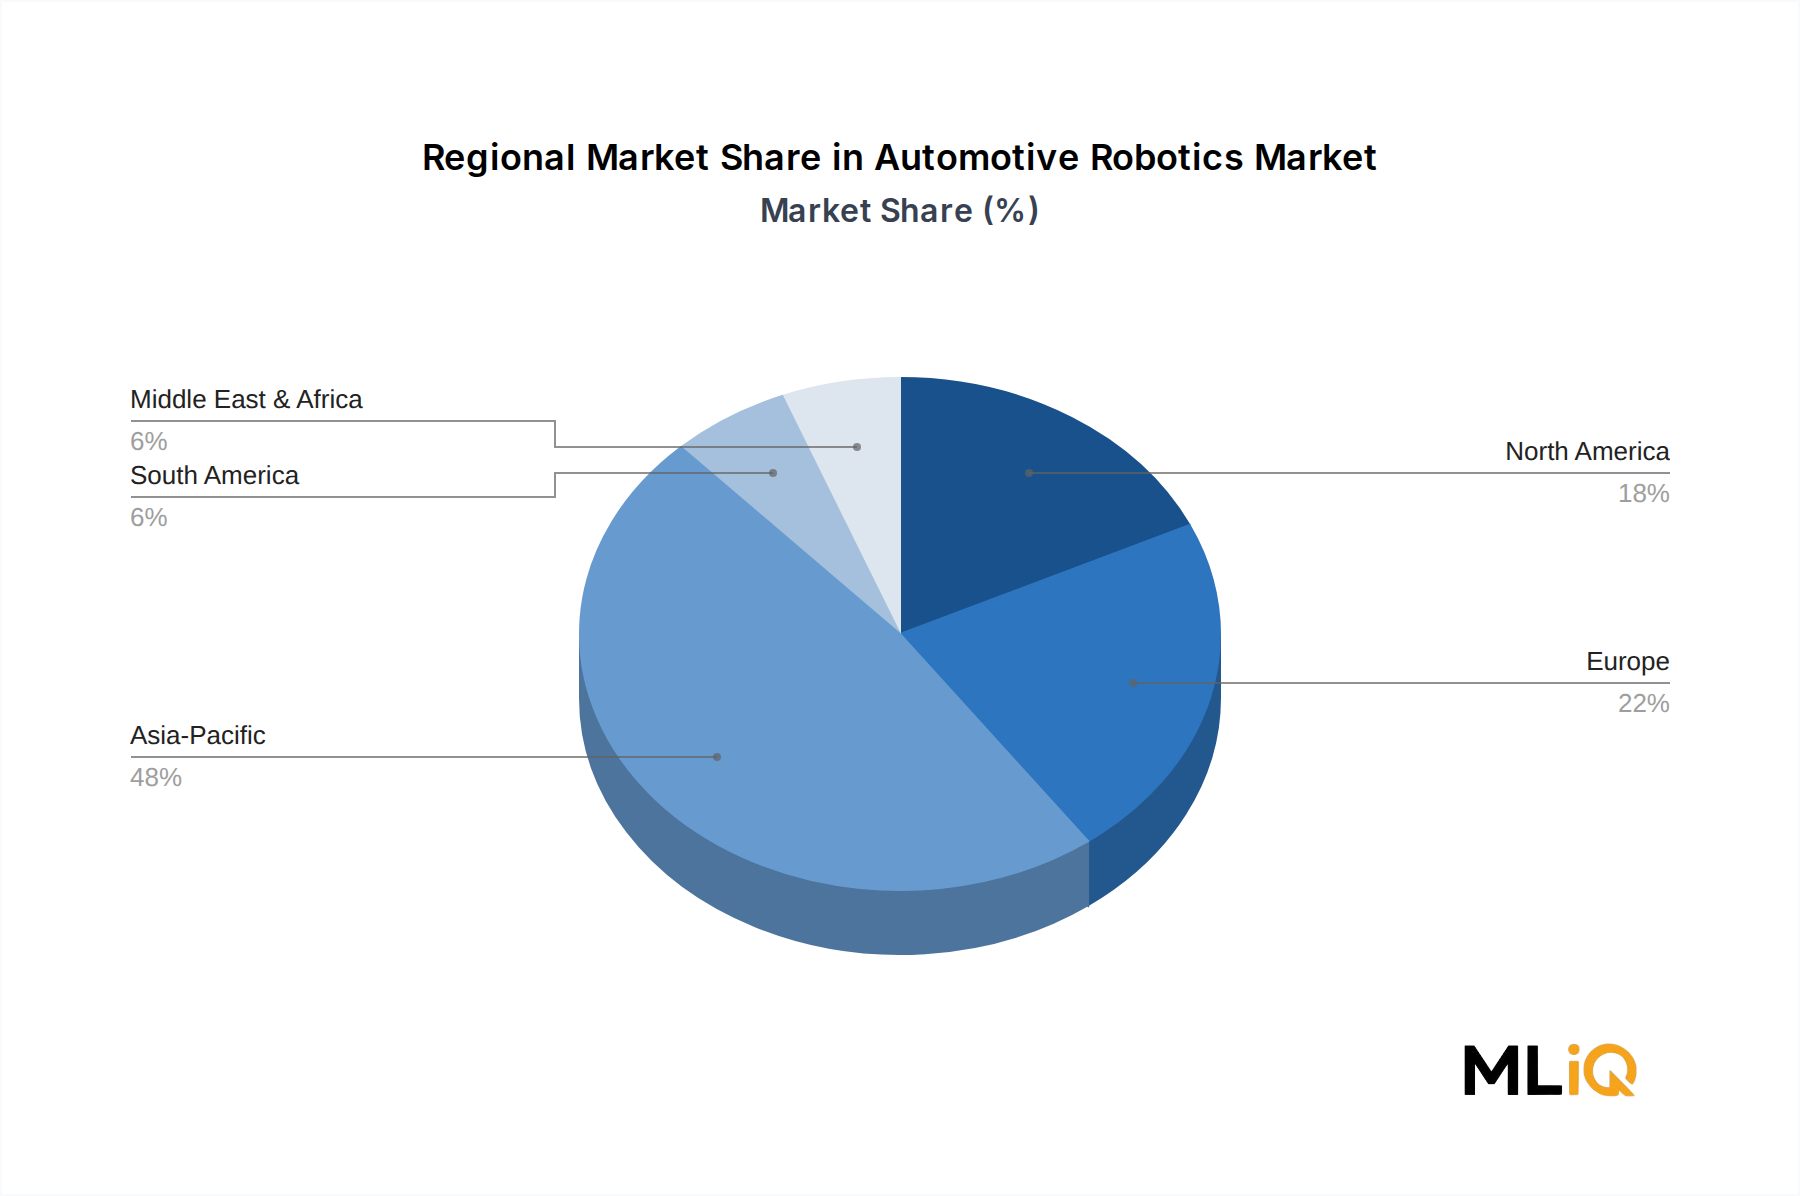
The Automotive Robotics Market is propelled by a set of quantifiable, structurally anchored drivers while simultaneously navigating constraints that moderate near-term adoption velocity.
Driver 1: Electric Vehicle Platform Investment. Global EV production is expected to surpass 40 million units annually by the early 2030s, with major OEMs—Volkswagen, General Motors, Toyota, and BYD—committing to dedicated EV assembly facilities that require entirely new robotic tooling for battery module handling, cell stacking, and pack integration. Each new dedicated EV plant represents robotic investment in the range of $200 million to $500 million, depending on production volume targets.
Driver 2: Labor Cost and Availability Pressures. In the United States, average hourly compensation for manufacturing workers in motor vehicle assembly exceeded $35 in recent years when benefits are included. In Germany, comparable figures approach €45 per hour. At these labor cost levels, the payback period for a standard six-axis welding robot has compressed to 18–24 months in high-volume applications, making automation economically compelling across a broader tier of suppliers.
Driver 3: Quality and Traceability Requirements. Increasingly stringent homologation standards—including IATF 16949 quality management certification and OEM-specific supplier quality agreements—demand documented process consistency that robotic systems inherently provide through data logging and in-cycle monitoring. Each robotic weld, paint pass, or material handling cycle can be timestamped, logged, and traced, enabling root-cause analysis that manual operations cannot replicate at scale.
Constraint 1: High Initial Capital Expenditure. A fully integrated robotic welding cell, inclusive of robot, controller, welding equipment, safety fencing, programming, and commissioning, typically costs between $150,000 and $400,000 per cell. For smaller tier-two and tier-three suppliers operating on thin margins, this capital threshold remains a meaningful barrier despite declining hardware prices.
Constraint 2: Skilled Integration and Maintenance Shortage. The global shortage of robotics engineers, systems integrators, and maintenance technicians capable of supporting advanced automotive robotic installations is a documented constraint. This talent gap extends project timelines, increases integration costs, and creates operational risk for facilities with limited in-house expertise. Industry surveys consistently identify skilled labor availability as the primary implementation obstacle for mid-market automotive suppliers.
Constraint 3: Transition Complexity from ICE to EV Platforms. Legacy robotic installations calibrated for internal combustion engine vehicle production often cannot be reprogrammed and redeployed for EV-specific tasks without significant retooling investment, creating a sunk-cost drag on net new automation spending.