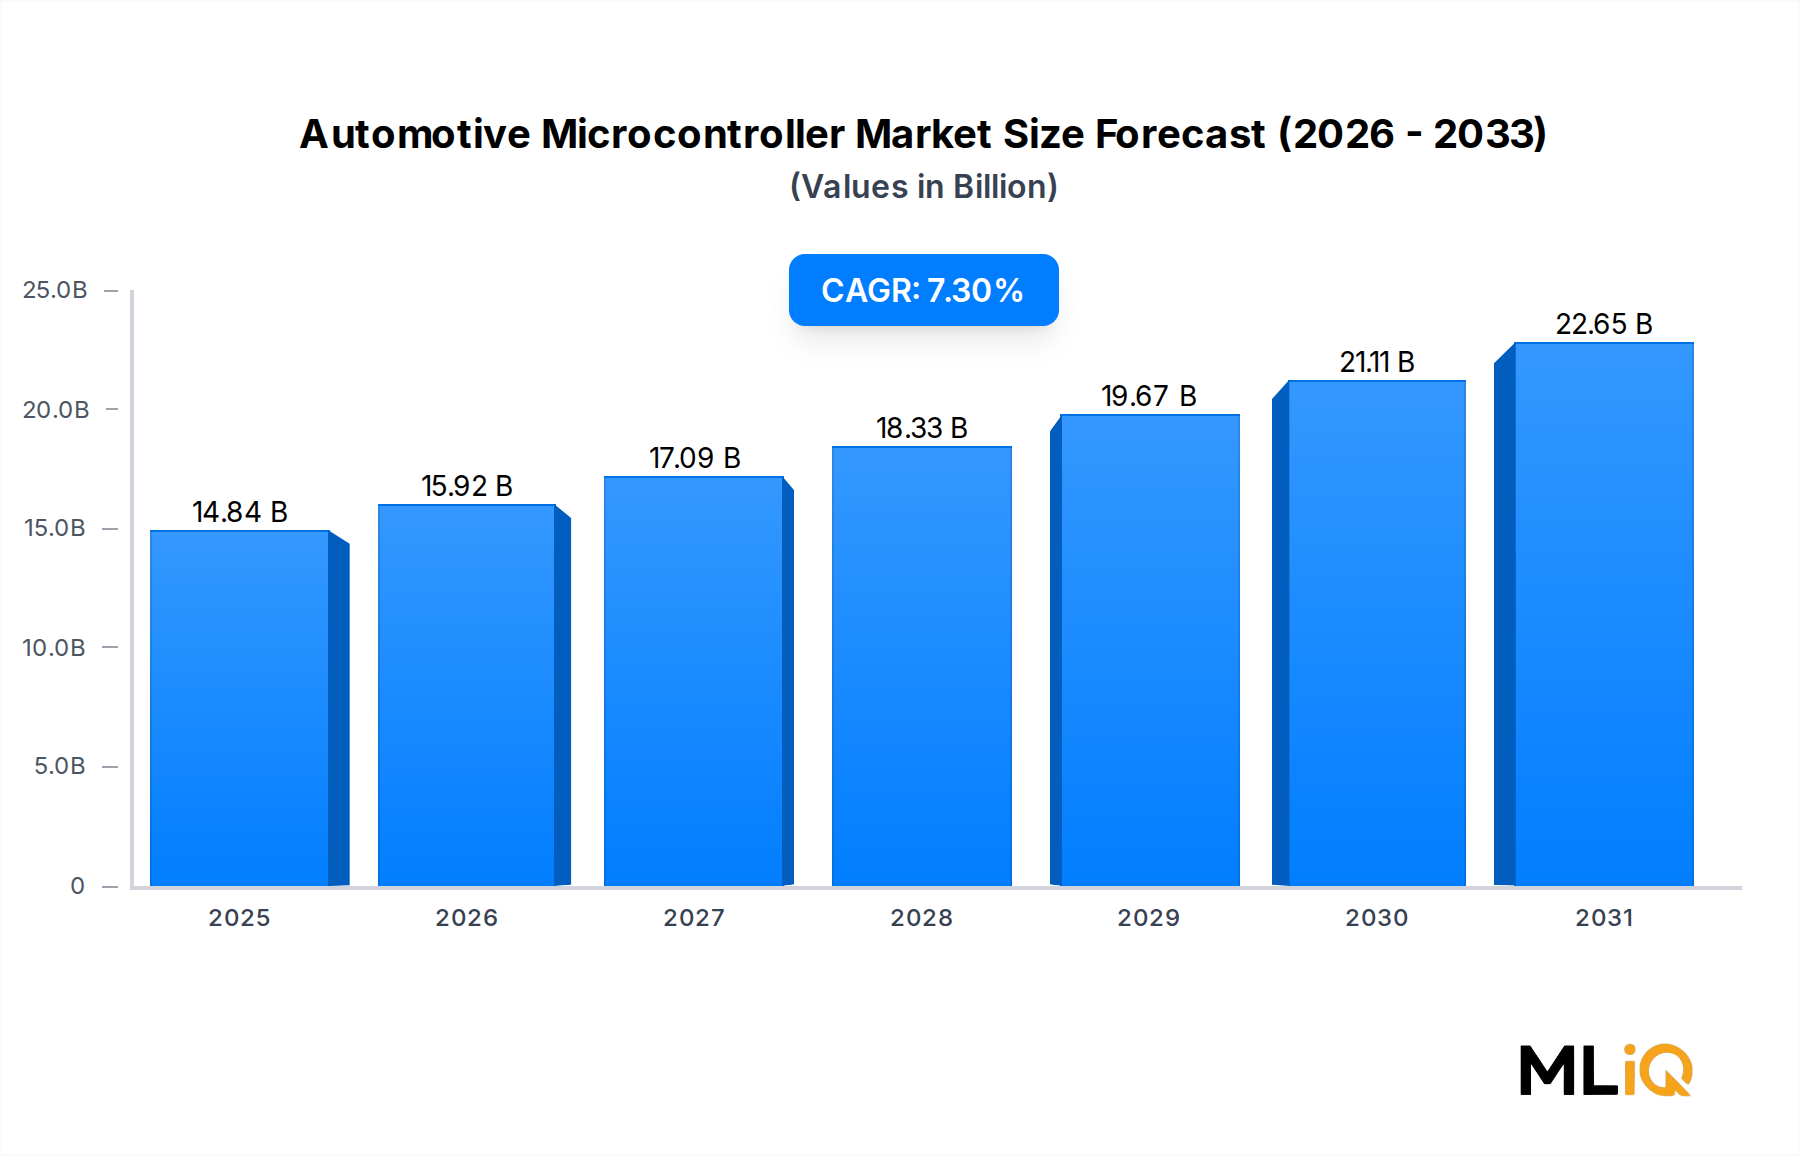
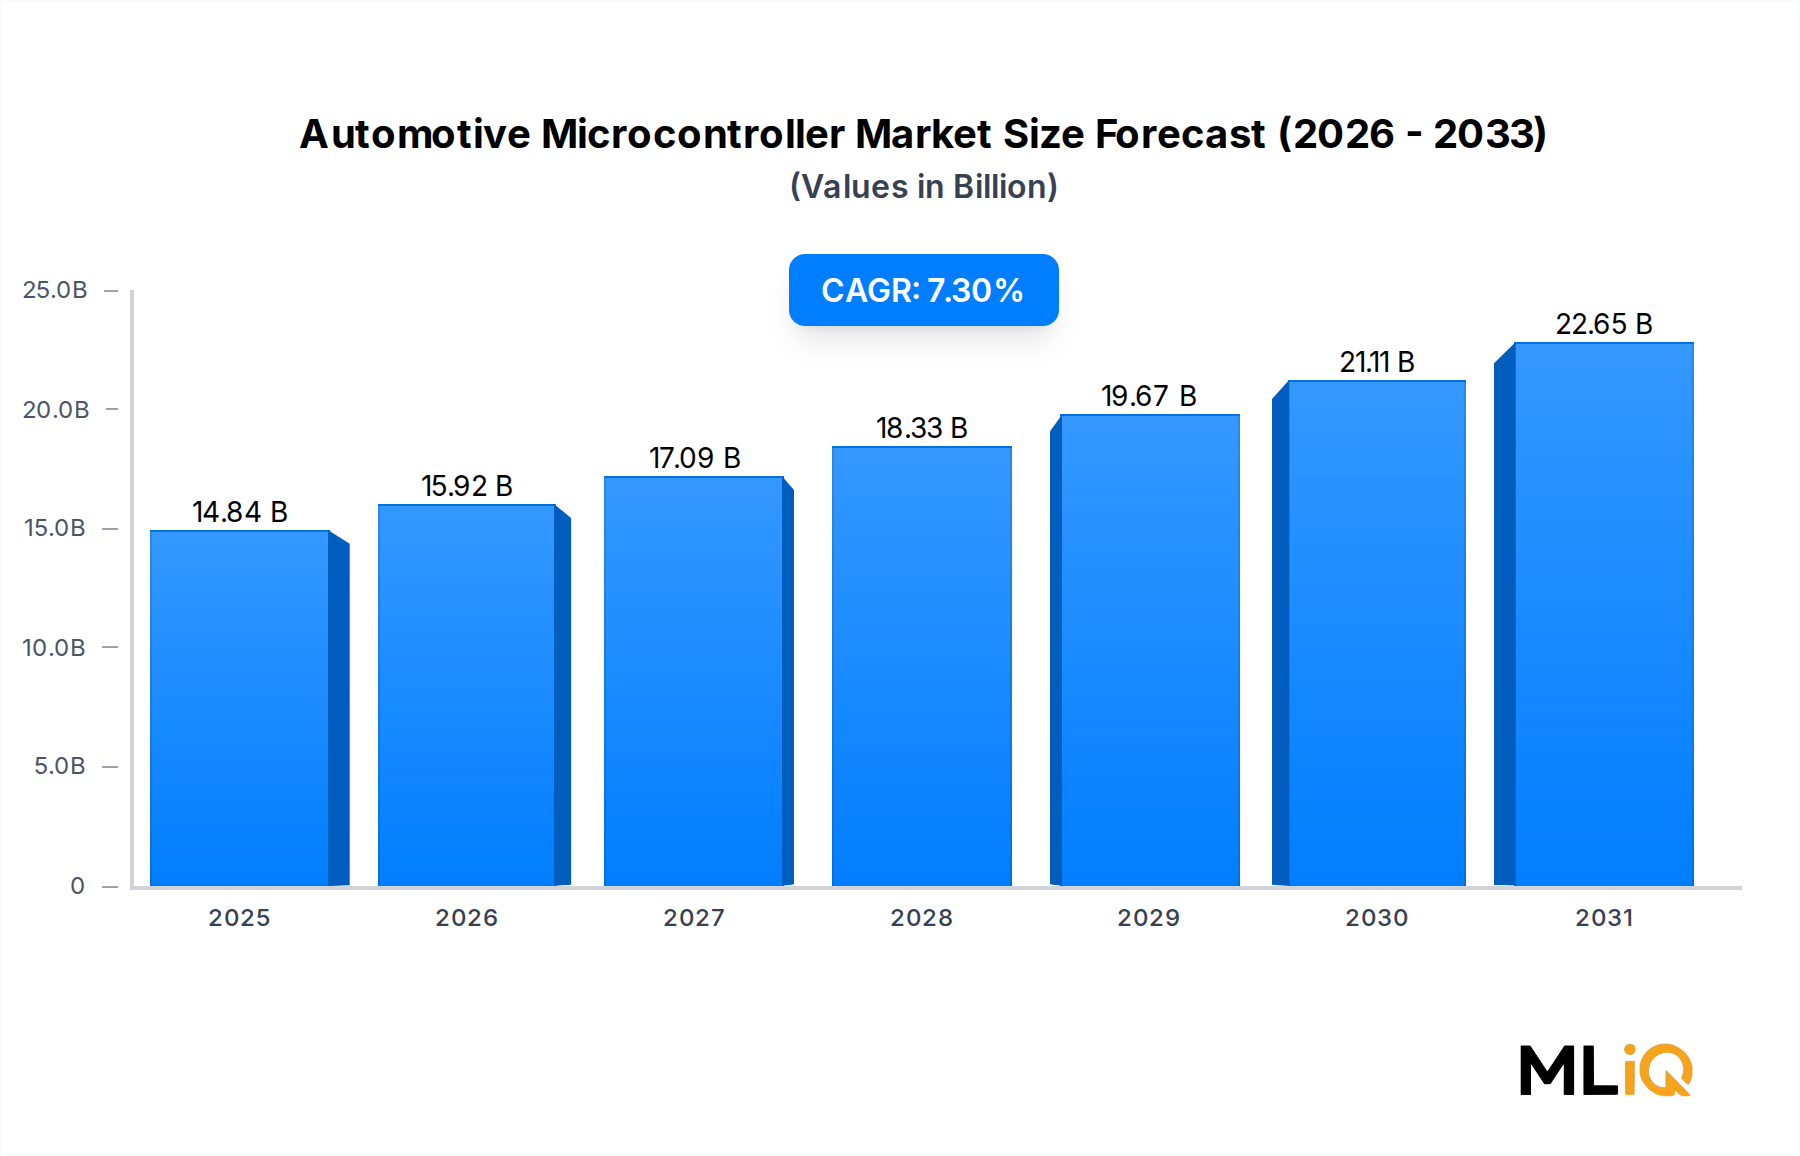
The global Automotive Microcontroller Market was valued at $14.84 billion in the base year and is projected to expand at a compound annual growth rate of 7.3% through 2025–2033, reflecting robust structural demand across all major vehicle architectures. This momentum is being driven by an unprecedented convergence of electrification, advanced safety mandates, and the rising computational complexity embedded in modern vehicles.
Automotive microcontrollers (MCUs) serve as the central nervous system of a vehicle's electronic architecture, orchestrating functions that span powertrain management, chassis control, safety systems, body electronics, telematics, and infotainment. As vehicles transition from mechanical to software-defined platforms, the average MCU content per vehicle is rising sharply, with electric vehicles (EVs) consuming up to three to five times more semiconductor content than comparable internal combustion engine (ICE) vehicles.
Macro tailwinds reinforcing this trajectory include aggressive government electrification targets across the European Union, the United States, China, South Korea, and Japan; tightening functional safety standards such as ISO 26262 and AUTOSAR compliance requirements; and growing consumer expectations for connected, over-the-air (OTA) updatable vehicles. These factors are compelling OEMs and Tier-1 suppliers to source higher-performance, multi-core MCUs capable of real-time processing across safety-critical and non-safety-critical domains simultaneously.
The Automotive Semiconductor Market, of which automotive MCUs form a critical sub-segment, is experiencing elevated capital expenditure from leading chip foundries and IDMs seeking to reduce geopolitical supply chain vulnerabilities exposed during the 2020–2022 chip shortage. This strategic re-shoring and diversification effort is creating new supply corridors in North America, Europe, and Southeast Asia, providing medium-term supply stability for automotive-grade MCUs.
From a demand perspective, the Electric Vehicle Electronics Market is emerging as the fastest-growing end-use segment, with EV-specific MCU applications spanning battery management systems, inverter control, thermal management, and regenerative braking. Meanwhile, safety and security applications—particularly those aligned with the Advanced Driver Assistance Systems Market—are pulling demand for high-integrity, ASIL-D rated microcontrollers at an accelerating pace.
Looking forward through 2033, the market outlook remains constructive. The integration of MCUs with AI-capable edge inference engines, the proliferation of zonal and domain-centralized electrical architectures, and the growing role of software-defined vehicles (SDVs) are expected to sustain above-market growth rates. Vendors with comprehensive safety certification portfolios, multi-die packaging capabilities, and strong ecosystem partnerships with OEMs and Tier-1 integrators are best positioned to capture disproportionate share of this expanding opportunity.