Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Medical Injection Molding Machines: 2033 Growth & Trends
Medical Injection Molding Machines Market
Medical Injection Molding Machines: 2033 Growth & Trends
Medical Injection Molding Machines Market by Material (Polypropylene, Polyethylene, Thermoplastic Elastomer, Cyclic Olefin Copolymer, Acrylonitrile Butadiene Styrene, Others), by Application (Surgery, Pharma, Diagnostics Medical Equipment, Healthcare, Cosmetics), by Machine Type (Standard Injection Molding Machine, Multi-component Injection Molding Machine, LSR Injection Molding Machine), by Mode of Operation (All-electric, Hybrid, Hydraulic), by Clamping Force (Less than 200 Tons Force, 200 to 500 Tons Force, More than 500 Tons Force), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Jul 31, 2026|Base Year : 2025|Pages : 461
Key Insights & Executive Summary: Medical Injection Molding Machines Market
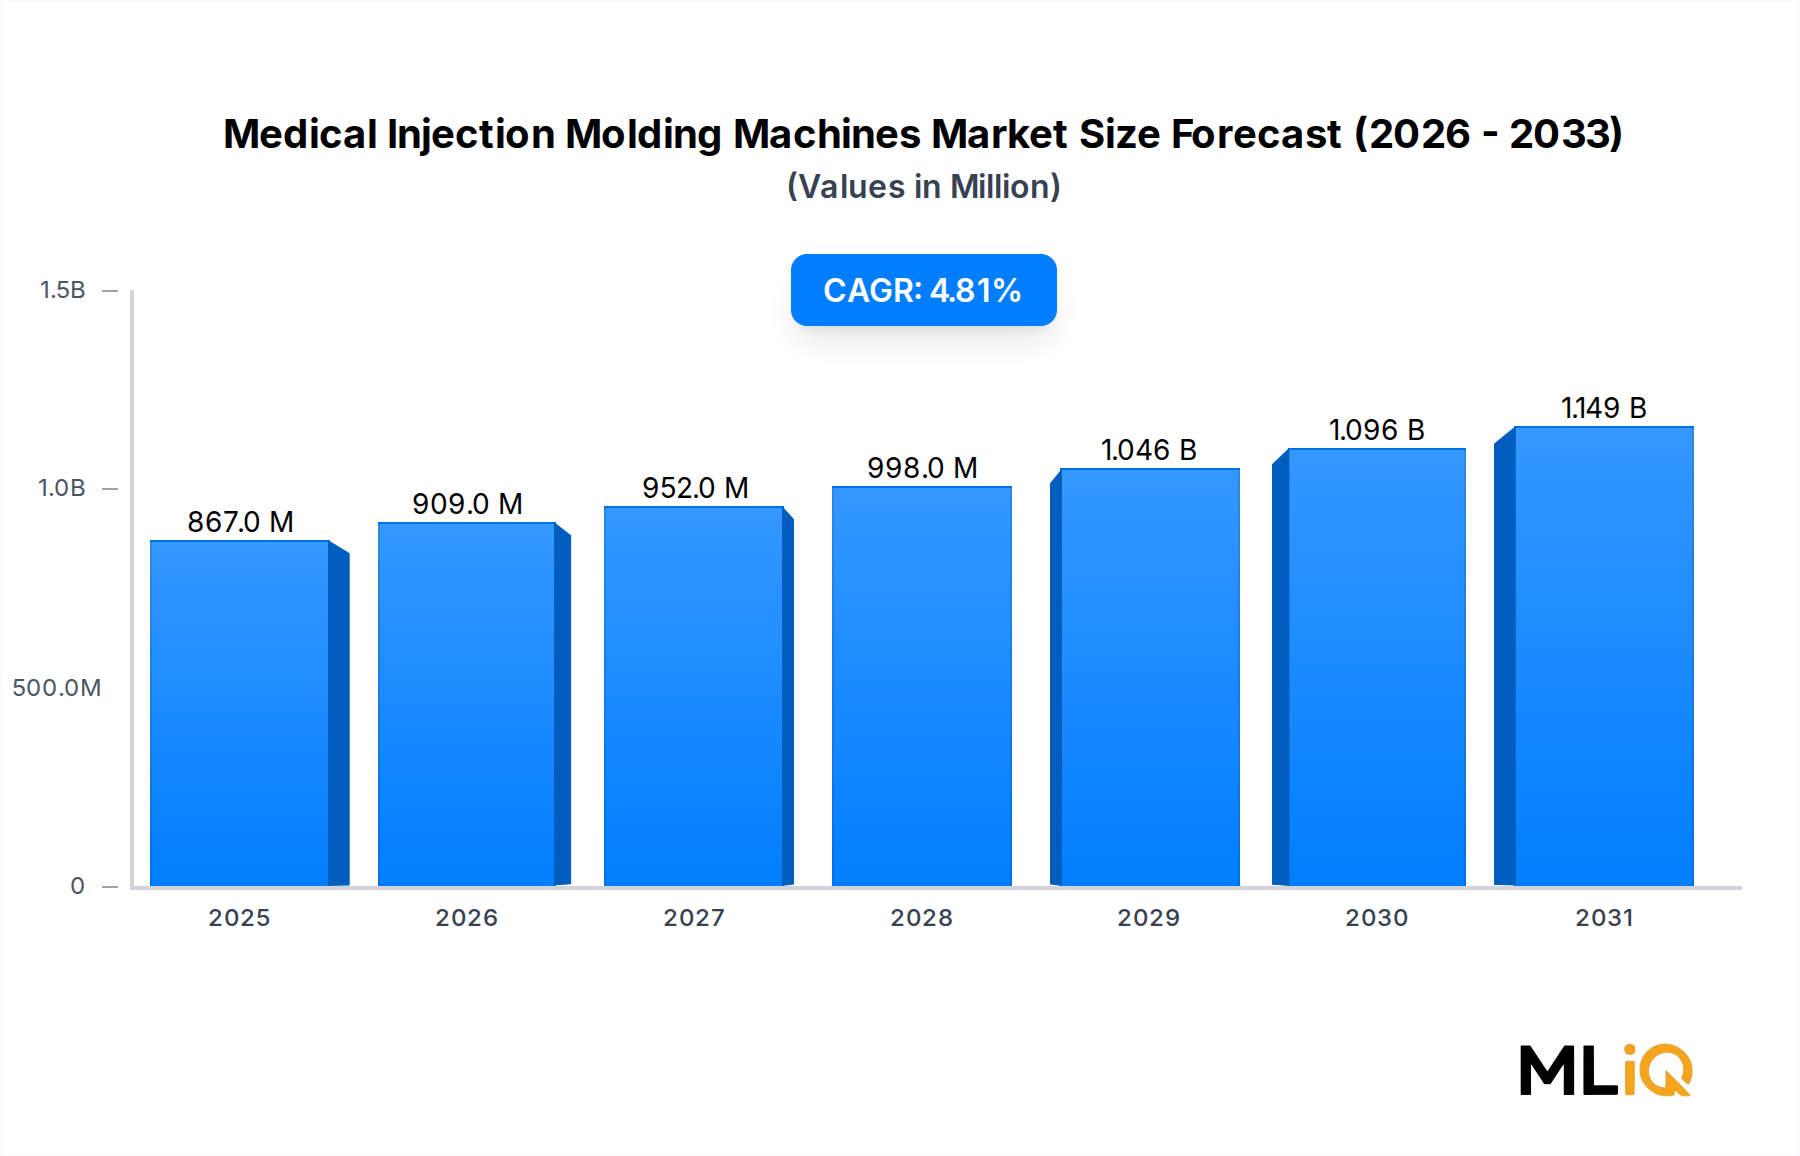
Medical Injection Molding Machines Market Size (In Million)
1.5B
1.0B
500.0M
0
867.0 M
2025
909.0 M
2026
952.0 M
2027
998.0 M
2028
1.046 B
2029
1.096 B
2030
1.149 B
2031
Market at a Glance
The global Medical Injection Molding Machines Market is poised for sustained expansion, anchored at a base valuation of USD 867.10 million and advancing at a CAGR of 4.8% through the forecast horizon. This trajectory reflects deep structural demand shifts across global healthcare infrastructure, precision plastics production, and advanced polymer processing technologies applied to clinical and diagnostic device manufacturing.
At its core, market momentum is being shaped by four converging macro forces. First, the accelerating global burden of chronic disease is driving unprecedented volumes of disposable medical devices, syringes, IV components, diagnostic cartridges, and drug delivery systems—all of which require high-precision injection molding processes. Second, international regulatory bodies including the U.S. FDA, EU MDR, and PMDA in Japan are reinforcing stringent quality and traceability requirements on medical-grade polymer components, compelling device OEMs to invest in validated, cleanroom-compatible molding platforms. Third, the increasing adoption of high-performance engineering polymers such as Cyclic Olefin Copolymer and Thermoplastic Elastomer in pharmaceutical and surgical applications is pushing demand toward specialized multi-component and LSR injection systems. Fourth, the ongoing transition from hydraulic to all-electric and hybrid machine architectures is reconfiguring capital expenditure decisions across large-scale medical molding facilities, particularly in North America, Western Europe, and East Asia.
Strategically, the market is undergoing a shift toward fully integrated manufacturing cells that incorporate robotics, vision systems, cleanroom compliance, and real-time process data—converging with the broader Industrial Automation Equipment Market. Leading vendors including ENGEL AUSTRIA, ARBURG, Sumitomo, and Husky are aggressively positioning their medical-segment platforms as end-to-end solutions rather than standalone capital equipment. The competitive landscape is moderately consolidated at the premium tier but fragmented in the mid-range Asian machine segment, primarily driven by Chinese OEMs expanding their medical-grade machine portfolios.
From an application standpoint, surgical and pharmaceutical end-uses represent the highest-value segments, while diagnostics and healthcare device production are the fastest-growing verticals. The shift toward single-use, sterile-packaged medical components—accelerated by post-pandemic infection control protocols—continues to underpin robust volume demand. These dynamics collectively position the medical injection molding sector as one of the most technically differentiated and defensible sub-segments within the broader Plastic Injection Molding Machine Market.
Segment Deep-Dive: All-Electric Dominance in Medical Injection Molding Machines Market
Why All-Electric Machines Lead the Medical Segment
The all-electric mode of operation represents the dominant and fastest-growing sub-segment within the medical injection molding space, commanding a disproportionately high share of new capital investment relative to its installed base. This dominance is not incidental—it reflects a convergence of clinical precision requirements, regulatory compliance imperatives, and total cost of ownership (TCO) economics that collectively favor servo-motor-driven electric architectures over legacy hydraulic systems.
All-electric machines eliminate hydraulic fluid entirely from the production environment, a critical advantage in ISO Class 7 and Class 8 cleanrooms where any contamination risk is disqualifying. The Medical Device Manufacturing Market's stringent particulate and chemical contamination standards, particularly under ISO 13485 and FDA 21 CFR Part 820, create a near-mandatory compliance pathway toward all-electric platforms for components intended for implantable, inhalation, or injectable drug delivery applications.
Precision & Repeatability Advantages
All-electric machines achieve shot-to-shot repeatability tolerances below ±0.1% in injection velocity and pressure profiles, critical for thin-wall micro-molding applications such as insulin pen components, ophthalmic lenses, and diagnostic microfluidic chips. The servo-driven closed-loop control systems enable process data logging at millisecond resolution, directly supporting 21 CFR Part 11-compliant electronic batch records—a capability increasingly demanded by pharmaceutical packaging customers operating under GMP conditions.
The energy efficiency of all-electric platforms is typically 50–70% more efficient than comparable hydraulic systems, a factor that has elevated their appeal as energy costs have risen across European and North American manufacturing facilities. Over a standard 7–10 year asset lifecycle, the electricity savings alone can offset a 15–25% machine price premium over hydraulic equivalents.
Sub-Segment Dynamics: Hybrid Machines as Bridge Technology
The hybrid sub-segment—combining electric servo injection with hydraulic clamping—retains strategic relevance in the 200–500 ton clamping force category, where the economics of full electrification at high tonnage are less favorable. Hybrid machines serve as a practical bridge technology for molders transitioning from hydraulic fleets, allowing partial cleanroom compliance while managing capital outlay. However, as all-electric systems from ENGEL, ARBURG, and Sumitomo scale into the 500+ ton range at progressively lower price points, hybrid penetration is expected to plateau over the medium term.
Hydraulic Segment Decline
Hydraulic injection molding machines, while still prevalent in price-sensitive Asian markets and heavy-tonnage applications, are facing structural share erosion in medical-grade production. Regulatory audits increasingly flag hydraulic systems as contamination risks, and the growing footprint of the All-Electric Injection Molding Machine Market is diminishing the addressable opportunity for hydraulic-only platforms in the medical space. Remaining hydraulic demand in medical molding is concentrated in developing markets in Southeast Asia and South America, where upfront CapEx constraints still outweigh long-term efficiency arguments.
Clamping Force Distribution
Within the all-electric segment, the 200 to 500 tons force bracket is the highest-revenue tier, covering the broadest application range from mid-complexity surgical trays to multi-cavity diagnostic cartridge tools. The less than 200 tons bracket is the fastest growing, driven by micro-molding demand in wearable drug delivery devices and point-of-care diagnostics. Machines exceeding 500 tons are niche in medical applications but see demand in large-volume packaging for pharmaceutical distribution.
Primary Market Drivers & Growth Restraints in Medical Injection Molding Machines Market
Key Demand Catalysts
Aging Global Demographics and Chronic Disease Prevalence: The WHO estimates that by 2030, 1 in 6 individuals globally will be over age 60. This demographic shift directly correlates with elevated demand for minimally invasive surgical instruments, orthopedic implant tooling, diagnostic consumables, and pharmaceutical delivery devices—all intensive users of precision injection-molded polymer components.
Regulatory Push Toward Single-Use Medical Devices: The European MDR (EU 2017/745) and FDA's Quality System Regulation reforms are accelerating the transition from reusable to single-use devices across surgical, endoscopy, and ICU applications. Single-use devices are almost exclusively injection-molded, directly translating regulatory compliance pressure into sustained machine demand.
Advanced Polymer Adoption: Growing adoption of specialty resins including Cyclic Olefin Copolymer—valued for its optical clarity and low extractables in pharmaceutical and diagnostics applications—and Thermoplastic Elastomer in surgical grips and catheter overmolds is compelling OEMs to invest in specialized molding platforms. These materials require tightly controlled melt temperature and injection pressure profiles that only high-end electric machines can consistently deliver.
Nearshoring of Medical Supply Chains: Post-COVID supply chain disruptions accelerated reshoring and nearshoring of medical component manufacturing in North America and Europe, directly stimulating capital investment in domestic injection molding capacity.
Operational Restraints
High Capital and Validation Costs: A fully equipped medical-grade all-electric injection molding cell—including cleanroom integration, robotics, and process qualification—can require USD 500,000 to USD 2+ million in capital outlay. The IQ/OQ/PQ validation process per medical application adds USD 50,000–200,000 and 6–18 months of lead time, creating significant barriers for small and mid-tier molders.
Resin Supply Volatility: The medical molding value chain is exposed to upstream volatility in the Pharmaceutical Packaging Market's resin supply, particularly for specialty polymers. Polypropylene and Polyethylene pricing swings of 15–30% year-over-year directly compress molder margins on fixed-price OEM contracts.
Skilled Technician Shortage: The global shortage of process engineers trained in medical-grade molding validation, particularly in North America and Europe, constrains capacity utilization rates and delays new program launches.
The competitive landscape is characterized by a premium tier of European and Japanese OEMs commanding the highest ASPs and technical differentiation, challenged by expanding Chinese machine builders targeting mid-market medical applications.
ENGEL AUSTRIA GmbH: Austria-based ENGEL is widely regarded as the global technology leader in medical injection molding, with its e-victory and e-mac all-electric platforms specifically engineered for cleanroom deployment. ENGEL's integrated automation and Industry 4.0 iQ process control systems are standard references in pharmaceutical packaging and surgical device production.
ARBURG GmbH: ARBURG's Allrounder electric series commands premium positioning in micro-molding and multi-component medical applications. The company's Freeformer additive system complements its injection molding portfolio, enabling integrated production workflows for complex medical device geometries.
Husky Injection Molding Systems Ltd: Husky holds a dominant position in high-cavitation PET and polypropylene systems for pharmaceutical closures and prefilled syringe components, with its HyCAP and Altanium platform widely deployed in sterile packaging lines globally.
Sumitomo Heavy Industries, Ltd.: Sumitomo's SE-EV all-electric platform is a preferred platform for Japanese and South Korean medical device OEMs, with particular strength in micro-precision and thin-wall medical molding applications requiring sub-micron repeatability.
CHINA NATIONAL CHEMICAL CORPORATION LTD. (KRAUSSMAFFEI GROUP GmbH): KraussMaffei, now under ChemChina's umbrella, brings European engineering heritage with expanding manufacturing scale for medical-grade machines. Its PX all-electric and CX hybrid series are gaining traction in European medical device clusters.
HILLENBRAND INC. (MILACRON HOLDINGS CORP.): Milacron's Roboshot all-electric series, distributed through Hillenbrand's industrial platform, targets North American medical molders seeking domestic technical support and validated process solutions.
BOLE Machinery: BOLE represents China's rising challenge in the mid-market medical molding segment, offering electric and hybrid platforms at price points 20–35% below European equivalents, targeting Southeast Asian and domestic Chinese medical device manufacturers.
Haitian International Holding Limited: Haitian's Venus electric series is among the highest-volume all-electric medical molding platforms produced globally, with strong penetration in China's rapidly expanding domestic medical device sector and growing export presence.
Shibaura Machine Co. Ltd.: Formerly known as Toshiba Machine, Shibaura maintains a respected position in high-precision electric injection systems for Japanese medical OEMs, with particular expertise in semiconductor and optical-grade polymer components overlapping with medical diagnostics applications.
The Japan Steel Works, Ltd. (JSW): JSW's J-ADS all-electric series is a technically specialized platform for ultra-high-precision medical micro-molding, widely used in Japanese implantable device and ophthalmic lens production.
Strategic Milestones & Recent Developments in Medical Injection Molding Machines Market
The following chronological milestones capture pivotal commercial, technological, and regulatory developments shaping competitive positioning:
Q1 2023: ENGEL AUSTRIA launched its new e-mac 310 cleanroom-ready all-electric injection molding system at Medtec Europe, featuring integrated iQ weight control and direct compatibility with ISO Class 8 cleanroom enclosures, targeting disposable medical device manufacturers across the EU.
Q2 2023: Husky Injection Molding Systems Ltd completed the strategic acquisition of Schöttli Group, a Swiss precision medical mold manufacturer, significantly vertically integrating Husky's medical offering from machine platforms into precision tooling for pharmaceutical closures and prefilled syringes.
Q3 2023: KraussMaffei Group (under CNCC ownership) announced a capacity expansion at its Munich medical systems production facility, adding 15,000 sqm of dedicated cleanroom machine assembly space to meet rising European demand for all-electric medical molding cells.
Q4 2023: Sumitomo Heavy Industries unveiled the next-generation SE-EV II all-electric series at Fakuma 2023, incorporating real-time AI-based melt viscosity compensation technology, reducing setup scrap rates by an estimated 40% in medical thin-wall applications.
Q1 2024: Haitian International announced the commercial launch of its Venus III E medical-series all-electric machines targeting ISO 13485-certified facilities, with direct export programs established for India and Southeast Asian emerging medical manufacturing hubs.
Q2 2024: ARBURG GmbH expanded its partnership with Stäubli Robotics to offer fully integrated, pre-validated medical automation cells based on the Allrounder electric platform, reducing customer validation timelines by approximately 30% for Class II medical device applications.
Q3 2024: Hillenbrand Inc. (Milacron) reported a 12% year-over-year increase in medical segment machine orders, attributing growth primarily to reshoring-driven capital investment by North American pharmaceutical packaging and surgical device manufacturers.
Regional Market Analysis & Growth Corridors for Medical Injection Molding Machines Market
Asia Pacific – Largest and Fastest-Growing Regional Market
Asia Pacific holds the largest regional share of the global market, driven by China's massive domestic medical device manufacturing base, Japan's precision engineering capabilities, and rapidly scaling production ecosystems in India, South Korea, and ASEAN nations. China alone accounts for an estimated 35–38% of global medical injection molding machine demand by volume, with domestic OEMs including Haitian and BOLE capturing growing share from European suppliers in the mid-tier segment. India's medical device manufacturing push under the Production Linked Incentive (PLI) scheme is generating greenfield injection molding investments, positioning it as the fastest-growing single national market within the region at an estimated CAGR exceeding 7% through 2030.
North America – Premium Segment Leader
North America represents the highest per-unit ASP market globally, with medical molders in the U.S. and Canada disproportionately investing in all-electric, cleanroom-integrated platforms driven by FDA regulatory stringency and the reshoring of critical medical supply chains. The U.S. market benefits from dense clusters of Class II and Class III medical device OEMs in Minnesota, Massachusetts, and California, all requiring validated injection molding partners. The Precision Plastics Manufacturing Market in North America is expanding at approximately 5.2% CAGR, directly pulling demand for advanced electric molding systems.
Europe – Mature but Technically Sophisticated
Europe is the most technically mature regional market, dominated by German, Austrian, Swiss, and Irish medical device manufacturing clusters. EU MDR compliance requirements have accelerated equipment refresh cycles, as legacy hydraulic machines are increasingly incompatible with updated cleanroom and traceability requirements. Germany, Ireland, and Switzerland collectively represent over 60% of European medical injection molding machine demand. The Pharmaceutical Packaging Market's strength in Western Europe is a consistent demand anchor for high-cavitation medical molding platforms.
Middle East & Africa and South America – Emerging Corridors
LAMEA markets remain nascent but are attracting greenfield investment in healthcare infrastructure across GCC nations, South Africa, Brazil, and Mexico. Brazil's domestic medical device industry, supported by ANVISA regulatory harmonization with international standards, is the most developed in South America. GCC nations' Vision 2030 and similar sovereign investment programs are funding new hospital and medical manufacturing infrastructure, creating early-stage but structurally significant demand for medical-grade injection molding capacity in the medium term.
Investment, M&A & Funding Activity in Medical Injection Molding Machines Market
The 2022–2025 period has been characterized by elevated M&A activity and strategic capital deployment across the medical injection molding value chain, reflecting investor confidence in the sector's structural growth fundamentals and the premium valuations commanded by medical-certified manufacturing assets.
Husky's acquisition of Schöttli Group (
Medical Injection Molding Machines Market Segmentation
1. Material
1.1. Polypropylene
1.2. Polyethylene
1.3. Thermoplastic Elastomer
1.4. Cyclic Olefin Copolymer
1.5. Acrylonitrile Butadiene Styrene
1.6. Others
2. Application
2.1. Surgery
2.2. Pharma
2.3. Diagnostics Medical Equipment
2.4. Healthcare
2.5. Cosmetics
3. Machine Type
3.1. Standard Injection Molding Machine
3.2. Multi-component Injection Molding Machine
3.3. LSR Injection Molding Machine
4. Mode of Operation
4.1. All-electric
4.2. Hybrid
4.3. Hydraulic
5. Clamping Force
5.1. Less than 200 Tons Force
5.2. 200 to 500 Tons Force
5.3. More than 500 Tons Force
Medical Injection Molding Machines Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Medical Injection Molding Machines Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 4.8% from 2020-2034
Segmentation
By Material
Polypropylene
Polyethylene
Thermoplastic Elastomer
Cyclic Olefin Copolymer
Acrylonitrile Butadiene Styrene
Others
By Application
Surgery
Pharma
Diagnostics Medical Equipment
Healthcare
Cosmetics
By Machine Type
Standard Injection Molding Machine
Multi-component Injection Molding Machine
LSR Injection Molding Machine
By Mode of Operation
All-electric
Hybrid
Hydraulic
By Clamping Force
Less than 200 Tons Force
200 to 500 Tons Force
More than 500 Tons Force
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Material
5.1.1. Polypropylene
5.1.2. Polyethylene
5.1.3. Thermoplastic Elastomer
5.1.4. Cyclic Olefin Copolymer
5.1.5. Acrylonitrile Butadiene Styrene
5.1.6. Others
5.2. Market Analysis, Insights and Forecast - by Application
5.2.1. Surgery
5.2.2. Pharma
5.2.3. Diagnostics Medical Equipment
5.2.4. Healthcare
5.2.5. Cosmetics
5.3. Market Analysis, Insights and Forecast - by Machine Type
5.3.1. Standard Injection Molding Machine
5.3.2. Multi-component Injection Molding Machine
5.3.3. LSR Injection Molding Machine
5.4. Market Analysis, Insights and Forecast - by Mode of Operation
5.4.1. All-electric
5.4.2. Hybrid
5.4.3. Hydraulic
5.5. Market Analysis, Insights and Forecast - by Clamping Force
5.5.1. Less than 200 Tons Force
5.5.2. 200 to 500 Tons Force
5.5.3. More than 500 Tons Force
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. South America
5.6.3. Europe
5.6.4. Middle East & Africa
5.6.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Material
6.1.1. Polypropylene
6.1.2. Polyethylene
6.1.3. Thermoplastic Elastomer
6.1.4. Cyclic Olefin Copolymer
6.1.5. Acrylonitrile Butadiene Styrene
6.1.6. Others
6.2. Market Analysis, Insights and Forecast - by Application
6.2.1. Surgery
6.2.2. Pharma
6.2.3. Diagnostics Medical Equipment
6.2.4. Healthcare
6.2.5. Cosmetics
6.3. Market Analysis, Insights and Forecast - by Machine Type
6.3.1. Standard Injection Molding Machine
6.3.2. Multi-component Injection Molding Machine
6.3.3. LSR Injection Molding Machine
6.4. Market Analysis, Insights and Forecast - by Mode of Operation
6.4.1. All-electric
6.4.2. Hybrid
6.4.3. Hydraulic
6.5. Market Analysis, Insights and Forecast - by Clamping Force
6.5.1. Less than 200 Tons Force
6.5.2. 200 to 500 Tons Force
6.5.3. More than 500 Tons Force
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Material
7.1.1. Polypropylene
7.1.2. Polyethylene
7.1.3. Thermoplastic Elastomer
7.1.4. Cyclic Olefin Copolymer
7.1.5. Acrylonitrile Butadiene Styrene
7.1.6. Others
7.2. Market Analysis, Insights and Forecast - by Application
7.2.1. Surgery
7.2.2. Pharma
7.2.3. Diagnostics Medical Equipment
7.2.4. Healthcare
7.2.5. Cosmetics
7.3. Market Analysis, Insights and Forecast - by Machine Type
7.3.1. Standard Injection Molding Machine
7.3.2. Multi-component Injection Molding Machine
7.3.3. LSR Injection Molding Machine
7.4. Market Analysis, Insights and Forecast - by Mode of Operation
7.4.1. All-electric
7.4.2. Hybrid
7.4.3. Hydraulic
7.5. Market Analysis, Insights and Forecast - by Clamping Force
7.5.1. Less than 200 Tons Force
7.5.2. 200 to 500 Tons Force
7.5.3. More than 500 Tons Force
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Material
8.1.1. Polypropylene
8.1.2. Polyethylene
8.1.3. Thermoplastic Elastomer
8.1.4. Cyclic Olefin Copolymer
8.1.5. Acrylonitrile Butadiene Styrene
8.1.6. Others
8.2. Market Analysis, Insights and Forecast - by Application
8.2.1. Surgery
8.2.2. Pharma
8.2.3. Diagnostics Medical Equipment
8.2.4. Healthcare
8.2.5. Cosmetics
8.3. Market Analysis, Insights and Forecast - by Machine Type
8.3.1. Standard Injection Molding Machine
8.3.2. Multi-component Injection Molding Machine
8.3.3. LSR Injection Molding Machine
8.4. Market Analysis, Insights and Forecast - by Mode of Operation
8.4.1. All-electric
8.4.2. Hybrid
8.4.3. Hydraulic
8.5. Market Analysis, Insights and Forecast - by Clamping Force
8.5.1. Less than 200 Tons Force
8.5.2. 200 to 500 Tons Force
8.5.3. More than 500 Tons Force
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Material
9.1.1. Polypropylene
9.1.2. Polyethylene
9.1.3. Thermoplastic Elastomer
9.1.4. Cyclic Olefin Copolymer
9.1.5. Acrylonitrile Butadiene Styrene
9.1.6. Others
9.2. Market Analysis, Insights and Forecast - by Application
9.2.1. Surgery
9.2.2. Pharma
9.2.3. Diagnostics Medical Equipment
9.2.4. Healthcare
9.2.5. Cosmetics
9.3. Market Analysis, Insights and Forecast - by Machine Type
9.3.1. Standard Injection Molding Machine
9.3.2. Multi-component Injection Molding Machine
9.3.3. LSR Injection Molding Machine
9.4. Market Analysis, Insights and Forecast - by Mode of Operation
9.4.1. All-electric
9.4.2. Hybrid
9.4.3. Hydraulic
9.5. Market Analysis, Insights and Forecast - by Clamping Force
9.5.1. Less than 200 Tons Force
9.5.2. 200 to 500 Tons Force
9.5.3. More than 500 Tons Force
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Material
10.1.1. Polypropylene
10.1.2. Polyethylene
10.1.3. Thermoplastic Elastomer
10.1.4. Cyclic Olefin Copolymer
10.1.5. Acrylonitrile Butadiene Styrene
10.1.6. Others
10.2. Market Analysis, Insights and Forecast - by Application
10.2.1. Surgery
10.2.2. Pharma
10.2.3. Diagnostics Medical Equipment
10.2.4. Healthcare
10.2.5. Cosmetics
10.3. Market Analysis, Insights and Forecast - by Machine Type
10.3.1. Standard Injection Molding Machine
10.3.2. Multi-component Injection Molding Machine
10.3.3. LSR Injection Molding Machine
10.4. Market Analysis, Insights and Forecast - by Mode of Operation
10.4.1. All-electric
10.4.2. Hybrid
10.4.3. Hydraulic
10.5. Market Analysis, Insights and Forecast - by Clamping Force
10.5.1. Less than 200 Tons Force
10.5.2. 200 to 500 Tons Force
10.5.3. More than 500 Tons Force
11. Competitive Analysis
11.1. Company Profiles
11.1.1. ARBURG GmbH
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Haitian International Holding Limited
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Sumitomo Heavy Industries
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Ltd.
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. CHINA NATIONAL CHEMICAL CORPORATION LTD. (KRAUSSMAFFEI GROUP GmbH)
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. HILLENBRAND INC. (MILACRON HOLDINGS CORP.)
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. BOLE Machinery
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Husky Injection Molding Systems Ltd
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. ENGEL AUSTRIA GmbH
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Shibaura Machine Co. Ltd.
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. The Japan Steel Works
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. Ltd.(JSW)
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Medical Injection Molding Machines Market Revenue Breakdown (million, %) by Region 2026 & 2034
Figure 2: North America Medical Injection Molding Machines Market Revenue (million), by Material 2026 & 2034
Figure 3: North America Medical Injection Molding Machines Market Revenue Share (%), by Material 2026 & 2034
Figure 4: North America Medical Injection Molding Machines Market Revenue (million), by Application 2026 & 2034
Figure 5: North America Medical Injection Molding Machines Market Revenue Share (%), by Application 2026 & 2034
Figure 6: North America Medical Injection Molding Machines Market Revenue (million), by Machine Type 2026 & 2034
Figure 7: North America Medical Injection Molding Machines Market Revenue Share (%), by Machine Type 2026 & 2034
Figure 8: North America Medical Injection Molding Machines Market Revenue (million), by Mode of Operation 2026 & 2034
Figure 9: North America Medical Injection Molding Machines Market Revenue Share (%), by Mode of Operation 2026 & 2034
Figure 10: North America Medical Injection Molding Machines Market Revenue (million), by Clamping Force 2026 & 2034
Figure 11: North America Medical Injection Molding Machines Market Revenue Share (%), by Clamping Force 2026 & 2034
Figure 12: North America Medical Injection Molding Machines Market Revenue (million), by Country 2026 & 2034
Figure 13: North America Medical Injection Molding Machines Market Revenue Share (%), by Country 2026 & 2034
Figure 14: South America Medical Injection Molding Machines Market Revenue (million), by Material 2026 & 2034
Figure 15: South America Medical Injection Molding Machines Market Revenue Share (%), by Material 2026 & 2034
Figure 16: South America Medical Injection Molding Machines Market Revenue (million), by Application 2026 & 2034
Figure 17: South America Medical Injection Molding Machines Market Revenue Share (%), by Application 2026 & 2034
Figure 18: South America Medical Injection Molding Machines Market Revenue (million), by Machine Type 2026 & 2034
Figure 19: South America Medical Injection Molding Machines Market Revenue Share (%), by Machine Type 2026 & 2034
Figure 20: South America Medical Injection Molding Machines Market Revenue (million), by Mode of Operation 2026 & 2034
Figure 21: South America Medical Injection Molding Machines Market Revenue Share (%), by Mode of Operation 2026 & 2034
Figure 22: South America Medical Injection Molding Machines Market Revenue (million), by Clamping Force 2026 & 2034
Figure 23: South America Medical Injection Molding Machines Market Revenue Share (%), by Clamping Force 2026 & 2034
Figure 24: South America Medical Injection Molding Machines Market Revenue (million), by Country 2026 & 2034
Figure 25: South America Medical Injection Molding Machines Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Europe Medical Injection Molding Machines Market Revenue (million), by Material 2026 & 2034
Figure 27: Europe Medical Injection Molding Machines Market Revenue Share (%), by Material 2026 & 2034
Figure 28: Europe Medical Injection Molding Machines Market Revenue (million), by Application 2026 & 2034
Figure 29: Europe Medical Injection Molding Machines Market Revenue Share (%), by Application 2026 & 2034
Figure 30: Europe Medical Injection Molding Machines Market Revenue (million), by Machine Type 2026 & 2034
Figure 31: Europe Medical Injection Molding Machines Market Revenue Share (%), by Machine Type 2026 & 2034
Figure 32: Europe Medical Injection Molding Machines Market Revenue (million), by Mode of Operation 2026 & 2034
Figure 33: Europe Medical Injection Molding Machines Market Revenue Share (%), by Mode of Operation 2026 & 2034
Figure 34: Europe Medical Injection Molding Machines Market Revenue (million), by Clamping Force 2026 & 2034
Figure 35: Europe Medical Injection Molding Machines Market Revenue Share (%), by Clamping Force 2026 & 2034
Figure 36: Europe Medical Injection Molding Machines Market Revenue (million), by Country 2026 & 2034
Figure 37: Europe Medical Injection Molding Machines Market Revenue Share (%), by Country 2026 & 2034
Figure 38: Middle East & Africa Medical Injection Molding Machines Market Revenue (million), by Material 2026 & 2034
Figure 39: Middle East & Africa Medical Injection Molding Machines Market Revenue Share (%), by Material 2026 & 2034
Figure 40: Middle East & Africa Medical Injection Molding Machines Market Revenue (million), by Application 2026 & 2034
Figure 41: Middle East & Africa Medical Injection Molding Machines Market Revenue Share (%), by Application 2026 & 2034
Figure 42: Middle East & Africa Medical Injection Molding Machines Market Revenue (million), by Machine Type 2026 & 2034
Figure 43: Middle East & Africa Medical Injection Molding Machines Market Revenue Share (%), by Machine Type 2026 & 2034
Figure 44: Middle East & Africa Medical Injection Molding Machines Market Revenue (million), by Mode of Operation 2026 & 2034
Figure 45: Middle East & Africa Medical Injection Molding Machines Market Revenue Share (%), by Mode of Operation 2026 & 2034
Figure 46: Middle East & Africa Medical Injection Molding Machines Market Revenue (million), by Clamping Force 2026 & 2034
Figure 47: Middle East & Africa Medical Injection Molding Machines Market Revenue Share (%), by Clamping Force 2026 & 2034
Figure 48: Middle East & Africa Medical Injection Molding Machines Market Revenue (million), by Country 2026 & 2034
Figure 49: Middle East & Africa Medical Injection Molding Machines Market Revenue Share (%), by Country 2026 & 2034
Figure 50: Asia Pacific Medical Injection Molding Machines Market Revenue (million), by Material 2026 & 2034
Figure 51: Asia Pacific Medical Injection Molding Machines Market Revenue Share (%), by Material 2026 & 2034
Figure 52: Asia Pacific Medical Injection Molding Machines Market Revenue (million), by Application 2026 & 2034
Figure 53: Asia Pacific Medical Injection Molding Machines Market Revenue Share (%), by Application 2026 & 2034
Figure 54: Asia Pacific Medical Injection Molding Machines Market Revenue (million), by Machine Type 2026 & 2034
Figure 55: Asia Pacific Medical Injection Molding Machines Market Revenue Share (%), by Machine Type 2026 & 2034
Figure 56: Asia Pacific Medical Injection Molding Machines Market Revenue (million), by Mode of Operation 2026 & 2034
Figure 57: Asia Pacific Medical Injection Molding Machines Market Revenue Share (%), by Mode of Operation 2026 & 2034
Figure 58: Asia Pacific Medical Injection Molding Machines Market Revenue (million), by Clamping Force 2026 & 2034
Figure 59: Asia Pacific Medical Injection Molding Machines Market Revenue Share (%), by Clamping Force 2026 & 2034
Figure 60: Asia Pacific Medical Injection Molding Machines Market Revenue (million), by Country 2026 & 2034
Figure 61: Asia Pacific Medical Injection Molding Machines Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Medical Injection Molding Machines Market Revenue million Forecast, by Material 2020 & 2034
Table 2: Medical Injection Molding Machines Market Revenue million Forecast, by Application 2020 & 2034
Table 3: Medical Injection Molding Machines Market Revenue million Forecast, by Machine Type 2020 & 2034
Table 4: Medical Injection Molding Machines Market Revenue million Forecast, by Mode of Operation 2020 & 2034
Table 5: Medical Injection Molding Machines Market Revenue million Forecast, by Clamping Force 2020 & 2034
Table 6: Medical Injection Molding Machines Market Revenue million Forecast, by Region 2020 & 2034
Table 7: North America Medical Injection Molding Machines Market Revenue million Forecast, by Material 2020 & 2034
Table 8: North America Medical Injection Molding Machines Market Revenue million Forecast, by Application 2020 & 2034
Table 9: North America Medical Injection Molding Machines Market Revenue million Forecast, by Machine Type 2020 & 2034
Table 10: North America Medical Injection Molding Machines Market Revenue million Forecast, by Mode of Operation 2020 & 2034
Table 11: North America Medical Injection Molding Machines Market Revenue million Forecast, by Clamping Force 2020 & 2034
Table 12: North America Medical Injection Molding Machines Market Revenue million Forecast, by Country 2020 & 2034
Table 13: United States Medical Injection Molding Machines Market Revenue (million) Forecast, by Application 2020 & 2034
Table 14: Canada Medical Injection Molding Machines Market Revenue (million) Forecast, by Application 2020 & 2034
Table 15: Mexico Medical Injection Molding Machines Market Revenue (million) Forecast, by Application 2020 & 2034
Table 16: South America Medical Injection Molding Machines Market Revenue million Forecast, by Material 2020 & 2034
Table 17: South America Medical Injection Molding Machines Market Revenue million Forecast, by Application 2020 & 2034
Table 18: South America Medical Injection Molding Machines Market Revenue million Forecast, by Machine Type 2020 & 2034
Table 19: South America Medical Injection Molding Machines Market Revenue million Forecast, by Mode of Operation 2020 & 2034
Table 20: South America Medical Injection Molding Machines Market Revenue million Forecast, by Clamping Force 2020 & 2034
Table 21: South America Medical Injection Molding Machines Market Revenue million Forecast, by Country 2020 & 2034
Table 22: Brazil Medical Injection Molding Machines Market Revenue (million) Forecast, by Application 2020 & 2034
Table 23: Argentina Medical Injection Molding Machines Market Revenue (million) Forecast, by Application 2020 & 2034
Table 24: Rest of South America Medical Injection Molding Machines Market Revenue (million) Forecast, by Application 2020 & 2034
Table 25: Europe Medical Injection Molding Machines Market Revenue million Forecast, by Material 2020 & 2034
Table 26: Europe Medical Injection Molding Machines Market Revenue million Forecast, by Application 2020 & 2034
Table 27: Europe Medical Injection Molding Machines Market Revenue million Forecast, by Machine Type 2020 & 2034
Table 28: Europe Medical Injection Molding Machines Market Revenue million Forecast, by Mode of Operation 2020 & 2034
Table 29: Europe Medical Injection Molding Machines Market Revenue million Forecast, by Clamping Force 2020 & 2034
Table 30: Europe Medical Injection Molding Machines Market Revenue million Forecast, by Country 2020 & 2034
Table 31: United Kingdom Medical Injection Molding Machines Market Revenue (million) Forecast, by Application 2020 & 2034
Table 32: Germany Medical Injection Molding Machines Market Revenue (million) Forecast, by Application 2020 & 2034
Table 33: France Medical Injection Molding Machines Market Revenue (million) Forecast, by Application 2020 & 2034
Table 34: Italy Medical Injection Molding Machines Market Revenue (million) Forecast, by Application 2020 & 2034
Table 35: Spain Medical Injection Molding Machines Market Revenue (million) Forecast, by Application 2020 & 2034
Table 36: Russia Medical Injection Molding Machines Market Revenue (million) Forecast, by Application 2020 & 2034
Table 37: Benelux Medical Injection Molding Machines Market Revenue (million) Forecast, by Application 2020 & 2034
Table 38: Nordics Medical Injection Molding Machines Market Revenue (million) Forecast, by Application 2020 & 2034
Table 39: Rest of Europe Medical Injection Molding Machines Market Revenue (million) Forecast, by Application 2020 & 2034
Table 40: Middle East & Africa Medical Injection Molding Machines Market Revenue million Forecast, by Material 2020 & 2034
Table 41: Middle East & Africa Medical Injection Molding Machines Market Revenue million Forecast, by Application 2020 & 2034
Table 42: Middle East & Africa Medical Injection Molding Machines Market Revenue million Forecast, by Machine Type 2020 & 2034
Table 43: Middle East & Africa Medical Injection Molding Machines Market Revenue million Forecast, by Mode of Operation 2020 & 2034
Table 44: Middle East & Africa Medical Injection Molding Machines Market Revenue million Forecast, by Clamping Force 2020 & 2034
Table 45: Middle East & Africa Medical Injection Molding Machines Market Revenue million Forecast, by Country 2020 & 2034
Table 46: Turkey Medical Injection Molding Machines Market Revenue (million) Forecast, by Application 2020 & 2034
Table 47: Israel Medical Injection Molding Machines Market Revenue (million) Forecast, by Application 2020 & 2034
Table 48: GCC Medical Injection Molding Machines Market Revenue (million) Forecast, by Application 2020 & 2034
Table 49: North Africa Medical Injection Molding Machines Market Revenue (million) Forecast, by Application 2020 & 2034
Table 50: South Africa Medical Injection Molding Machines Market Revenue (million) Forecast, by Application 2020 & 2034
Table 51: Rest of Middle East & Africa Medical Injection Molding Machines Market Revenue (million) Forecast, by Application 2020 & 2034
Table 52: Asia Pacific Medical Injection Molding Machines Market Revenue million Forecast, by Material 2020 & 2034
Table 53: Asia Pacific Medical Injection Molding Machines Market Revenue million Forecast, by Application 2020 & 2034
Table 54: Asia Pacific Medical Injection Molding Machines Market Revenue million Forecast, by Machine Type 2020 & 2034
Table 55: Asia Pacific Medical Injection Molding Machines Market Revenue million Forecast, by Mode of Operation 2020 & 2034
Table 56: Asia Pacific Medical Injection Molding Machines Market Revenue million Forecast, by Clamping Force 2020 & 2034
Table 57: Asia Pacific Medical Injection Molding Machines Market Revenue million Forecast, by Country 2020 & 2034
Table 58: China Medical Injection Molding Machines Market Revenue (million) Forecast, by Application 2020 & 2034
Table 59: India Medical Injection Molding Machines Market Revenue (million) Forecast, by Application 2020 & 2034
Table 60: Japan Medical Injection Molding Machines Market Revenue (million) Forecast, by Application 2020 & 2034
Table 61: South Korea Medical Injection Molding Machines Market Revenue (million) Forecast, by Application 2020 & 2034
Table 62: ASEAN Medical Injection Molding Machines Market Revenue (million) Forecast, by Application 2020 & 2034
Table 63: Oceania Medical Injection Molding Machines Market Revenue (million) Forecast, by Application 2020 & 2034
Table 64: Rest of Asia Pacific Medical Injection Molding Machines Market Revenue (million) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
The foundation of this report on the Medical Injection Molding Machines Market rests on a robust primary research framework, constituting approximately 70–80% of the total research effort. This intensive engagement with market participants ensures that the forecasts, segmentation analysis, and competitive landscape reflect ground-level realities across the 2026–2034 projection period.
Primary data was gathered through structured interviews, questionnaires, and expert consultations across the following key company types within the medical injection molding machines value chain:
Medical-grade resin and polymer compounders (suppliers of polypropylene, cyclic olefin copolymer, thermoplastic elastomers, and ABS formulations certified for healthcare applications)
Injection molding machine OEMs and system integrators (manufacturers of standard, multi-component, and LSR injection molding platforms serving medical device clients)
Contract medical device manufacturers (CMOs/CMDOs) (facilities producing syringes, diagnostic cartridges, surgical instruments, and drug delivery components under ISO 13485-compliant environments)
Medical device brand owners and pharmaceutical packaging companies (end-users specifying clamping force requirements, material compatibility, and cleanroom-grade automation)
Tooling, mold-making, and validation service providers (specialized vendors supplying precision molds, process validation (IQ/OQ/PQ), and regulatory compliance documentation for medical injection molding lines)
Stakeholder interviews were conducted with the following specific job titles to capture technical, procurement, regulatory, and strategic perspectives:
Validation Engineers / Process Validation Managers at contract medical device manufacturers — providing insight into machine qualification requirements, cleanroom integration standards, and material-specific processing parameters
Medical Device Manufacturing Directors / VP of Operations at OEM medical device companies — offering demand-side perspectives on machine type preferences, clamping force selection, and all-electric vs. hydraulic mode adoption
Regulatory Affairs Specialists (FDA/MDR/ISO 13485 compliance) at medical molding facilities — detailing the impact of evolving device regulations on machine procurement and material selection decisions
Sales & Application Engineers at injection molding machine manufacturers — supplying competitive pricing benchmarks, technological roadmaps for LSR and multi-component systems, and regional deployment trends
Primary research was conducted across all key geographies covered in this report, including North America, Europe, Asia Pacific, South America, and Middle East & Africa, ensuring regional demand nuances — such as ASEAN's growing medical device export capacity or GCC's healthcare infrastructure investments — are accurately captured.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Validation Engineers / Process Validation Managers
28%
Medical Device Manufacturing Directors / VP of Operations
Sales & Application Engineers at Molding Machine Manufacturers
20%
Industry Ecosystem Breakdown
Company Type
Representation (%)
Medical-Grade Resin & Polymer Compounders
18%
Injection Molding Machine OEMs & System Integrators
27%
Contract Medical Device Manufacturers (CMOs/CMDOs)
25%
Medical Device Brand Owners & Pharma Packaging Companies
20%
Tooling, Mold-Making & Validation Service Providers
10%
Secondary Research & Industry Benchmarking
Secondary research accounts for the remaining 20–30% of the research framework, serving as the structural backbone for market sizing validation, regulatory landscape mapping, and competitive benchmarking. All secondary sources are rigorously vetted; data from generic market research aggregator websites is explicitly excluded.
Bloomberg Terminal — for public company financials, capital expenditure trends among medical device manufacturers, and M&A activity in the injection molding equipment sector
Factiva (Dow Jones) — for news intelligence, press releases, and corporate announcements related to medical molding machine deployments and facility expansions
Hoovers (Dun & Bradstreet) — for company profiling, revenue estimates, and industry classification of molding machine OEMs and medical device CMOs
PitchBook — for venture funding, private equity activity, and growth-stage investment tracking in medical-grade polymer processing and device manufacturing technology
Government, Regulatory & Trade Association Sources consulted include:
European Medicines Agency (EMA) — for regulatory directives under EU MDR (2017/745) impacting molding process requirements for pharmaceutical and surgical device components
Plastics Industry Association (PLASTICS) — for injection molding industry shipment data, workforce statistics, and technology adoption benchmarks in medical applications
Trade publications, patent databases, regulatory dockets, and government health infrastructure spending reports (e.g., CMS National Health Expenditure data, WHO Global Health Observatory) were also reviewed to contextualize demand drivers across application segments including surgery, pharma, diagnostics, healthcare, and cosmetics.
Demand Modeling & Market Estimation
Market sizing and forecasting for the Medical Injection Molding Machines Market employ a dual-methodology approach combining top-down and bottom-up estimation, with multi-level data triangulation ensuring internal consistency across segments, geographies, and the 2026–2034 forecast horizon.
Bottom-Up Market Sizing is constructed by aggregating demand at the granular segment level using the following specific metrics and variables:
Number of medical-grade injection molding machine units installed per facility type (surgical device plants, pharmaceutical packaging lines, diagnostics equipment manufacturers) multiplied by average machine selling price stratified by clamping force band (< 200 tons, 200–500 tons, > 500 tons) and mode of operation (all-electric, hybrid, hydraulic)
Annual replacement and capacity expansion rate of injection molding machines in certified medical manufacturing environments (ISO 13485, FDA-registered facilities), estimated at segment level by geography and end-use application
Volume of medical components produced per machine cycle (e.g., syringe barrels, IV connectors, diagnostic cartridge housings, LSR seals) correlated with material-specific processing throughput rates for PP, PE, COC, TPE, and ABS grades
Cleanroom integration and automation premium coefficients applied to standard machine pricing to reflect the incremental capital cost of all-electric and multi-component platforms deployed in Class 7/8 cleanroom environments for pharma and surgical applications
Top-Down Market Sizing cross-references total global medical device manufacturing output value (sourced from FDA, WHO, and national health ministries) with the estimated capital equipment intensity ratio for injection molding machinery as a share of total device manufacturing capex. This macro-level estimate is then disaggregated by region, machine type, and material segment using allocation weights derived from primary interviews and trade association data.
Multi-level data triangulation reconciles demand-side estimates (from medical device OEMs and CMOs), supply-side estimates (from machine OEM revenue disclosures and shipment data), and macro-economic proxies (healthcare infrastructure spending, surgical procedure volumes, pharmaceutical packaging demand growth) to produce a consensus market size with documented variance ranges.
Data Accuracy & Quality Check
All data outputs in this report carry a guaranteed estimated accuracy level of 85–90%, achieved through a structured quality assurance protocol applied at each stage of the research process.
Iterative Respondent Validation: Preliminary findings and draft market size estimates are shared with a subset of primary research participants — specifically Validation Engineers and Manufacturing Directors — for factual verification before data is finalized. Discrepancies exceeding ±10% trigger additional interview cycles or secondary source reconciliation.
Cross-Segment Consistency Checks: Market size totals are validated by ensuring that the sum of all material-type segments (PP, PE, TPE, COC, ABS, Others), application segments (surgery, pharma, diagnostics, healthcare, cosmetics), machine type segments, and operational mode segments independently reconcile to the same reported total market value within an acceptable margin.
Geographic Sanity Benchmarking: Regional estimates are benchmarked against national-level medical device manufacturing output statistics from government sources (e.g., U.S. Census Bureau's Annual Survey of Manufactures, Eurostat, China's NMPA device registration data) to detect and correct outlier projections.
Forecast Assumption Stress-Testing: Key forecast drivers — including healthcare capex growth rates, medical-grade polymer price trajectories, and regulatory compliance adoption timelines (EU MDR, FDA UDI) — are subjected to scenario analysis (base, optimistic, and conservative cases) to ensure that the primary forecast reflects a defensible central estimate rather than a best-case projection.
Continuous Report Currency: Every edition of this report is updated to the date of purchase, incorporating the most recent regulatory approvals, M&A transactions, machine OEM product launches, and macroeconomic indicators available at the time of delivery, ensuring subscribers receive the most current intelligence possible.
Frequently Asked Questions
1. What disruptive technologies are reshaping medical injection molding machines?
All-electric injection molding machines are displacing hydraulic systems due to 50–70% lower energy consumption and cleaner operation suited for ISO-classified medical environments. Multi-component and LSR (Liquid Silicone Rubber) molding technologies are also accelerating adoption, enabling complex single-shot part geometries that reduce assembly steps. Companies like ENGEL AUSTRIA GmbH and ARBURG GmbH are actively commercializing these platforms.
2. How do raw material sourcing challenges affect the medical injection molding machines supply chain?
The market depends heavily on engineering-grade resins including Cyclic Olefin Copolymer (COC), Polypropylene, and Thermoplastic Elastomers, all subject to petrochemical price volatility. COC, widely used in pharmaceutical packaging and diagnostics, is produced by a limited number of global suppliers, creating concentration risk. Supply disruptions in Asia-Pacific resin production can directly delay machine utilization rates and OEM delivery schedules.
3. Who is investing in the medical injection molding machines market and what is the level of venture capital activity?
Strategic investment has been led by large industrial conglomerates rather than early-stage venture capital; Hillenbrand Inc.'s acquisition of Milacron Holdings and CNCC's ownership of KraussMaffei Group illustrate consolidation-driven capital deployment. Private equity interest is concentrated in automation integration and cleanroom-compatible machine retrofits. The market's $867.10 million valuation and 4.8% CAGR make it attractive for mid-market industrial PE funds targeting medtech adjacencies.
4. What are the primary growth drivers fueling demand for medical injection molding machines?
Rising global demand for single-use medical devices, disposable diagnostic equipment, and prefilled pharmaceutical delivery systems is the core demand catalyst. Aging demographics in North America and Europe are increasing surgical procedure volumes, directly expanding consumption of injection-molded components in Surgery and Pharma application segments. Regulatory pressure for contamination-free manufacturing is also accelerating the shift from hydraulic to all-electric machine configurations.
5. What are the major challenges and restraints limiting medical injection molding machines market growth?
High capital expenditure for all-electric and multi-component machines—often 30–50% above standard hydraulic equivalents—restricts adoption among small and mid-sized medical component manufacturers. Stringent FDA, EU MDR, and ISO 13485 compliance requirements extend validation timelines and increase total cost of ownership. Additionally, dependence on skilled tooling and process engineers creates a talent bottleneck that constrains production scale-up across emerging markets.
6. Which region dominates the medical injection molding machines market and why?
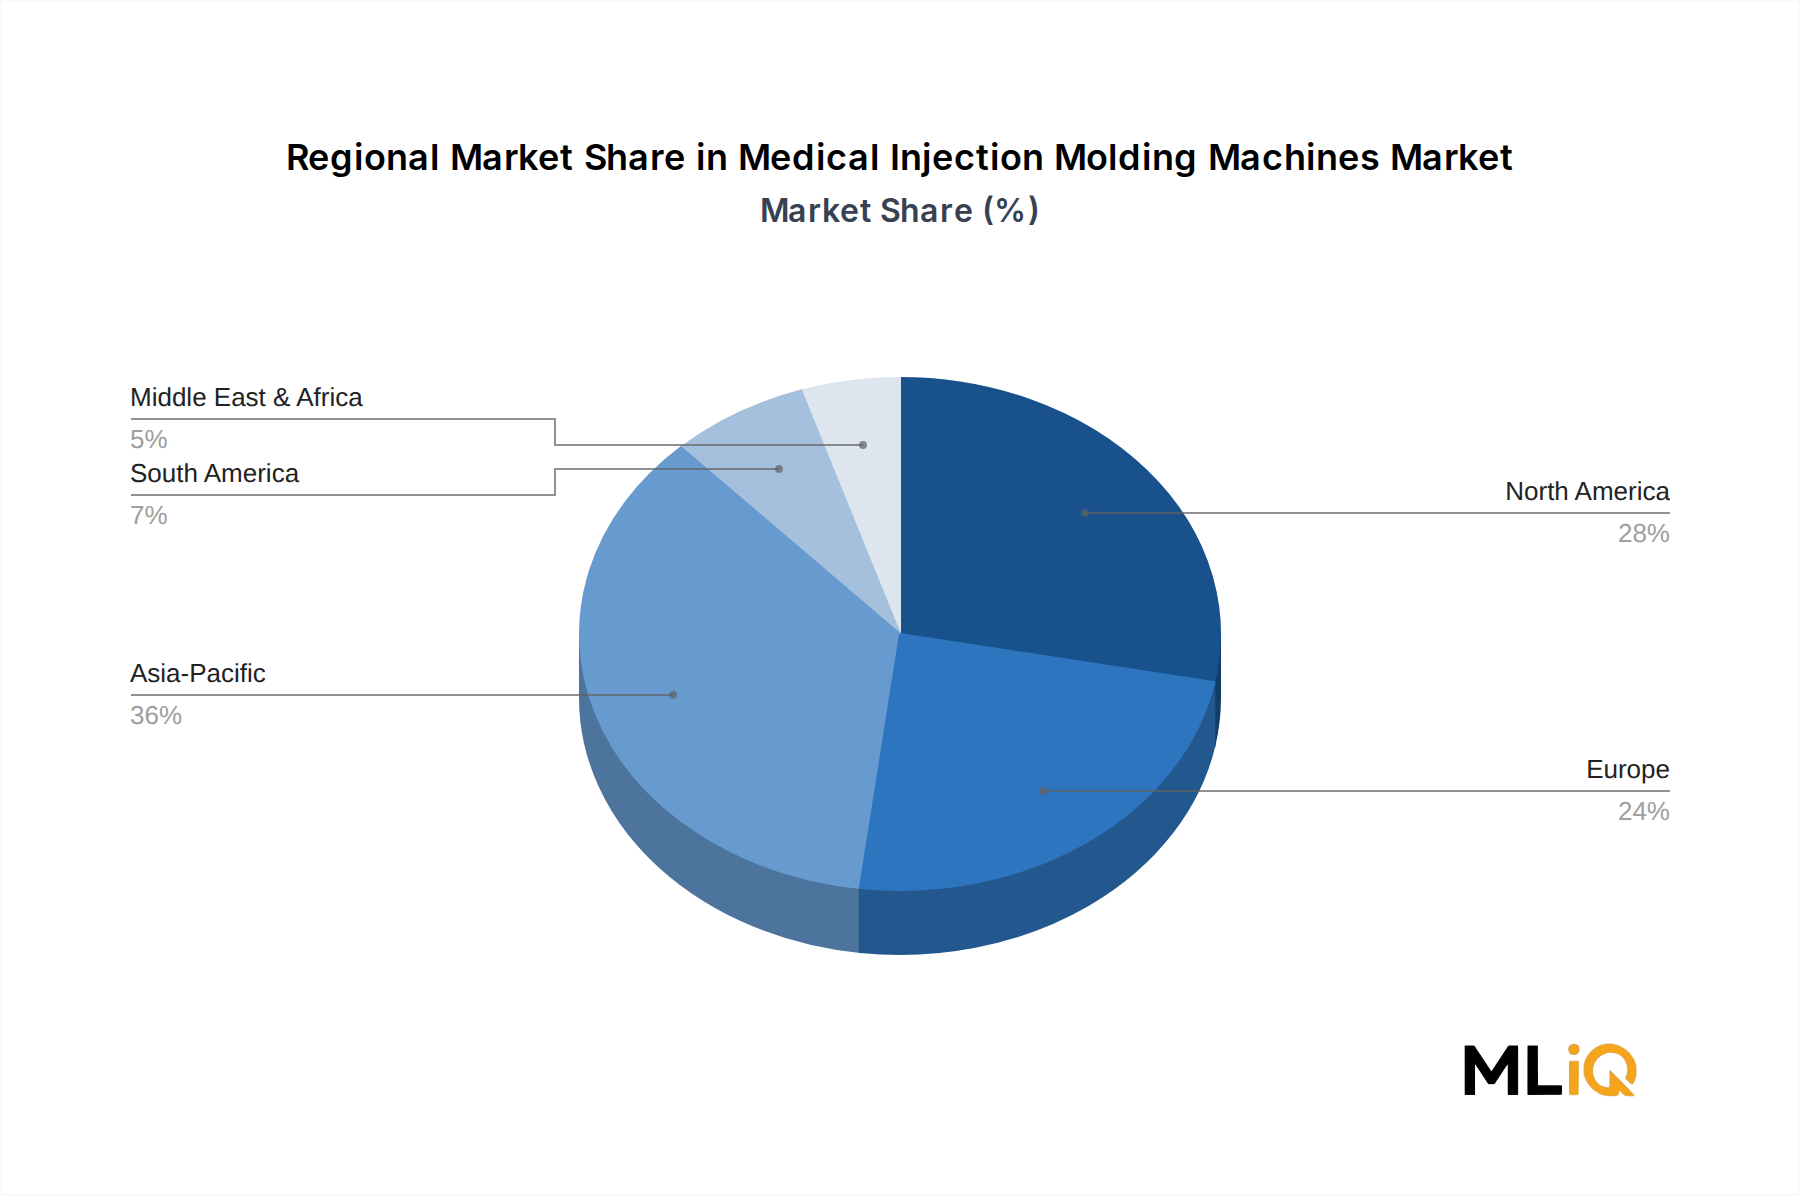
Asia-Pacific holds the largest regional share at approximately 36%, driven by China's scale in medical device manufacturing, Japan's precision engineering base anchored by companies like Sumitomo Heavy Industries and The Japan Steel Works (JSW), and India's expanding pharmaceutical production infrastructure. Low labor costs, growing domestic healthcare expenditure, and government-backed medtech manufacturing incentives reinforce the region's structural cost advantage. North America follows at roughly 28%, supported by high per-unit device value and strict quality-driven capital investment cycles.