Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Unmanned Ground Vehicle Market to Reach USD 5.61B by 2033
Unmanned Ground Vehicle Market
Unmanned Ground Vehicle Market to Reach USD 5.61B by 2033
Unmanned Ground Vehicle Market by Application (Military, Civil and Commercial), by Mobility (Wheeled, Tracked, Legged), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 24, 2026|Base Year : 2025|Pages : 234
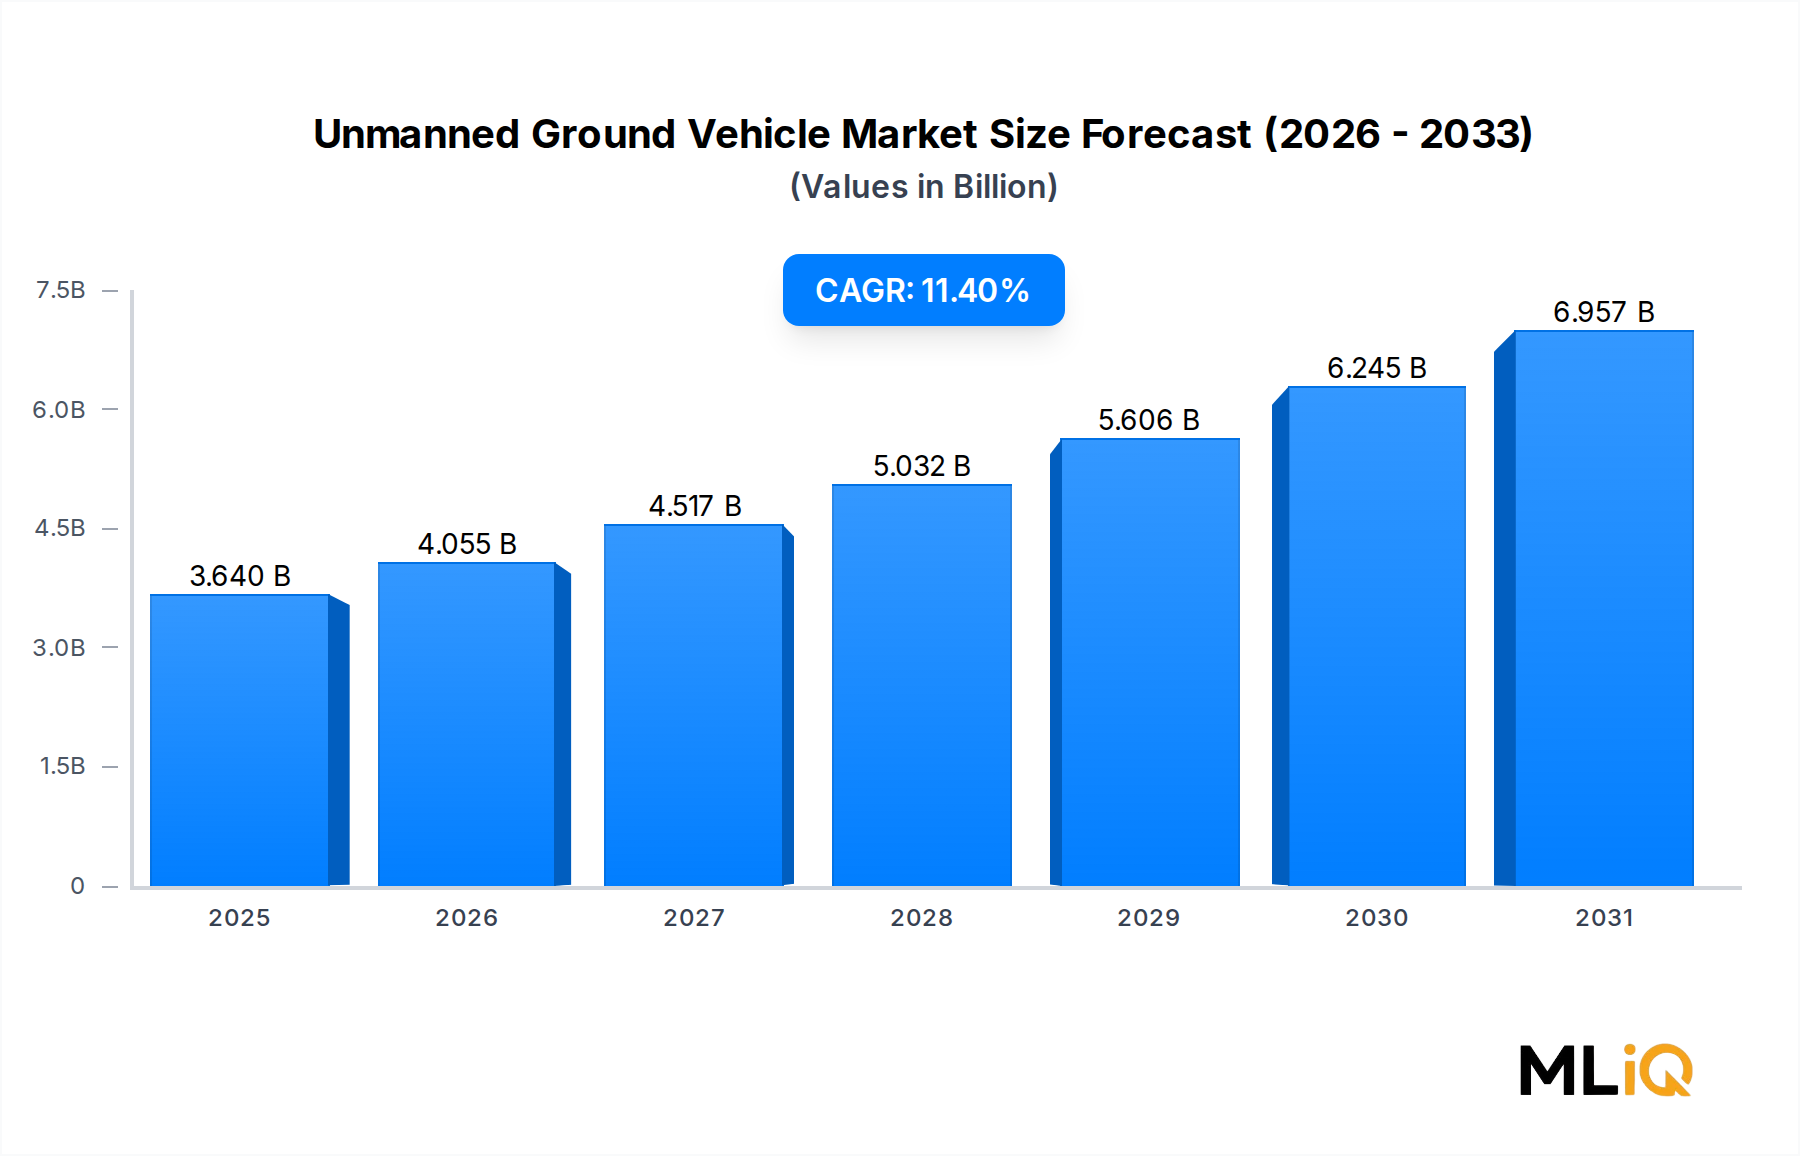
The global unmanned ground vehicle (UGV) sector closed 2025 at USD 3.02 billion and is forecast to reach USD 5.61 billion by 2033, expanding at a CAGR of 8.06%. Growth is pulled by defense modernization budgets rather than commercial demand, which remains a minority share of revenue and is growing more slowly.
Unmanned Ground Vehicle Market Size (In Million)
5.0M
4.0M
3.0M
2.0M
1.0M
0
3.000 M
2025
3.000 M
2026
4.000 M
2027
4.000 M
2028
4.000 M
2029
4.000 M
2030
5.000 M
2031
Structural demand signals
Military procurement represents roughly 68% of global UGV revenue in 2025, or about USD 2.05 billion.
Modular payload architectures for EO/IR, CBRN, and counter-IED missions cut per-mission retrofit cost by an estimated 20-30%.
The broader Unmanned Systems Market, spanning aerial, ground, and maritime platforms, is expanding faster than any single domain because autonomy stacks are increasingly shared across them.
Macro drivers
Rising adoption of IoT and autonomous systems in logistics, agriculture, and industrial inspection.
Demand for military satellite communication and beyond-line-of-sight datalinks, which underpin teleoperation of ground platforms across contested terrain.
Multi-year procurement programs in the United States, Turkey, Israel, and the Nordic states.
Constraints
Cybersecurity exposure in command-and-control links and radio-frequency interference limit operation in contested electromagnetic environments.
Unit costs for tracked combat UGVs of USD 1.5-3.5 million per platform restrict volumes to tier-one defense budgets.
What to watch through 2033
Tracked platforms growing fastest at 9.2% CAGR, driven by combat engineering and casualty evacuation roles.
Asia-Pacific investment accelerating as China, India, and South Korea field indigenous chassis.
Software-defined autonomy becoming the primary differentiation vector, shifting value from hardware toward perception and navigation stacks.
Segment Deep-Dive: Military Application Dominance in Unmanned Ground Vehicle Market
Segment Analysis Matrix
Segment
Growth Rate (CAGR %)
Market Share (%)
Key Demand Driver
Military (Application)
8.9%
68%
EOD, route clearance, casualty evacuation
Civil and Commercial (Application)
6.7%
32%
Inspection, agriculture, mining, logistics
Tracked (Mobility)
9.2%
41%
Rough-terrain engineering, payload mass
Wheeled (Mobility)
7.6%
52%
Lower unit cost, road mobility, sustainment
Legged (Mobility)
10.4%
7%
Stair and rubble navigation, subterranean tasks
Military Application: The Revenue Core
Military applications generated roughly USD 2.05 billion of the 2025 base and anchor both the Wheeled Unmanned Ground Vehicle Market and the Tracked Unmanned Ground Vehicle Market.
Explosive ordnance disposal and counter-IED remain the highest-volume use cases; teleoperated route clearance follows closely.
Procurement is contract-driven: a single program of record can shift annual volumes by double digits, producing lumpy revenue recognition for primes and subsystem suppliers.
Mobility Split: Wheeled, Tracked, Legged
Wheeled platforms hold 52% of units shipped because acquisition cost falls between USD 150,000 and 600,000 and maintenance is simpler.
Tracked platforms carry a 35-50% price premium but win on soft soil, gradient, and payload mass.
Legged designs hold a 7% niche concentrated in subterranean and urban reconnaissance trials, where commercial pricing is still unproven.
Civil and Commercial Applications: The Slower but Broader Half
Growth sits at 6.7% CAGR, held back by fragmented buyer budgets and the absence of certification frameworks for public-road operation.
Participants in the Civil and Commercial Robotics Market target mining, agriculture, and utility inspection first, where autonomy operates inside closed or semi-controlled environments.
Price sensitivity is acute: commercial buyers require payback under 24 months, which caps the sensor and compute bill of materials.
Margin Pressures
Gross margins on military chassis run 25-35%; dedicated payload and software suppliers regularly exceed 50%.
Fixed-price development contracts transfer engineering risk to vendors and compress margins during low-rate initial production.
Component inflation in ruggedized compute, EO/IR detectors, and battery cells has added 4-7% to unit cost since 2022.
IoT and autonomous systems adoption across defense and industry
High
Long term
Driver
Military satellite communication demand for BLOS teleoperation
High
Short term
Driver
Manpower reduction targets in NATO ground forces
Medium
Long term
Driver
Falling LiDAR and ruggedized compute costs
Medium
Short term
Restraint
Cybersecurity threats to command-and-control links
High
Long term
Restraint
RF interference and jamming in contested spectrum
High
Short term
Restraint
High unit cost and thin sustainment infrastructure
Medium
Long term
Restraint
Absence of civil certification and liability frameworks
Medium
Long term
Driver Quantification
The Military Robotics Market benefits from bloc-level capability targets: several NATO members have committed to fielding robotic ground systems by 2030, creating a multi-year demand floor.
Leaders in the Autonomous Navigation System Market report that GNSS-denied operation is now a mandatory specification rather than an option, which raises sensor content per platform by an estimated 15-25%.
Industrial buyers using UGVs for inspection and haulage report 18-30% reductions in hazardous-manual-labor hours, the strongest commercial pull in the base year.
Restraint Quantification
Jamming and spoofing against command links can render a platform unusable within seconds; hardening against this adds 5-10% to platform cost.
Unit economics remain the binding constraint outside tier-one budgets, where a single tracked system equals the annual equipment spend of a small municipal agency.
Civil liability exposure for autonomous ground machines is unresolved in most jurisdictions, delaying fleet-scale commercial deployment.
Tracked and wheeled mission systems, effects integration
European and NATO forces
Leader
Milrem AS
Modular hybrid-electric UGV chassis
NATO and export defense buyers
Challenger
Oshkosh Corporation
Wheeled vehicle autonomy and convoy retrofit
U.S. Army logistics commands
Challenger
QinetiQ Group PLC
Route clearance and testing/evaluation services
UK MoD and allied programs
Challenger
Israel Aerospace Industries Ltd
Autonomy, robotics, and export-ready defense systems
Global defense export markets
Leader
ASELSAN AS
Border security and electronic systems integration
Turkey, GCC, and allied exports
Challenger
Textron Inc
Robotic combat vehicle prototyping and mobility
U.S. Army development programs
Niche
Vendor Profiles
General Dynamics Corporation: Leverages combat vehicle integration scale to bundle UGV payloads with existing ground platform programs, giving the firm outsized influence over program-of-record awards.
Teledyne FLIR LLC: Sensor leadership across EO/IR and thermal imaging positions the company as a default payload partner for nearly every tracked and wheeled platform in production.
Rheinmetall AG: Fields a broad robotic mission family and pairs chassis supply with effects and remote weapon station integration, capturing value across two layers of the chain.
Milrem AS: Modular hybrid-electric architecture and rapid NATO-market traction make it the most credible challenger to incumbent prime platforms.
Oshkosh Corporation: Convoy autonomy retrofits align with U.S. Army logistics modernization, where autonomy improves on-road resupply security with minimal new fleet investment.
QinetiQ Group PLC: Route clearance systems plus deep test and evaluation capability create a dual revenue base across platform sales and assurance services.
Israel Aerospace Industries Ltd: Combines mature autonomy stacks with export-ready productization, particularly for border and perimeter security buyers.
ASELSAN AS: Electronic systems strength translates into integrated border security packages with domestic and GCC buyers.
Textron Inc: Focused prototype and mobility work gives it a development-stage position, with upside tied to U.S. Army robotic combat vehicle milestones rather than near-term volume.
Strategic Milestones & Recent Developments in Unmanned Ground Vehicle Market
Latest Strategic Moves
Date
Company
Event Type
Impact
2023
EDGE Group / Milrem AS
M&A (majority stake)
High
2024
Rheinmetall AG
Platform launch
High
2024
Textron Inc
Partnership (robotic combat vehicle prototyping)
Medium
2024
Israel Aerospace Industries Ltd
Export clearance for robotic systems
Medium
2025
Teledyne FLIR LLC
Payload launch (CBRN reconnaissance)
Medium
2025
Oshkosh Corporation
Partnership (autonomous convoy retrofit)
Medium
2025
ASELSAN AS
Contract award (border security UGVs)
Medium
2025
QinetiQ Group PLC
Contract (route clearance systems)
Medium
Chronological Detail
2023 - Consolidation in chassis supply: The EDGE Group majority stake in Milrem AS created a Gulf-based champion with European engineering, reshaping competitive dynamics in modular UGV supply.
2024 - Platform expansion: Rheinmetall extended its robotic mission family, tightening integration between chassis, effectors, and remote weapon stations for NATO buyers.
2024 - Development-stage partnerships: Textron advanced robotic combat vehicle prototyping, keeping the United States as the single largest catalyst for wheeled and tracked volumes.
2025 - Payload and retrofit momentum: Teledyne FLIR and Oshkosh both pushed capabilities that raise autonomy and sensing content per fielded platform, supporting the 8.06% base-case CAGR.
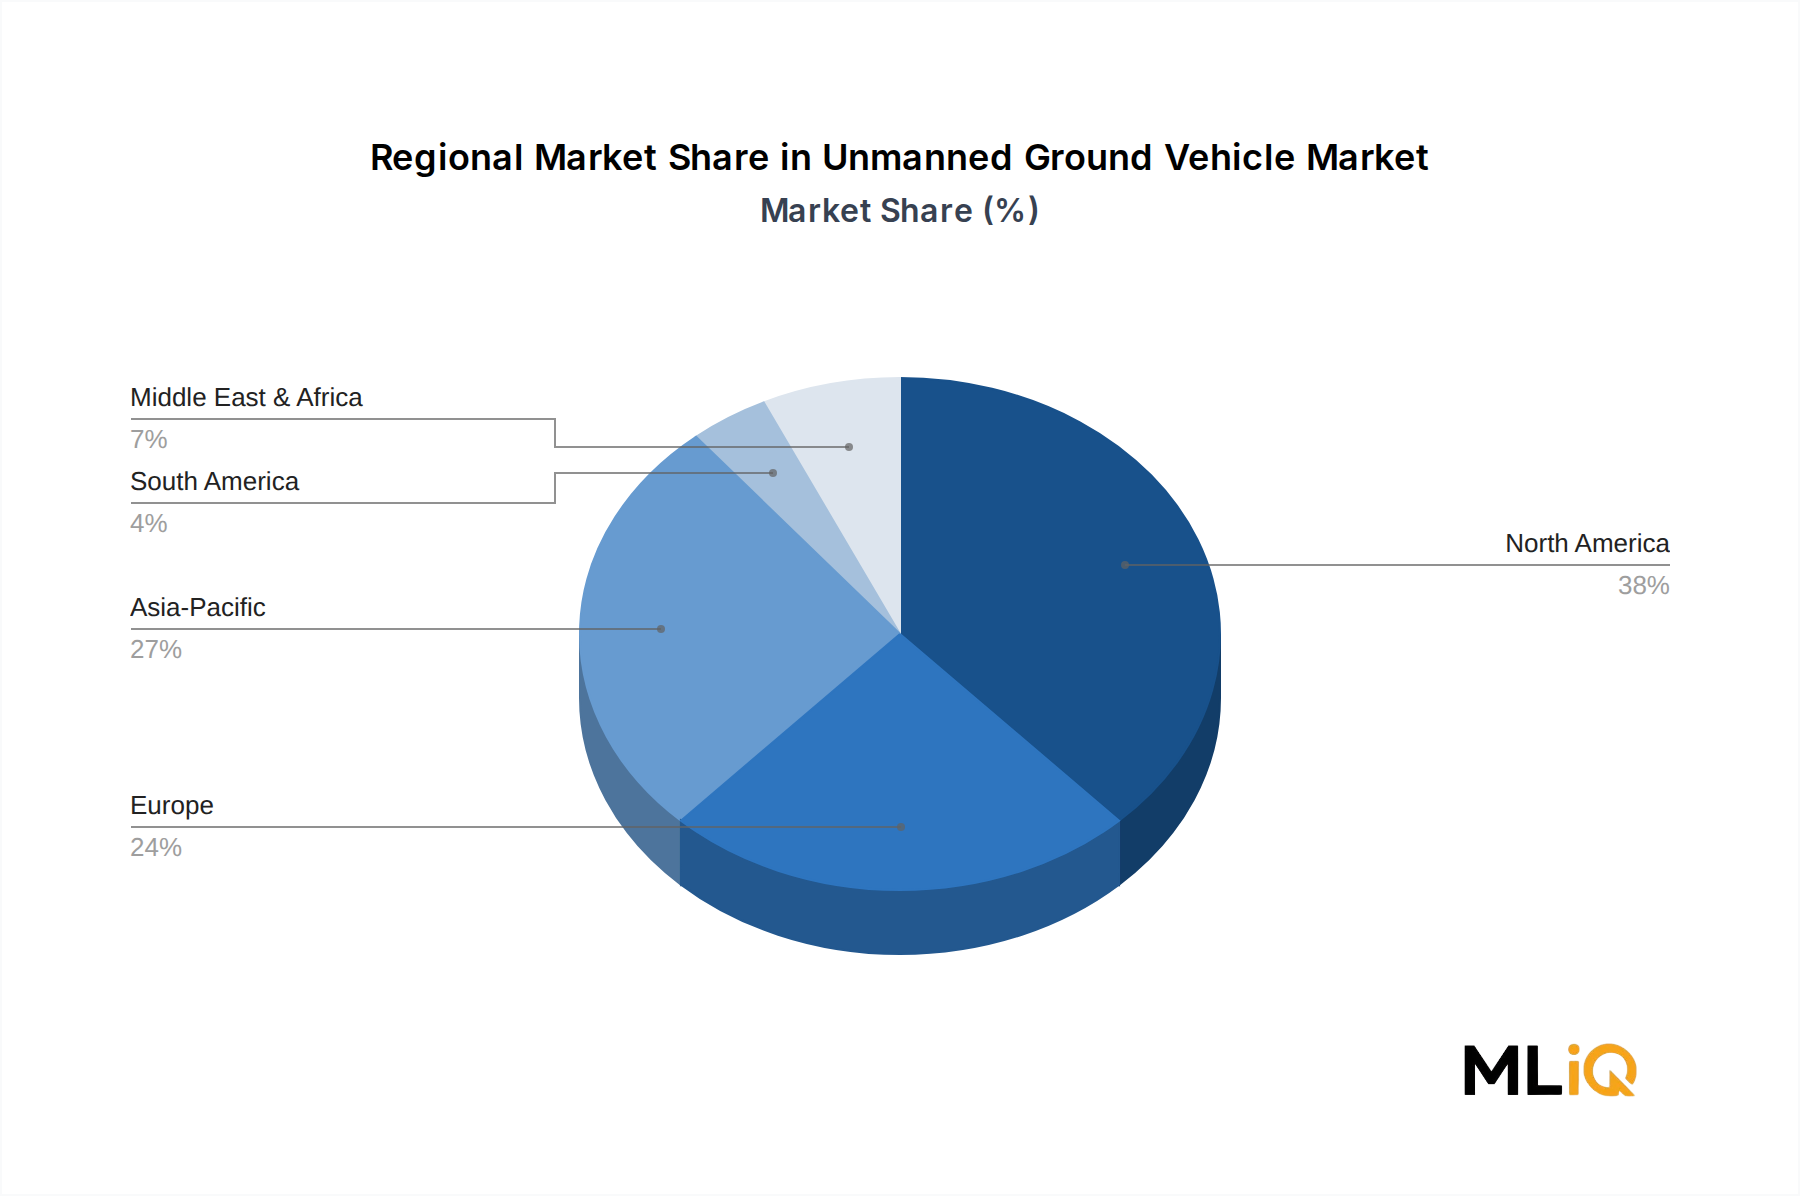
Asia-Pacific leads at 9.5% CAGR, with local production lowering unit costs and reducing reliance on Western export approvals.
Middle East & Africa runs at 8.9%, where border surveillance and counter-IED missions justify premium tracked and wheeled platforms.
Europe expands at 8.4%, supported by bloc-level funding and multi-year capability targets that favor regional suppliers.
Most Mature Markets
North America holds 38% of global value, or USD 1.15 billion, and grows more slowly at 7.6% because the installed base is already large.
Procurement here is dominated by a small number of programs of record, so annual revenue swings track budget cycles rather than underlying capability demand.
South America remains the smallest and slowest region at 6.2% CAGR, with mining automation in Brazil and Chile the most bankable near-term use case.
Supply Chain & Raw Material Dynamics: Unmanned Ground Vehicle Market
Upstream Input Risk Matrix
Input
Sourcing Concentration
Price Trend
Risk Level
Lithium-ion cells
China-dominant cell manufacturing
Stable to rising
High
EO/IR detector materials (germanium, InSb)
Few qualified suppliers
Rising
High
Titanium alloys
Russia, China, U.S.
Volatile
High
Armor-grade steel
Regional mills
Stable
Medium
GaN RF components
Taiwan, U.S., Europe
Rising
Medium
Rare-earth magnets
China-dominant refining
Volatile
High
Structural Dependencies
The Lithium-Ion Battery Market supplies the single most supply-sensitive input for hybrid-electric UGVs; cell allocation now constrains production planning as much as chassis capacity does.
The Defense Electronics Market, spanning ruggedized processors, GaN amplifiers, and radiation-tolerant components, sits behind 6-9 month lead times for qualified parts.
The Titanium Alloy Market remains exposed to geopolitical disruption, and aerospace-grade substitution approvals add 6-12 months to any sourcing change.
Historical Disruption Patterns
Semiconductor shortages between 2021 and 2023 delayed autonomy retrofit programs and pushed some buyers toward commercial-grade substitutes with reduced environmental qualification.
Battery cell price volatility since 2022 added 4-7% to platform cost, an effect that procurement offices absorbed rather than passed to end users.
Traceability requirements on conflict-sensitive minerals increase documentation overhead for every tier-two supplier.
Wheeled platforms average USD 150,000-600,000, while tracked combat variants reach USD 1.5-3.5 million, producing a bimodal price distribution.
ASPs are rising at roughly 3-5% annually on higher sensor and compute content, even where chassis prices stay flat.
Payload and software content now accounts for 30-40% of total platform value, up from a fifth a decade ago.
Margin Structure Across the Chain
Chassis integrators operate at 25-35% gross margin; autonomy software and sensor suppliers routinely exceed 50%.
Fixed-price development contracts shift engineering risk downstream and compress margins during low-rate initial production.
Pricing power favors qualified software suppliers and payload specialists, whose switching costs are measured in years of re-integration and re-testing.
Competitive Pricing Pressure
Commercial buyers in inspection and agriculture anchor negotiations to a 24-month payback threshold, capping achievable price points.
Asian manufacturers are compressing entry-level wheeled pricing, forcing Western vendors to compete on sustainment, certification, and integration depth rather than unit cost.
Outlook
Sustained 8.06% CAGR through 2033 depends on holding margin through software and sustainment rather than hardware volume alone.
Unmanned Ground Vehicle Market Segmentation
1. Application
1.1. Military
1.2. Civil and Commercial
2. Mobility
2.1. Wheeled
2.2. Tracked
2.3. Legged
Unmanned Ground Vehicle Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Unmanned Ground Vehicle Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 8.06% from 2020-2034
Segmentation
By Application
Military
Civil and Commercial
By Mobility
Wheeled
Tracked
Legged
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Application
5.1.1. Military
5.1.2. Civil and Commercial
5.2. Market Analysis, Insights and Forecast - by Mobility
5.2.1. Wheeled
5.2.2. Tracked
5.2.3. Legged
5.3. Market Analysis, Insights and Forecast - by Region
5.3.1. North America
5.3.2. South America
5.3.3. Europe
5.3.4. Middle East & Africa
5.3.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Application
6.1.1. Military
6.1.2. Civil and Commercial
6.2. Market Analysis, Insights and Forecast - by Mobility
6.2.1. Wheeled
6.2.2. Tracked
6.2.3. Legged
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Application
7.1.1. Military
7.1.2. Civil and Commercial
7.2. Market Analysis, Insights and Forecast - by Mobility
7.2.1. Wheeled
7.2.2. Tracked
7.2.3. Legged
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Application
8.1.1. Military
8.1.2. Civil and Commercial
8.2. Market Analysis, Insights and Forecast - by Mobility
8.2.1. Wheeled
8.2.2. Tracked
8.2.3. Legged
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Application
9.1.1. Military
9.1.2. Civil and Commercial
9.2. Market Analysis, Insights and Forecast - by Mobility
9.2.1. Wheeled
9.2.2. Tracked
9.2.3. Legged
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Application
10.1.1. Military
10.1.2. Civil and Commercial
10.2. Market Analysis, Insights and Forecast - by Mobility
10.2.1. Wheeled
10.2.2. Tracked
10.2.3. Legged
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Teledyne FLIR LLC
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. General Dynamics Corporation
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Rheinmetall AG
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Oshkosh Corporation
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. ECA GROUP
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Aunav (everis Aeroespacial y Defensa SLU)
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. HORIBA MIRA Ltd
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. ASELSAN AS
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. QinetiQ Group PLC
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Telerob GmbH (AeroVironment Inc )
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Milrem AS
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. Roboteam
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. Israel Aerospace Industries Ltd
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.1.14. Textron Inc
11.1.14.1. Company Overview
11.1.14.2. Products
11.1.14.3. Company Financials
11.1.14.4. SWOT Analysis
11.1.15. Leonardo SpA
11.1.15.1. Company Overview
11.1.15.2. Products
11.1.15.3. Company Financials
11.1.15.4. SWOT Analysis
11.1.16. Peraton Corp
11.1.16.1. Company Overview
11.1.16.2. Products
11.1.16.3. Company Financials
11.1.16.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Unmanned Ground Vehicle Market Revenue Breakdown (billionusdbillion, %) by Region 2026 & 2034
Figure 2: North America Unmanned Ground Vehicle Market Revenue (billionusdbillion), by Application 2026 & 2034
Figure 3: North America Unmanned Ground Vehicle Market Revenue Share (%), by Application 2026 & 2034
Figure 4: North America Unmanned Ground Vehicle Market Revenue (billionusdbillion), by Mobility 2026 & 2034
Figure 5: North America Unmanned Ground Vehicle Market Revenue Share (%), by Mobility 2026 & 2034
Figure 6: North America Unmanned Ground Vehicle Market Revenue (billionusdbillion), by Country 2026 & 2034
Figure 7: North America Unmanned Ground Vehicle Market Revenue Share (%), by Country 2026 & 2034
Figure 8: South America Unmanned Ground Vehicle Market Revenue (billionusdbillion), by Application 2026 & 2034
Figure 9: South America Unmanned Ground Vehicle Market Revenue Share (%), by Application 2026 & 2034
Figure 10: South America Unmanned Ground Vehicle Market Revenue (billionusdbillion), by Mobility 2026 & 2034
Figure 11: South America Unmanned Ground Vehicle Market Revenue Share (%), by Mobility 2026 & 2034
Figure 12: South America Unmanned Ground Vehicle Market Revenue (billionusdbillion), by Country 2026 & 2034
Figure 13: South America Unmanned Ground Vehicle Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Unmanned Ground Vehicle Market Revenue (billionusdbillion), by Application 2026 & 2034
Figure 15: Europe Unmanned Ground Vehicle Market Revenue Share (%), by Application 2026 & 2034
Figure 16: Europe Unmanned Ground Vehicle Market Revenue (billionusdbillion), by Mobility 2026 & 2034
Figure 17: Europe Unmanned Ground Vehicle Market Revenue Share (%), by Mobility 2026 & 2034
Figure 18: Europe Unmanned Ground Vehicle Market Revenue (billionusdbillion), by Country 2026 & 2034
Figure 19: Europe Unmanned Ground Vehicle Market Revenue Share (%), by Country 2026 & 2034
Figure 20: Middle East & Africa Unmanned Ground Vehicle Market Revenue (billionusdbillion), by Application 2026 & 2034
Figure 21: Middle East & Africa Unmanned Ground Vehicle Market Revenue Share (%), by Application 2026 & 2034
Figure 22: Middle East & Africa Unmanned Ground Vehicle Market Revenue (billionusdbillion), by Mobility 2026 & 2034
Figure 23: Middle East & Africa Unmanned Ground Vehicle Market Revenue Share (%), by Mobility 2026 & 2034
Figure 24: Middle East & Africa Unmanned Ground Vehicle Market Revenue (billionusdbillion), by Country 2026 & 2034
Figure 25: Middle East & Africa Unmanned Ground Vehicle Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Asia Pacific Unmanned Ground Vehicle Market Revenue (billionusdbillion), by Application 2026 & 2034
Figure 27: Asia Pacific Unmanned Ground Vehicle Market Revenue Share (%), by Application 2026 & 2034
Figure 28: Asia Pacific Unmanned Ground Vehicle Market Revenue (billionusdbillion), by Mobility 2026 & 2034
Figure 29: Asia Pacific Unmanned Ground Vehicle Market Revenue Share (%), by Mobility 2026 & 2034
Figure 30: Asia Pacific Unmanned Ground Vehicle Market Revenue (billionusdbillion), by Country 2026 & 2034
Figure 31: Asia Pacific Unmanned Ground Vehicle Market Revenue Share (%), by Country 2026 & 2034
Table 46: Rest of Asia Pacific Unmanned Ground Vehicle Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
70-80% of total research effort is derived from primary intelligence gathering, conducted directly with participants across the unmanned ground vehicle value chain.
Company types interviewed include: tracked UGV chassis integrators for combat engineering and route-clearance missions; wheeled UGV OEMs serving logistics and border-security programs; teleoperation and autonomy software developers building perception and path-planning modules; ruggedized compute and EO/IR sensor payload suppliers; and remote weapon station integrators operating alongside defense prime systems integrators.
Stakeholder titles interviewed include: Program Executive Officer, Robotic Combat Vehicle Programs; UGV Autonomy Systems Engineering Lead; Defense Procurement and Acquisition Director, Robotics Portfolio; Payload Integration Manager, EO/IR and Sensor Systems; and Ground Vehicle Sustainment and Field Support Manager.
Interview programs run 30-60 minutes per respondent and are structured to capture program timelines, unit volume expectations, pricing behavior, and qualification barriers.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
UGV Autonomy Systems Engineering Lead
28%
Program Executive Officer, Robotic Combat Vehicle Programs
26%
Defense Procurement and Acquisition Director
24%
Payload Integration Manager, EO/IR and Sensor Systems
22%
Industry Ecosystem Breakdown
Company Type
Representation (%)
Tracked UGV Chassis Integrators
28%
Wheeled UGV OEMs
24%
Autonomy Software & Sensor Suppliers
18%
Payload & Remote Weapon Station Integrators
16%
Defense Prime Systems Integrators
14%
Secondary Research & Industry Benchmarking
20-30% of total research effort draws on secondary sources, used to frame hypotheses before primary validation and to benchmark disclosed figures afterward.
Financial and deal databases used include Bloomberg, Factiva, Hoovers, and PitchBook for vendor revenue, capital structure, contract awards, and M&A activity.
Trade association publications, technical standards documents, and manufacturer filings are used for capability specifications; market research websites are explicitly excluded from the source set.
Every report is updated to the date of purchase, so all secondary benchmarking reflects the latest available filings and award notices.
Demand Modeling & Market Estimation
Top-down and bottom-up methodologies are applied simultaneously, then reconciled through multi-level data triangulation across platform, segment, and geography.
Bottom-up quantification relies on specific measurable inputs, including: the number of actively fielded UGV units and annual procurement volumes by program of record; average unit selling price by mobility class (wheeled, tracked, legged); defense robotics R&D allocation as a share of total ground procurement budgets; and average platform replacement and attrition cycles measured in years.
Segment builds are constructed separately for Application (Military, Civil and Commercial) and Mobility (Wheeled, Tracked, Legged), then aggregated to regional totals for North America, South America, Europe, Middle East & Africa, and Asia-Pacific.
Top-down validation uses published defense ground-vehicle budgets and robotics program allocations to constrain the modeled addressable value at USD 3.02 billion in 2025.
A guaranteed estimated data accuracy level of 85-90% is applied to all headline market values, growth rates, and segment shares.
Data Accuracy & Quality Check
A guaranteed estimated data accuracy level of 85-90% is maintained through cross-validation between primary interview outputs and secondary disclosed figures.
Multi-level data triangulation is performed at three tiers: component and payload level, platform and segment level, and regional aggregate level.
Discrepancies above a 10% variance threshold trigger re-interview or re-benchmarking before publication.
Regional and segment estimates are sanity-checked against independent defense expenditure data and against the sum of top-vendor revenue estimates, with residual values assigned to long-tail suppliers.
Every report is updated to the date of purchase, ensuring the delivered dataset reflects the most recent program awards, pricing updates, and regulatory changes available at delivery.
Frequently Asked Questions
1. Which end-user industries generate demand in the Unmanned Ground Vehicle Market, and how is that demand structured?
Defense ministries and interior security agencies account for roughly 68% of global revenue, concentrated in explosive ordnance disposal, route clearance, and casualty evacuation programs. The remaining 32% comes from mining, agriculture, utility inspection, and warehouse logistics, where buyers demand payback under 24 months. Military demand is contract-driven and lumpy, while civil demand is fragmented but volume-scalable.
2. Which region is growing fastest, and where are the emerging geographic opportunities?
Asia-Pacific is the fastest-growing region at an estimated 9.5% CAGR, supported by indigenous chassis programs in China, India, and South Korea. The Middle East & Africa follows at 8.9%, driven by border security and counter-IED procurement in the GCC and Turkey. South America remains the smallest at USD 0.15 billion, with mining automation in Brazil and Chile the primary entry point.
3. What are the main barriers to entry and competitive moats in this industry?
Program-of-record qualification cycles of 3 to 6 years, ITAR and export-control compliance, and NATO STANAG interoperability testing form the steepest barriers. Incumbents such as General Dynamics, Rheinmetall, and Milrem AS protect share through fielded fleets, sustainment contracts, and classified payload integration experience. Autonomy software stacks represent a newer moat, since perception models trained on operational terrain data are difficult to replicate.
4. What are the primary growth drivers and demand catalysts?
Two catalysts dominate: expanding adoption of IoT and autonomous systems across defense and industry, and rising demand for military satellite communication and beyond-line-of-sight datalinks that enable teleoperation. NATO manpower reduction targets and falling LiDAR and ruggedized compute costs add secondary momentum. Roughly 20 to 30% of per-mission retrofit cost is eliminated by modular payload architectures, which lowers the barrier for fleet-wide upgrades.
5. How are technological innovations and R&D trends shaping the market?
Development spend is shifting from chassis hardware to software-defined autonomy, with perception, path planning, and swarming behavior becoming the primary differentiators. Tracked platforms are growing at 9.2% CAGR and legged designs at 10.4%, though legged units hold only 7% share because commercial pricing is unproven. Hybrid-electric drivetrains and onboard edge inference for GPS-denied navigation are the two most active R&D vectors.
6. How does the regulatory environment affect compliance and market access?
Defense procurement rules, ITAR and EU dual-use export controls, and NATO standardization agreements govern most military sales and add 6 to 18 months to qualification timelines. Civil deployment is constrained by the absence of public-road certification and unclear liability frameworks. ISO 17757 for autonomous machine safety and AUVSI-led standards work are the reference points most buyers cite in tenders.