Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Turboprop Engine Market CAGR 8.25% to Reach $2.83B by 2033
Turboprop Engine Market
Turboprop Engine Market CAGR 8.25% to Reach $2.83B by 2033
Turboprop Engine Market by Application (Commercial Aircraft, Military Aircraft, General Aviation Aircraft), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 30, 2026|Base Year : 2025|Pages : 234
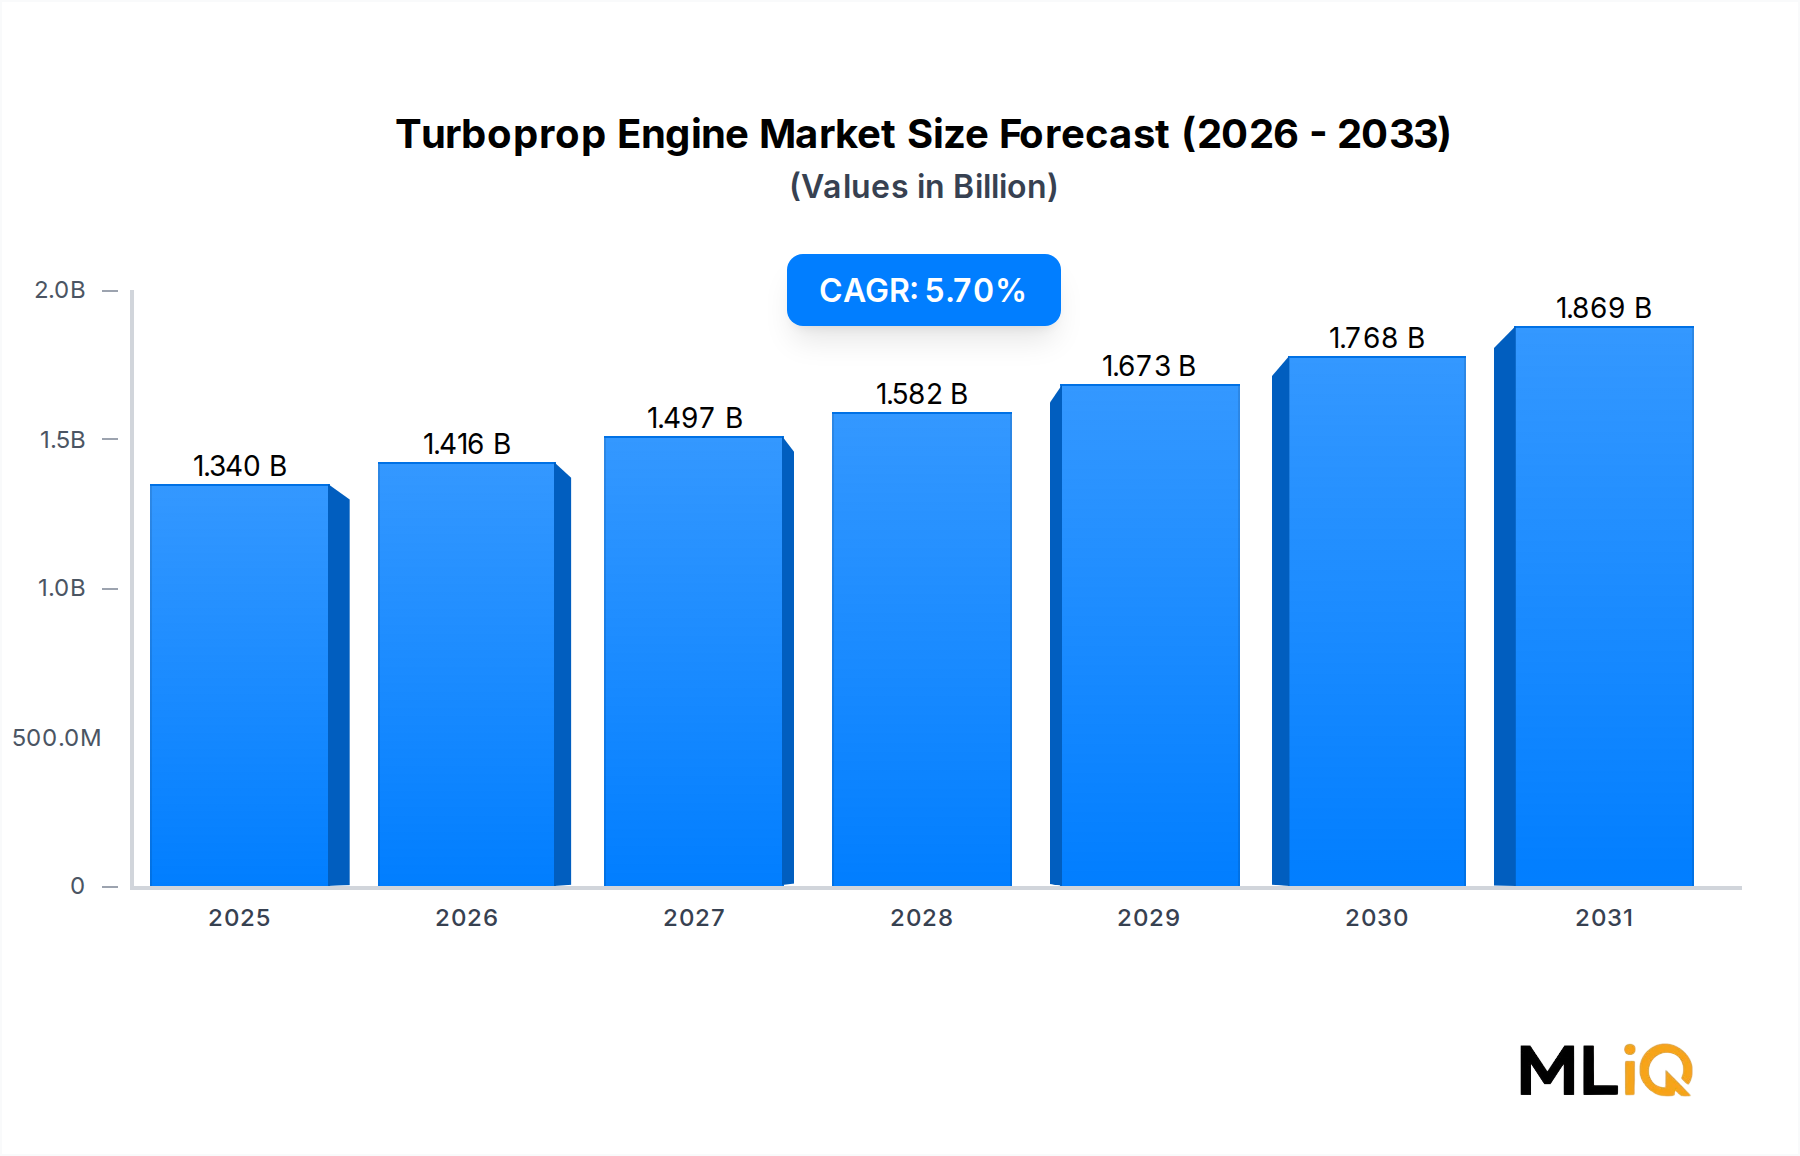
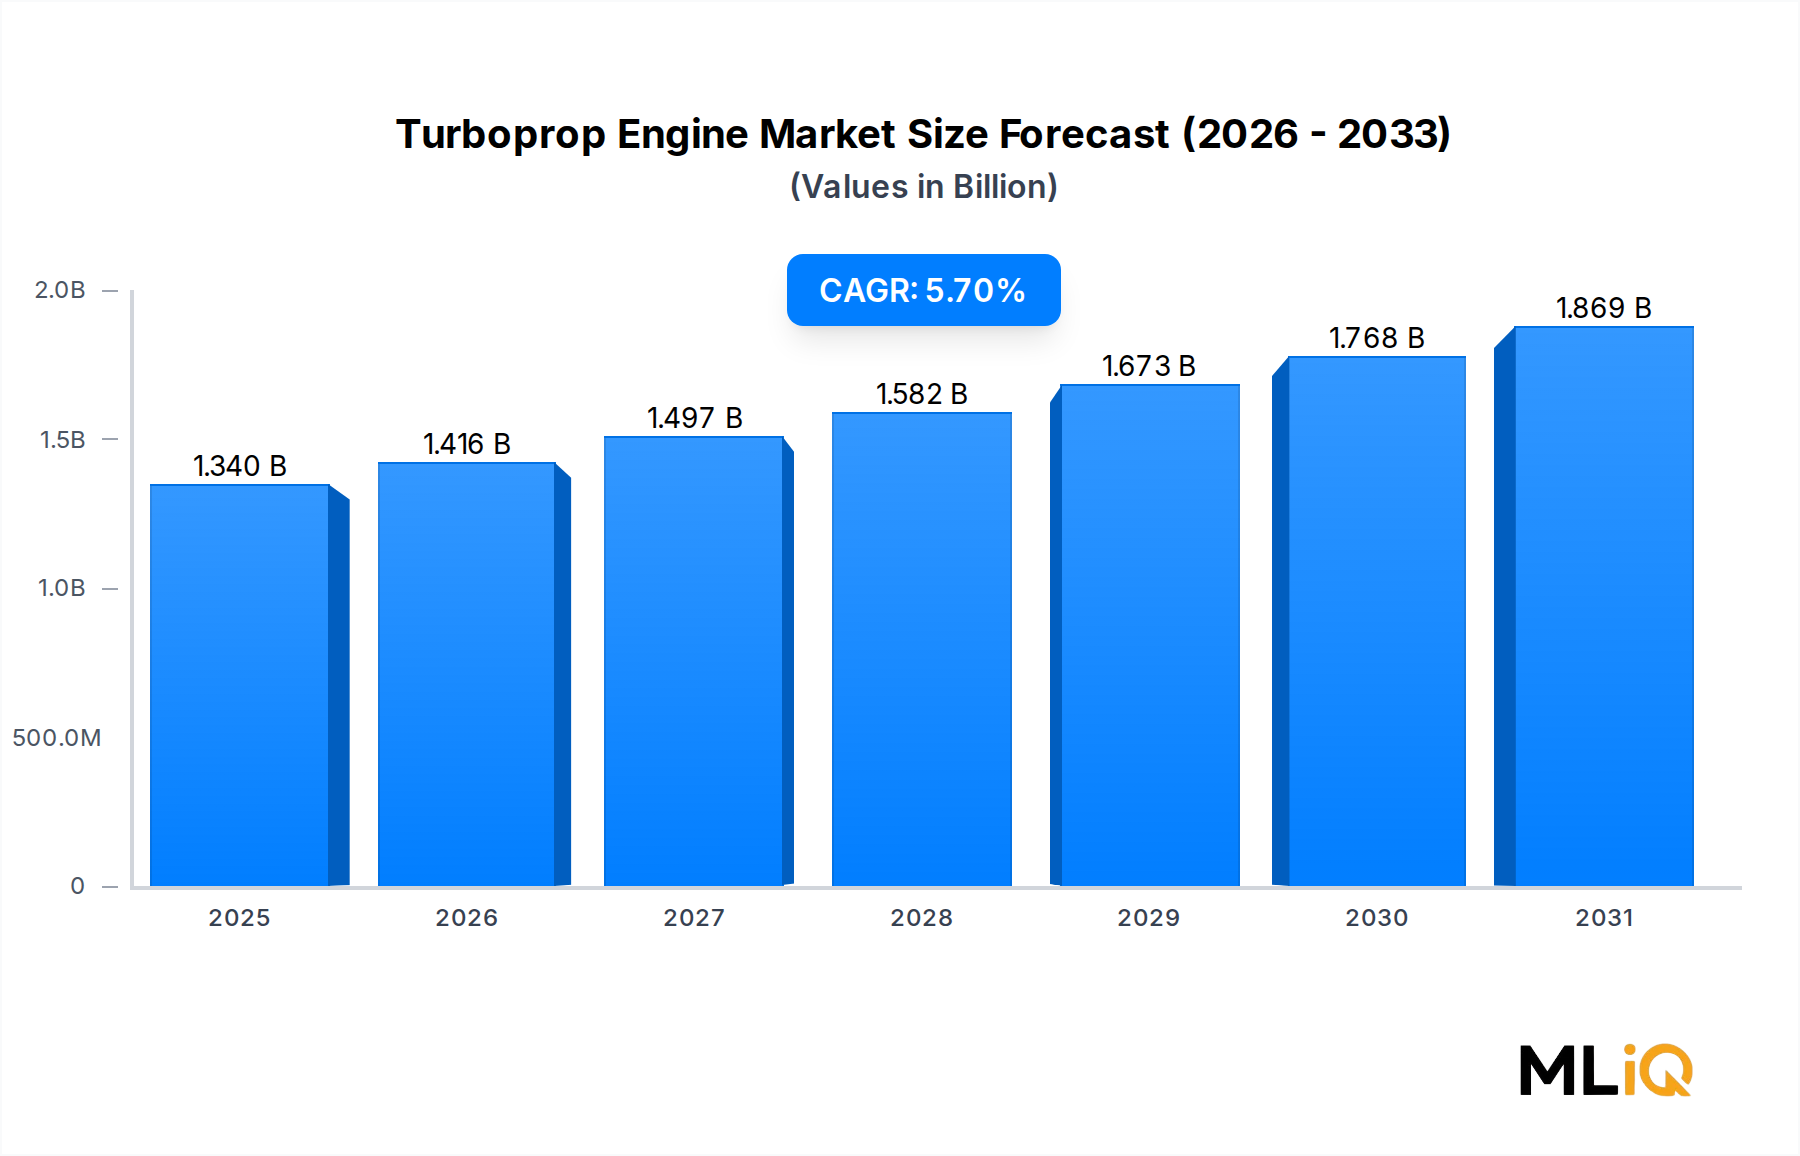
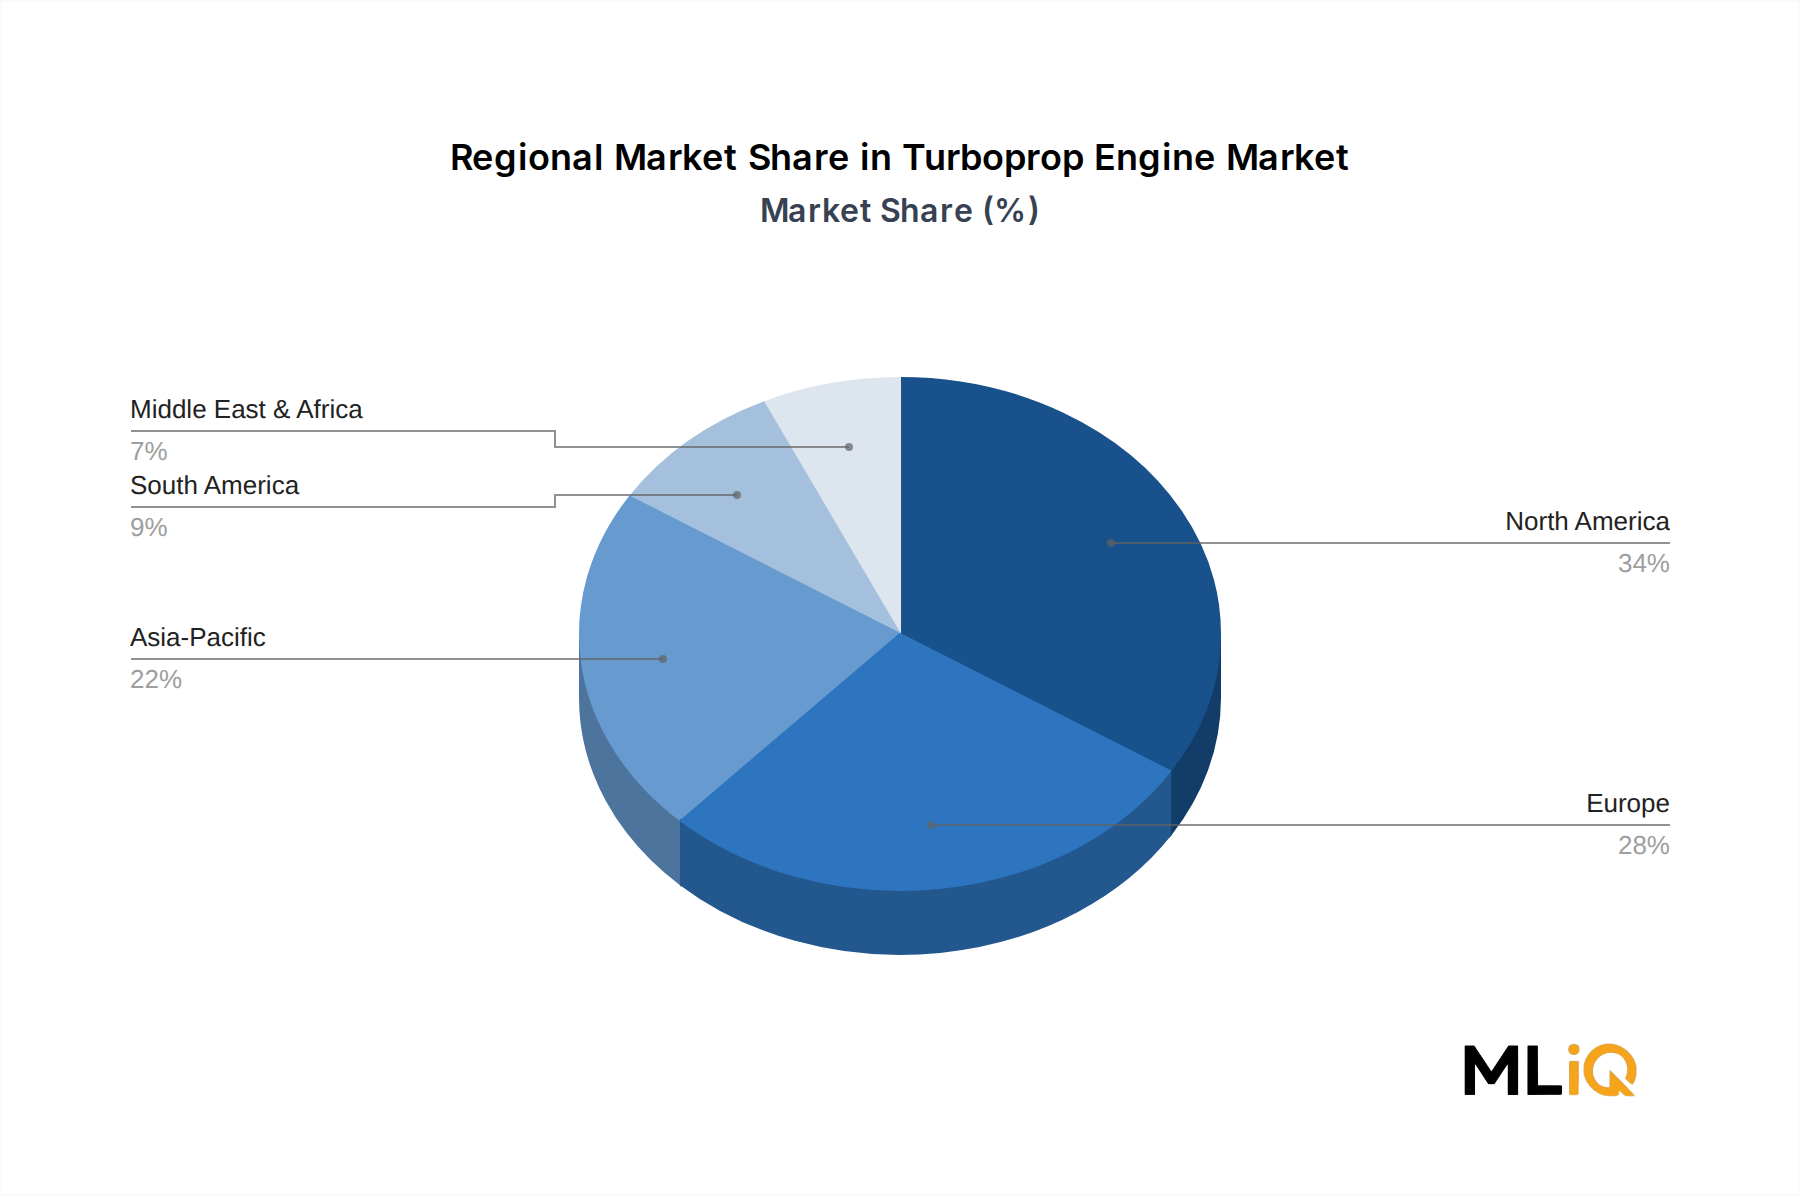
The Turboprop Engine Market is valued at $1.5 billion in 2025 and is forecast to reach $2.83 billion by 2033 at a 8.25% CAGR. Growth is supported by rising air passenger volumes, expansion of regional routes, and replacement demand in general aviation. Commercial aircraft remains the largest application, contributing 46% of revenue, while the General Aviation Aircraft Turboprop Engine Market is the fastest-growing subsegment at 9.1% CAGR. North America leads with 32% regional share, followed by Asia-Pacific at 27% and Europe at 24%.
Key demand signals include fleet modernization by regional carriers, military transport upgrades, and increasing use of portable electronic devices in cockpit operations. The Commercial Aircraft Turboprop Engine Market benefits from 50–70 seat regional aircraft, while the Military Aircraft Turboprop Engine Market is tied to airlift and maritime patrol platforms. Engine OEMs are prioritizing fuel burn reductions of 5–8% per generation and extending time-on-wing to 4,000–6,000 hours.
Supply chain dynamics remain mixed. Titanium and nickel superalloy availability improved in 2024, but specialized castings still face 12–18 week lead times. The Aircraft Engine MRO Market is expanding as operators seek predictive maintenance, with aftermarket services expected to grow at 7.4% CAGR through 2033. Strategic risks include certification delays, skilled labor shortages, and raw material price volatility.
For stakeholders across the Aerospace and Defense Market, the capital allocation priority is clear: fund next-generation engine architectures and digital aftermarket platforms. The Regional Turboprop Aircraft Market will absorb most near-term deliveries, but long-term upside depends on hybrid-electric and Sustainable Aviation Fuel Market compatibility. Overall, the market outlook is positive, with $1.33 billion in incremental value expected between 2025 and 2033.
Commercial aircraft: 46% share, driven by ATR 72, Dash 8, and C-130 replacements.
Military aircraft: 31% share, supported by transport and maritime patrol programs.
General aviation: 23% share, growing at 9.1% CAGR on private and charter demand.
Segment Deep-Dive: Commercial Aircraft Dominance in Turboprop Engine Market
Segment Analysis Matrix
Segment
Growth Rate (CAGR %)
Market Share (%)
Key Demand Driver
Commercial Aircraft
8.0%
46%
Regional airline fleet replacement
Military Aircraft
7.2%
31%
Airlift, patrol, and training upgrades
General Aviation Aircraft
9.1%
23%
Private and charter fleet modernization
Commercial Aircraft: Core Revenue Engine
The Commercial Aircraft Turboprop Engine Market generated approximately $690 million in 2025 and is projected to reach $1.28 billion by 2033. Demand centers on 50–70 seat regional aircraft used for short-haul routes where turboprops offer 25–40% lower fuel burn than comparable jets. ATR and De Havilland Canada dominate this airframe segment, with RTX Corporation's Pratt & Whitney Canada PW100 family holding a leading installed base. Margin pressure comes from long engine life cycles, which cap replacement volume and push OEMs toward aftermarket service contracts.
Commercial turboprop deliveries are forecast to average 320–360 units annually through 2030.
Aftermarket revenue for commercial turboprops is growing at 7.8% CAGR, faster than original equipment.
Fuel efficiency mandates in Europe and North America favor newer engines with 10–15% lower specific fuel consumption.
General Aviation: Fastest-Growing Application
The General Aviation Aircraft Turboprop Engine Market is set to expand at 9.1% CAGR, the highest among application segments. Private operators, fractional ownership fleets, and charter companies are replacing aging piston aircraft with turboprop platforms such as the Pilatus PC-12 and Cessna Denali. GE Aerospace's Catalyst engine and Honeywell's TPE331 upgrades target this segment with digital controls and 3–5% better fuel burn. The Aviation Propulsion Systems Market benefits as new turboprop designs integrate full-authority digital engine controls and health monitoring.
General aviation turboprop fleet exceeded 22,000 aircraft globally in 2025.
Replacement cycle averages 15–20 years, creating steady OEM demand.
Operator economics favor turboprops on routes under 500 nautical miles.
Military Aircraft: Steady Replacement Demand
The Military Aircraft Turboprop Engine Market represents 31% of revenue, supported by transport aircraft such as the C-130 Hercules, A400M, and maritime patrol platforms. Military budgets in the U.S., Europe, and Asia-Pacific fund engine upgrades for fuel efficiency and reduced acoustic signatures. Rolls-Royce plc's AE 2100 and T56 upgrades remain key programs, while TUSAS Engine Industries Inc develops indigenous turboprop power for Turkish platforms.
Military turboprop demand is less cyclical but subject to geopolitical budget shifts.
Upgrade programs can extend engine life by 20–30% at 40–50% of new engine cost.
Margin Pressures and Sub-Segment Dynamics
OEM gross margins in the 25–32% range face pressure from raw material costs, especially the Titanium Alloy Aerospace Market and nickel superalloys. Single-source castings and forgings add 5–10% to unit costs. Aftermarket margins stay higher at 35–45%, driving OEMs to bundle maintenance contracts. Sub-segment competition is intensifying as new entrants from China and India target light turboprop and UAV applications.
Primary Market Drivers & Growth Restraints in Turboprop Engine Market
Market Dynamics Impact Analysis
Factor Type
Description
Impact Level
Timeline
Driver
Increasing number of air passengers
High
Short term
Driver
Use of portable electronic devices and digital cockpit upgrades
Medium
Short term
Driver
Regional aircraft fleet replacement
High
Medium term
Driver
Military airlift and maritime patrol modernization
Medium
Long term
Restraint
High cost of connectivity equipment
High
Short term
Restraint
Supply chain bottlenecks for superalloy castings
Medium
Short term
Restraint
Stringent emissions and noise regulations
Medium
Long term
Rising air passenger traffic, particularly in Asia-Pacific and Latin America, directly supports regional turboprop demand. The General Aviation Aircraft Turboprop Engine Market benefits from portable electronic device integration, as modern cockpits require more electrical power and cooling. Fleet replacement cycles in North America and Europe add $420 million in cumulative engine demand through 2033.
Connectivity equipment costs remain a restraint. Upgrading a regional turboprop with satellite communications and in-flight Wi-Fi can cost $250,000–$500,000 per aircraft, limiting adoption among small operators. Supply chain bottlenecks for directionally solidified and single-crystal turbine blades extend lead times by 12–18 weeks, while emissions regulations in Europe push OEMs to invest in Sustainable Aviation Fuel Market compatibility.
Regulatory developments include FAA and EASA noise standards for new turboprop certifications and ICAO's carbon offsetting scheme. These rules raise compliance costs but also create replacement demand for older engines. The net impact is positive for OEMs with fuel-efficient portfolios, while MRO providers face margin pressure from longer maintenance intervals.
RTX Corporation: Pratt & Whitney Canada's PT6 family powers more than 60% of the global general aviation turboprop fleet. The company's aftermarket network covers 100+ service centers.
Rolls-Royce plc: The AE 2100 and T56 engine lines support military transport and maritime patrol aircraft. Rolls-Royce is testing 100% SAF compatibility on these engines.
Safran: Focuses on turboprop engine components, accessories, and MRO for military trainers. The company benefits from European defense spending increases.
General Electric Company: The Catalyst engine targets the Cessna Denali and similar platforms with a 10% fuel burn advantage over legacy engines.
Honeywell International Inc: TPE331 engines serve utility, cargo, and agricultural aircraft. Honeywell's installed base exceeds 8,000 engines globally.
MTU Aero Engines AG: Supplies modules and components for turboprop programs and offers independent MRO services.
PBS AEROSPACE Inc: Provides small turboprop engines for UAVs and light aircraft, with a focus on cost-sensitive markets.
Motor Sich JSC: Legacy turboprop and turboshaft engines for Eastern European transport aircraft. Geopolitical factors constrain export growth.
TUSAS Engine Industries Inc: Developing indigenous turboprop engines for Turkish military and regional aircraft, reducing import dependence.
Strategic Milestones & Recent Developments in Turboprop Engine Market
Latest Strategic Moves
Date
Company
Event Type
Impact
2023
RTX Corporation
Facility expansion
Increased PT6 MRO capacity by 20%
2024
Rolls-Royce plc
SAF test
Validated 100% SAF on AE 2100 engine
2024
GE Aerospace
Certification milestone
Catalyst engine advanced toward FAA certification
2024
Honeywell International Inc
Product upgrade
TPE331-14GR improved fuel burn by 3%
2025
Safran
Partnership
Hybrid-electric turboprop demonstrator announced
2023: RTX Corporation expanded its Pratt & Whitney Canada engine overhaul facility to reduce turnaround times for PT6 operators.
2024: Rolls-Royce plc completed ground tests of the AE 2100 using 100% sustainable aviation fuel, supporting military decarbonization goals.
2024: GE Aerospace moved the Catalyst engine closer to certification, targeting the general aviation turboprop segment with digital engine controls.
2024: Honeywell International Inc introduced the TPE331-14GR upgrade, offering better fuel efficiency and longer time-on-wing.
2025: Safran announced a partnership to develop hybrid-electric turboprop propulsion for regional aircraft, aligning with the Aviation Propulsion Systems Market shift toward electrification.
Regional Market Analysis & Growth Corridors for Turboprop Engine Market
Regional Growth Comparison
Region
Projected CAGR (%)
Base Year Valuation
Primary Catalyst
Regulatory Stringency
North America
7.4%
$0.48B
General aviation and military fleets
High
Europe
7.9%
$0.36B
Regional connectivity and SAF mandates
High
Asia-Pacific
9.6%
$0.41B
Fleet expansion and MRO localization
Medium
South America
8.1%
$0.10B
Agricultural and regional aviation
Medium
Middle East & Africa
8.7%
$0.15B
Military airlift and cargo demand
Low-Medium
North America is the most mature market, with 32% of global revenue and a large installed base of PT6 and TPE331 engines. The U.S. accounts for over 60% of regional demand, driven by general aviation, regional airlines, and military transport. Canada contributes OEM design and testing capacity through Pratt & Whitney Canada.
Europe is the second-largest region at 24% share. The European Union's SAF blending mandates and noise regulations accelerate replacement of older turboprops. The Regional Turboprop Aircraft Market in Europe benefits from point-to-point connectivity to secondary airports.
Asia-Pacific is the fastest-growing region at 9.6% CAGR, supported by fleet expansion in China, India, and Southeast Asia. Local MRO providers are expanding capacity for the Aircraft Engine MRO Market, reducing reliance on North American service centers. China's domestic turboprop programs and India's regional connectivity scheme add volume.
South America and Middle East & Africa together represent 17% of the market. South America's agricultural and regional operators drive demand for utility turboprops, while Middle East & Africa demand is tied to military airlift and cargo operations. Regulatory stringency is lower in these regions, but infrastructure and financing constraints limit faster adoption.
Export, Cross-Border Trade & Tariff Impact on Turboprop Engine Market
Major trade corridors for turboprop engines and components run from Canada and the United States to Europe, Asia-Pacific, and Latin America. Canada is a net exporter of complete turboprop engines, led by Pratt & Whitney Canada, while the United States exports engine components, avionics, and MRO services. France and the United Kingdom export turbine modules, forgings, and control systems. China and Russia are net importers of high-end turboprop technology, though both fund domestic alternatives.
Trade Flow
Key Countries
Product Focus
Tariff/Barrier Risk
North America to Europe
U.S., Canada to France, Germany, U.K.
Engines, MRO, avionics
Low-to-medium
Europe to Asia-Pacific
France, U.K. to China, India, Japan
Modules, forgings, controls
Medium
North America to Latin America
U.S., Canada to Brazil, Mexico
Complete engines, parts
Low
Asia-Pacific intra-region
Japan, South Korea to ASEAN
Components, MRO
Medium
Tariffs on titanium and nickel alloys can raise engine costs by 2–4%. Export controls on advanced propulsion technology affect China and Russia, pushing them toward indigenous programs. Non-tariff barriers include FAA and EASA certification requirements, which add 12–24 months to market entry. The Titanium Alloy Aerospace Market is directly exposed to trade policy shifts, as Russia was a significant titanium supplier before 2022.
Cross-border MRO activity is growing as operators seek lower-cost service locations. Mexico, Singapore, and the United Arab Emirates have expanded turboprop MRO capacity to serve North American and European fleets. These shifts reduce downtime but require careful management of export licensing and parts traceability.
Sustainability, ESG & Decarbonization Pressures on Turboprop Engine Market
Environmental regulations and net-zero targets are reshaping the Turboprop Engine Market. The European Union's ReFuelEU Aviation initiative requires 6% SAF blending by 2030, rising to 70% by 2050. The Sustainable Aviation Fuel Market is expanding as OEMs certify engines for 100% SAF, including Rolls-Royce's AE 2100 and Honeywell's TPE331. Turboprops already offer lower fuel burn than jets on short routes, but ESG investors demand measurable reductions in lifecycle emissions.
Circular economy mandates affect raw material selection. Engine manufacturers are increasing use of recycled titanium and nickel alloys, while the Titanium Alloy Aerospace Market faces pressure to document carbon footprints. MRO providers are adopting component repair and remanufacturing to extend engine life by 20–30%. These practices reduce waste but require new investment in inspection and coating technologies.
ESG criteria also influence procurement. Airlines and lessors now include fuel efficiency, noise, and emissions metrics in engine selection. Manufacturers that offer SAF-compatible engines and transparent supply chains are better positioned for contracts. The General Aviation Aircraft Turboprop Engine Market will see gradual adoption of hybrid-electric designs, with first commercial applications expected after 2030. Overall, decarbonization adds compliance costs but creates differentiation opportunities for OEMs and MRO providers.
Turboprop Engine Market Segmentation
1. Application
1.1. Commercial Aircraft
1.2. Military Aircraft
1.3. General Aviation Aircraft
Turboprop Engine Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Turboprop Engine Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 8.25% from 2020-2034
Segmentation
By Application
Commercial Aircraft
Military Aircraft
General Aviation Aircraft
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Application
5.1.1. Commercial Aircraft
5.1.2. Military Aircraft
5.1.3. General Aviation Aircraft
5.2. Market Analysis, Insights and Forecast - by Region
5.2.1. North America
5.2.2. South America
5.2.3. Europe
5.2.4. Middle East & Africa
5.2.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Application
6.1.1. Commercial Aircraft
6.1.2. Military Aircraft
6.1.3. General Aviation Aircraft
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Application
7.1.1. Commercial Aircraft
7.1.2. Military Aircraft
7.1.3. General Aviation Aircraft
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Application
8.1.1. Commercial Aircraft
8.1.2. Military Aircraft
8.1.3. General Aviation Aircraft
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Application
9.1.1. Commercial Aircraft
9.1.2. Military Aircraft
9.1.3. General Aviation Aircraft
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Application
10.1.1. Commercial Aircraft
10.1.2. Military Aircraft
10.1.3. General Aviation Aircraft
11. Competitive Analysis
11.1. Company Profiles
11.1.1. RTX Corporation
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Rolls-Royce plc
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Safran
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. General Electric Company
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Honeywell International Inc
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. MTU Aero Engines AG
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. PBS AEROSPACE Inc
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Motor Sich JSC
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. TUSAS Engine Industries Inc
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Turboprop Engine Market Revenue Breakdown (billion, %) by Region 2026 & 2034
Figure 2: North America Turboprop Engine Market Revenue (billion), by Application 2026 & 2034
Figure 3: North America Turboprop Engine Market Revenue Share (%), by Application 2026 & 2034
Figure 4: North America Turboprop Engine Market Revenue (billion), by Country 2026 & 2034
Figure 5: North America Turboprop Engine Market Revenue Share (%), by Country 2026 & 2034
Figure 6: South America Turboprop Engine Market Revenue (billion), by Application 2026 & 2034
Figure 7: South America Turboprop Engine Market Revenue Share (%), by Application 2026 & 2034
Figure 8: South America Turboprop Engine Market Revenue (billion), by Country 2026 & 2034
Figure 9: South America Turboprop Engine Market Revenue Share (%), by Country 2026 & 2034
Figure 10: Europe Turboprop Engine Market Revenue (billion), by Application 2026 & 2034
Figure 11: Europe Turboprop Engine Market Revenue Share (%), by Application 2026 & 2034
Figure 12: Europe Turboprop Engine Market Revenue (billion), by Country 2026 & 2034
Figure 13: Europe Turboprop Engine Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Middle East & Africa Turboprop Engine Market Revenue (billion), by Application 2026 & 2034
Figure 15: Middle East & Africa Turboprop Engine Market Revenue Share (%), by Application 2026 & 2034
Figure 16: Middle East & Africa Turboprop Engine Market Revenue (billion), by Country 2026 & 2034
Figure 17: Middle East & Africa Turboprop Engine Market Revenue Share (%), by Country 2026 & 2034
Figure 18: Asia Pacific Turboprop Engine Market Revenue (billion), by Application 2026 & 2034
Figure 19: Asia Pacific Turboprop Engine Market Revenue Share (%), by Application 2026 & 2034
Figure 20: Asia Pacific Turboprop Engine Market Revenue (billion), by Country 2026 & 2034
Figure 21: Asia Pacific Turboprop Engine Market Revenue Share (%), by Country 2026 & 2034
Table 40: Rest of Asia Pacific Turboprop Engine Market Revenue (billion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
70–80% of research inputs are gathered through primary interviews, surveys, and direct data exchanges with turboprop engine OEMs, MRO providers, and component suppliers.
We conduct semi-structured interviews with turboprop engine program directors, aftermarket service managers, and propulsion engineers across North America, Europe, and Asia-Pacific.
Company types interviewed: turboprop engine OEMs; propeller and nacelle system integrators; aircraft engine MRO providers; avionics and full-authority digital engine control suppliers; aerospace alloy and forging distributors.
Stakeholder titles interviewed: Director of Turboprop Engine Programs; VP of Aftermarket and MRO Services; Chief Propulsion Engineer; Procurement Director for Aerospace Alloys; Airline Fleet Planning Manager.
Industry associations and regulatory bodies consulted: Federal Aviation Administration (FAA), European Union Aviation Safety Agency (EASA), General Aviation Manufacturers Association (GAMA), Aerospace Industries Association (AIA).
Primary research is refreshed continuously, and every report is updated to the date of purchase.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Director of Turboprop Engine Programs
30%
VP of Aftermarket and MRO Services
25%
Chief Propulsion Engineer
20%
Procurement Director for Aerospace Alloys
15%
Airline Fleet Planning Manager
10%
Industry Ecosystem Breakdown
Company Type
Representation (%)
Turboprop Engine OEMs
35%
Propeller & Nacelle Integrators
15%
MRO & Aftermarket Service Providers
20%
Avionics & Control System Suppliers
12%
Aerospace Alloy & Component Distributors
10%
Certification & Testing Labs
8%
Secondary Research & Industry Benchmarking
20–30% of data comes from secondary sources, including company annual reports, FAA and EASA airworthiness directives, and trade association publications.
Standard financial databases include Bloomberg, Factiva, Hoovers, and PitchBook. We also use .gov sources such as FAA.gov and EASA.europa.eu, .org sources such as GAMA.aero and AIA-Aerospace.org, and trade association data from the International Air Transport Association (IATA).
We avoid market research websites and rely on primary regulatory filings, OEM technical documents, and government trade statistics.
All secondary data is triangulated with primary interview findings before inclusion in the final forecast.
Demand Modeling & Market Estimation
We use top-down and bottom-up methodologies simultaneously, validated through multi-level data triangulation.
Bottom-up quantitative metrics include annual turboprop engine deliveries by platform, average engine flight hours before overhaul, regional turboprop fleet size, average selling price per turboprop engine, and fuel burn improvement rates by engine generation.
Top-down inputs include global aerospace and defense spending, regional airline capacity growth, general aviation fleet renewal rates, and military transport modernization budgets.
Segment and regional splits are cross-checked against OEM revenue disclosures, MRO contract values, and import-export data for engine parts.
The resulting estimated data accuracy level is 85–90%, with confidence intervals applied to emerging segments such as hybrid-electric turboprops.
Data Accuracy & Quality Check
All quantitative inputs undergo multi-level data triangulation using at least three independent sources.
Interviews are transcribed, coded, and checked for consistency before inclusion in demand models.
Forecast assumptions are stress-tested against fuel price scenarios, regulatory timelines, and supply chain lead times.
Reports are updated to the date of purchase, ensuring that the latest certification events, M&A activity, and trade policy changes are reflected.
Final estimates are reviewed by senior analysts with aerospace and defense specialization before publication.
Frequently Asked Questions
1. What are the key segments of the Turboprop Engine Market?
The market splits by application into commercial aircraft, military aircraft, and general aviation aircraft. Commercial aircraft holds roughly 46% revenue share in 2025, while general aviation is forecast to grow at a 9.1% CAGR through 2033. Military aircraft demand remains tied to transport and surveillance platforms like the C-130 and A400M.
2. Which region dominates the Turboprop Engine Market and why?
North America leads with about 32% share in 2025, supported by RTX Corporation's Pratt & Whitney Canada PT6 family and a dense MRO network. The U.S. alone accounts for over 60% of regional aftermarket spend due to large general aviation and regional airline fleets. Canada adds OEM design and testing capacity for turboprop platforms.
3. How are raw material sourcing and supply chains structured in the Turboprop Engine Market?
Critical inputs include titanium alloys, nickel-based superalloys, and carbon-fiber composites, with forgings often sourced from Europe and North America. Single-source constraints for certain turbine blades can extend lead times by 12–18 weeks. OEMs are qualifying additional suppliers in India and Japan to reduce concentration risk.
4. What are the major challenges and restraints in the Turboprop Engine Market?
High connectivity equipment costs and long certification cycles restrain retrofit adoption, especially in general aviation. Supply chain bottlenecks for specialized castings and bearings can add 5–10% to engine unit costs. Skilled labor shortages in MRO shops also limit aftermarket capacity growth.
5. How has the Turboprop Engine Market recovered after the pandemic?
After a 2020 decline of roughly 18% in engine deliveries, the market recovered to 2019 levels by 2023. Structural shifts include more regional point-to-point routes and increased military airlift demand. Long-term demand now favors fuel-efficient engines and digital maintenance tracking.
6. How are purchasing trends and operator behavior changing in the Turboprop Engine Market?
Operators increasingly prefer engines with lower fuel burn and longer time-on-wing, such as the PT6 E-Series and Catalyst. Purchasing decisions now weigh predictive maintenance and SAF compatibility alongside acquisition price. Fleet managers are also consolidating vendors to reduce total cost of ownership.