Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Target Acquisition Systems Market to Reach $22.8B by 2033
Target Acquisition Systems Market
Target Acquisition Systems Market to Reach $22.8B by 2033
Target Acquisition Systems Market by Platform (Land, Airborne, Naval), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 22, 2026|Base Year : 2025|Pages : 234
Key Insights & Executive Summary: Target Acquisition Systems Market
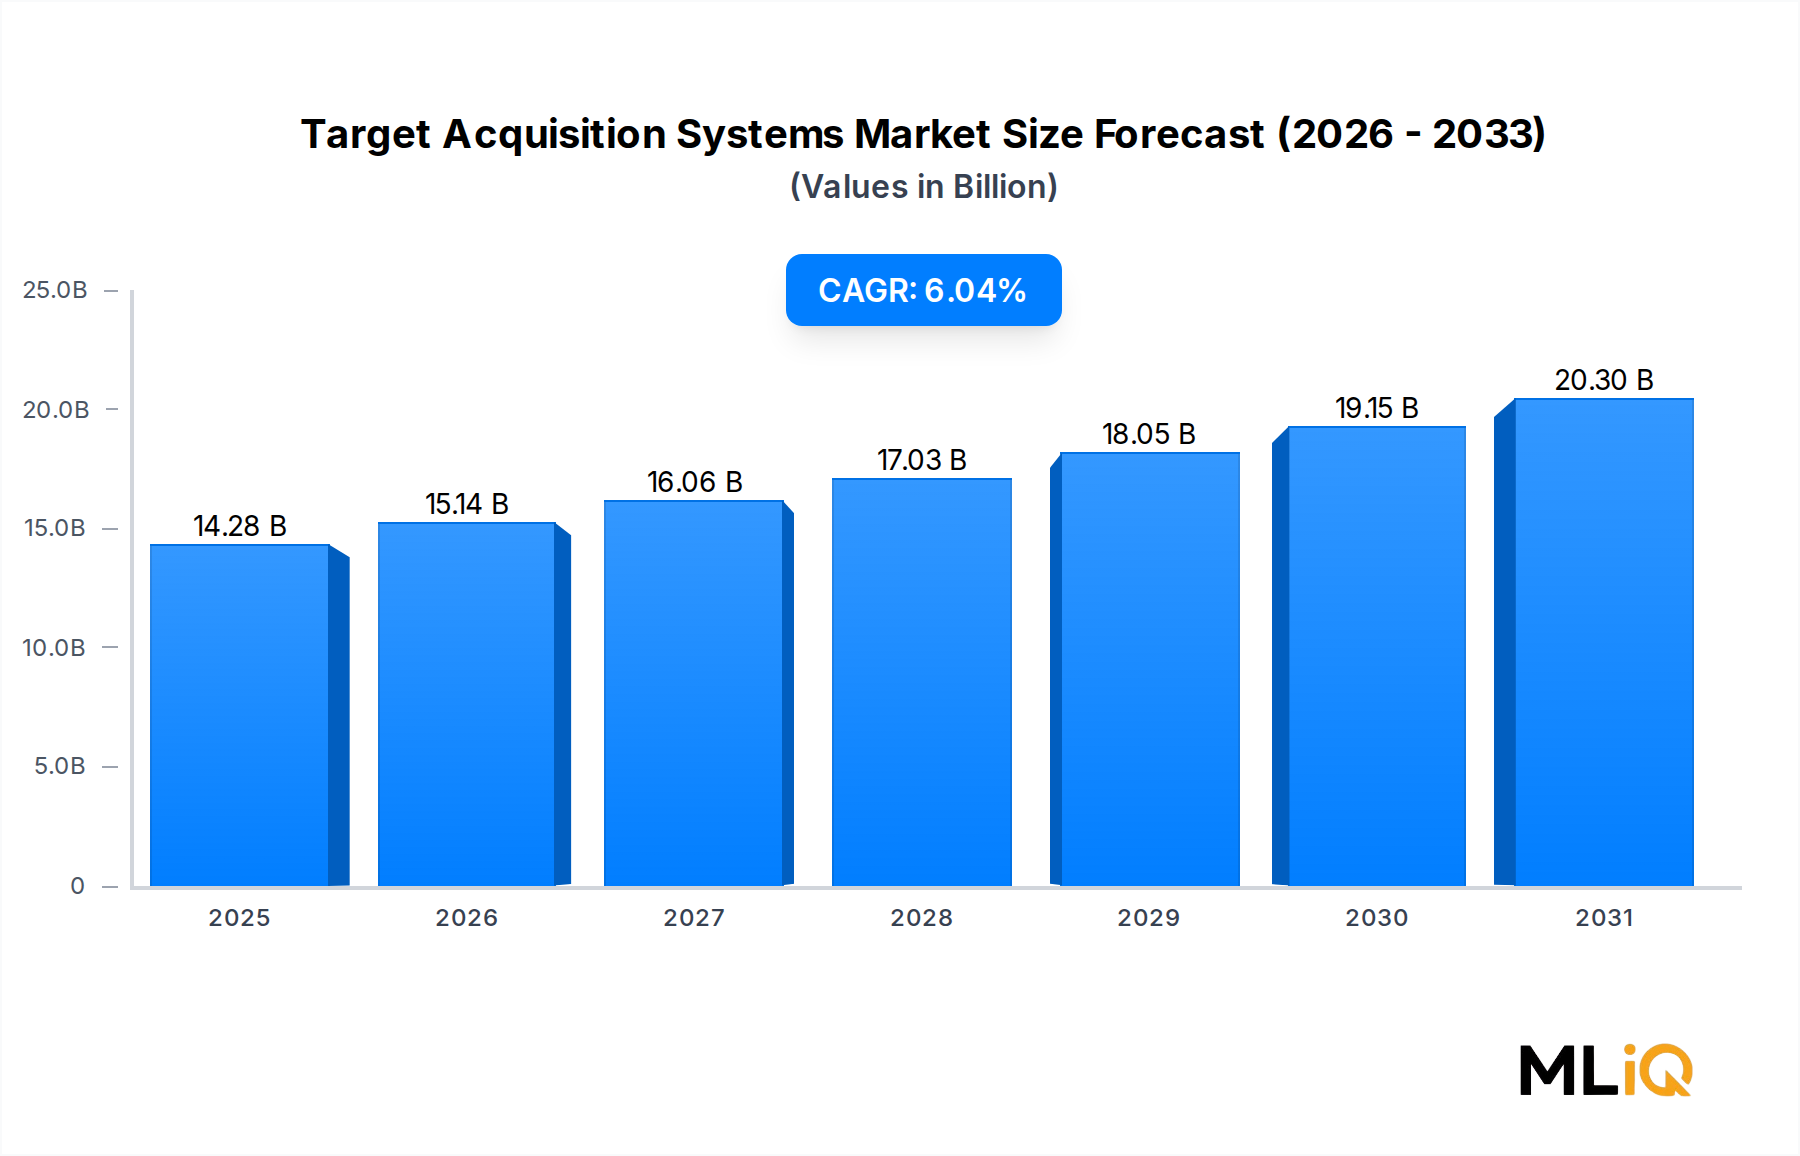
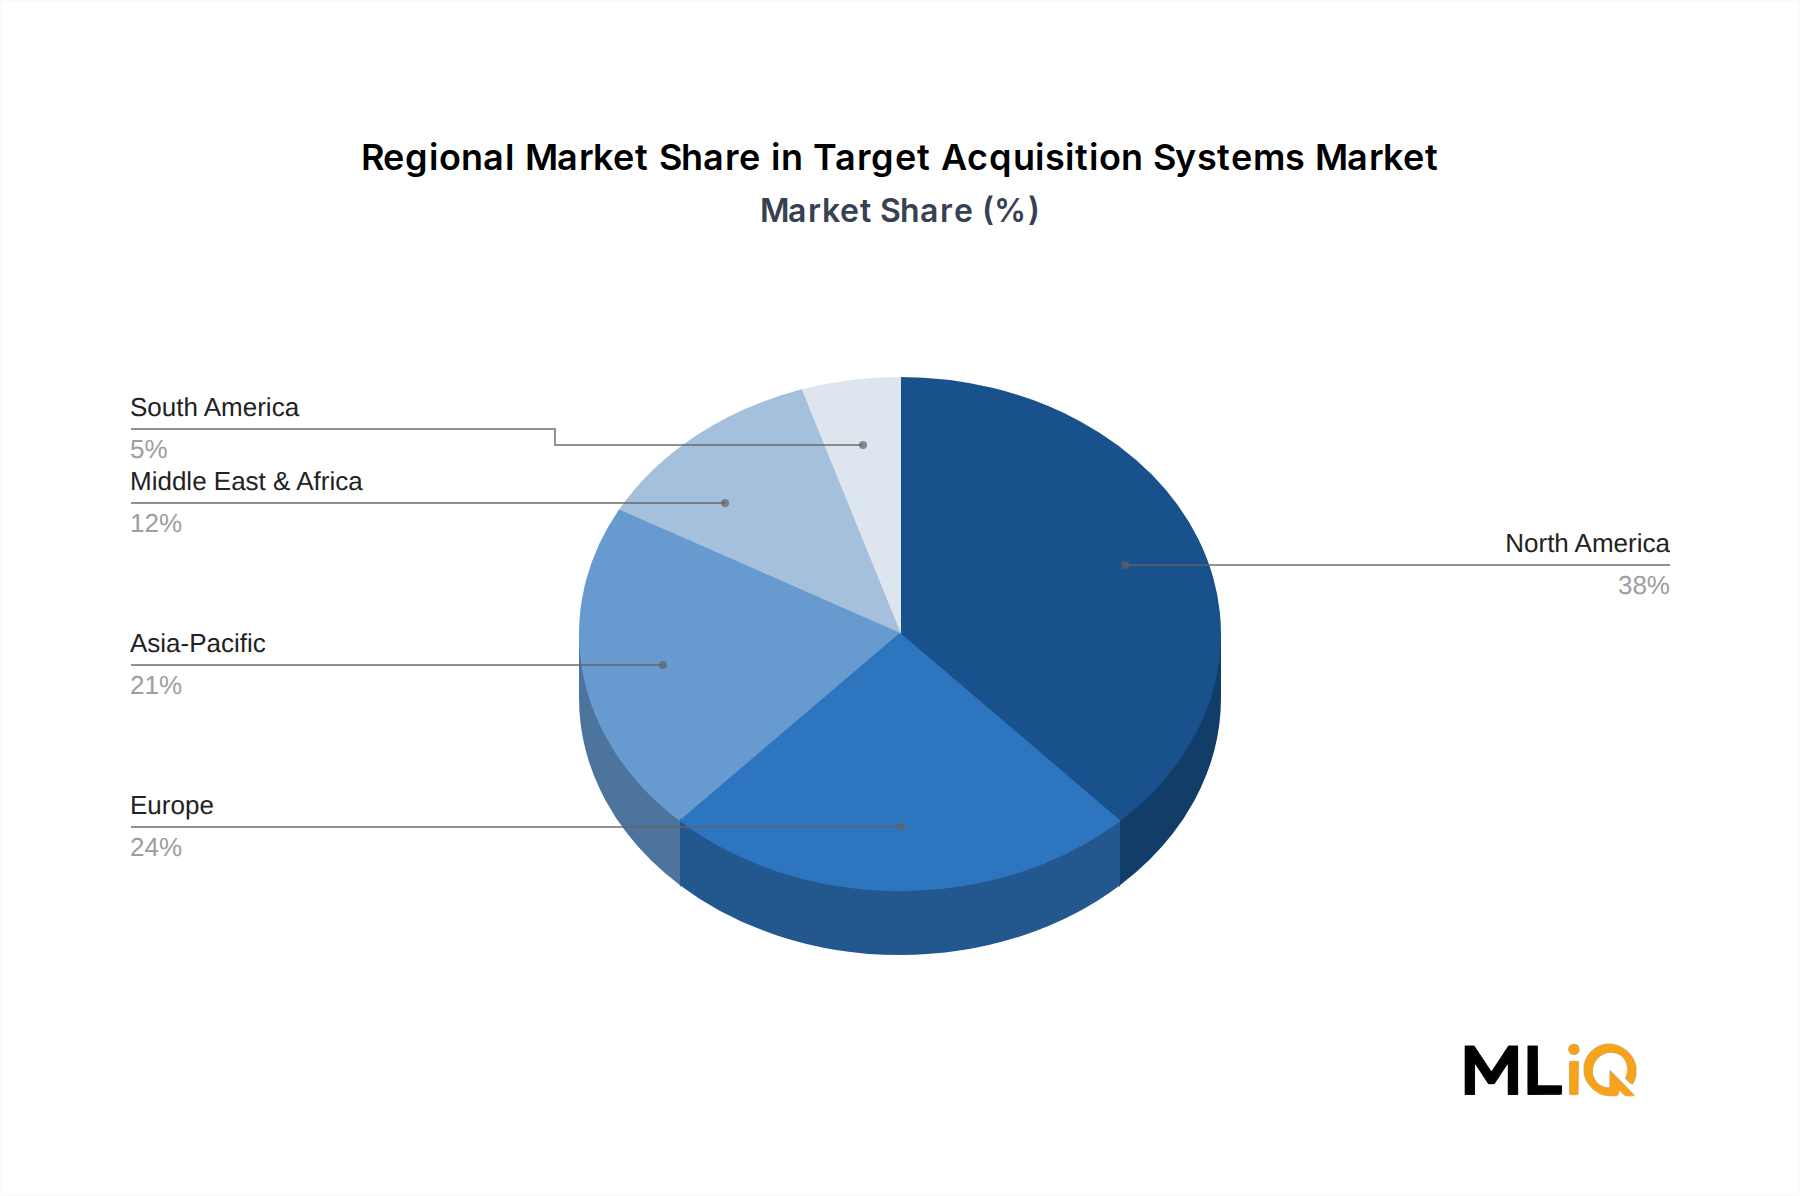
The Target Acquisition Systems Market is projected to grow from $14.28 billion in 2025 to $22.8 billion by 2033, at a CAGR of 6.04%. This expansion is fueled by rising defense budgets, modernization programs, and technological advancements in sensors and AI. North America leads with a 35% share, followed by Europe and Asia-Pacific. The Land segment dominates, accounting for over 45% of revenue. Key players include Lockheed Martin, Raytheon, Thales, and Elbit Systems. The Land Target Acquisition Systems Market benefits from infantry modernization, while the Airborne Target Acquisition Systems Market is driven by UAV payloads and fighter jet upgrades. The Naval Target Acquisition Systems Market remains stable due to maritime surveillance needs. The broader Military Targeting Systems Market is integrating AI for enhanced precision. Adjacent Defense Electronics Market growth is supported by advancements in radar and thermal imaging. The Thermal Imaging Market and Radar Systems Market are expanding, with the Rare Earth Materials Market facing supply constraints. The Lidar Systems Market is emerging as a key enabler for autonomous targeting. However, high R&D costs and export controls restrain growth. The market is characterized by long procurement cycles and stringent regulatory requirements. Geopolitical tensions in Eastern Europe and the Middle East have accelerated demand for target acquisition systems. The U.S. DoD budget for 2025 allocated $850 billion, with a significant portion for advanced targeting. Europe's NATO members are increasing defense spending to 2% of GDP. Asia-Pacific is the fastest-growing region at 7.8% CAGR, driven by China and India. The market is fragmented, with top five vendors holding 40% share. Innovation focuses on multi-sensor fusion, AI-enabled target recognition, and network-centric warfare. Challenges include supply chain disruptions for rare earth elements and semiconductors. The forecast period 2026-2034 anticipates steady growth, with opportunities in emerging markets and retrofit programs.
Target Acquisition Systems Market Size (In Billion)
25.0B
20.0B
15.0B
10.0B
5.0B
0
14.28 B
2025
15.14 B
2026
16.06 B
2027
17.03 B
2028
18.05 B
2029
19.15 B
2030
20.30 B
2031
Segment Deep-Dive: Land Dominance in Target Acquisition Systems Market
Segment
CAGR (2025-2033)
Market Share (2025)
Key Demand Driver
Land
5.8%
46%
Infantry modernization, artillery targeting
Airborne
6.5%
32%
Fighter jet upgrades, UAV payloads
Naval
6.0%
22%
Maritime surveillance, AEGIS systems
The Land segment held the largest market share in 2024 and continues to dominate, with 46% of total revenue. This segment includes target acquisition systems for tanks, artillery, and infantry soldiers. Growth is driven by conflicts in Ukraine and the Middle East, which have highlighted the need for precision targeting. The Airborne Target Acquisition Systems Market is the fastest-growing at 6.5% CAGR, fueled by increased use of unmanned aerial vehicles (UAVs) and fighter jet modernization programs. The Naval Target Acquisition Systems Market grows steadily at 6.0%, supported by naval fleet expansions and maritime security requirements.
Land Segment Dynamics
Dominated by systems like fire control radars and thermal sights.
Demand from main battle tanks (e.g., Abrams, Leopard 2) and artillery.
Margin pressures from raw material costs and competition from low-cost suppliers.
Growth driven by UAVs (e.g., Predator, Bayraktar) and fifth-generation fighters.
Requires lightweight, high-performance sensors.
Higher R&D costs but premium pricing.
Key vendors: Thales, Leonardo, Hensoldt.
Naval Segment Dynamics
Stable demand from navies worldwide, especially in Asia-Pacific.
Integration with AEGIS and other combat systems.
Long procurement cycles and high barriers to entry.
Key vendors: Raytheon, Thales, Aselsan.
The Land Target Acquisition Systems Market remains the largest, but the Airborne segment offers higher growth potential. The Naval Target Acquisition Systems Market is less volatile but competitive.
Primary Market Drivers & Growth Restraints in Target Acquisition Systems Market
Factor Type
Description
Impact Level
Timeline
Driver
Rising defense budgets globally
High
Short term
Driver
Technological advancements in AI and sensors
High
Long term
Driver
Geopolitical tensions and conflicts
High
Short term
Restraint
Stringent export controls (ITAR)
Medium
Long term
Restraint
High R&D costs
Medium
Short term
Restraint
Supply chain disruptions for rare earths
High
Short term
The market is propelled by increasing defense budgets, with global military spending reaching $2.2 trillion in 2024. The U.S., China, and India are significantly increasing their procurement of target acquisition systems. Technological advancements, such as AI-enabled target recognition and multi-sensor fusion, are enhancing system capabilities. Geopolitical tensions in Ukraine, Gaza, and the South China Sea are immediate drivers. However, stringent export controls, particularly ITAR in the U.S. and similar regulations in Europe, restrict market access and slow cross-border trade. High R&D costs and long development cycles create barriers for new entrants. Supply chain disruptions, especially for rare earth elements and semiconductors, pose risks. The Rare Earth Materials Market is tightly controlled by China, impacting production. The Defense Electronics Market faces similar constraints. The impact of these factors varies by region. In North America, drivers outweigh restraints, while in Asia-Pacific, supply chain issues are more pronounced. The forecast period 2026-2034 expects continued budget growth. Restraints are expected to ease with diversification efforts.
Competitive Ecosystem & Key Vendor Profiles: Target Acquisition Systems Market
Company Name
Core Strength
Target Audience
Market Position
Lockheed Martin
Advanced fire control systems
U.S. DoD, allies
Leader
Raytheon Technologies
Missile seekers and radar
Global militaries
Leader
Thales Group
Optronics and thermal imaging
European defense
Leader
Elbit Systems
Unmanned systems targeting
Israel and export
Challenger
Aselsan
Cost-effective land systems
Turkey and Middle East
Niche
Lockheed Martin Corporation: A dominant player with a broad portfolio of targeting systems for air, land, and sea. Its sniper pods and fire control radars are widely used by NATO forces.
Raytheon Technologies Corporation: Specializes in missile seekers and advanced radar systems. Its products are integral to U.S. and allied defense networks.
Thales Group: Provides optronic and thermal imaging systems for European and export markets. Strong in naval and airborne applications.
Elbit Systems Ltd: Focuses on unmanned systems and soldier-borne targeting. Competes globally with cost-effective solutions.
Aselsan AS: A Turkish defense electronics firm offering land-based targeting systems. Significant in the Middle East and Central Asia.
Leonardo SpA: Italian conglomerate with expertise in electro-optical systems. Supplies to European and global customers.
Rheinmetall AG: German firm known for armored vehicle targeting systems. Benefits from European rearmament.
The competitive landscape is moderately concentrated, with top five firms holding approximately 40% market share. Mergers and acquisitions are frequent as companies seek to acquire AI and sensor technologies. The Military Targeting Systems Market sees collaboration between primes and tech startups. The Thermal Imaging Market is dominated by Thales, Leonardo, and FLIR (Teledyne). The Radar Systems Market includes Raytheon, Lockheed Martin, and Hensoldt. The Lidar Systems Market is emerging, with players like Luminar and Hesai targeting defense applications.
Strategic Milestones & Recent Developments in Target Acquisition Systems Market
Date
Company
Event Type
Impact
2024 Q1
Lockheed Martin
Launch
New targeting pod for F-35
2024 Q2
Elbit Systems
Partnership
Joint venture with Indian firm
2024 Q3
Thales
M&A
Acquired AI startup for sensor fusion
2025 Q1
Raytheon
Contract
$500M award for missile seekers
In Q1 2024, Lockheed Martin launched the AN/AAQ-48 targeting pod, enhancing F-35 precision strike capabilities.
Elbit Systems formed a joint venture with India's Bharat Forge to produce targeting systems locally, aligning with 'Make in India'.
Thales acquired AI startup Neurala for $200 million to integrate AI-driven target recognition.
Raytheon secured a $500 million contract from the U.S. Army for advanced missile seekers.
In Q4 2024, Aselsan signed a deal with Saudi Arabia for land-based targeting systems worth $300 million.
Rheinmetall expanded its production capacity in Germany to meet NATO demand.
In 2025, Leonardo announced a partnership with Leonardo DRS to develop next-gen thermal sights.
These developments indicate a trend toward AI integration and local production. The market is also seeing increased collaboration between primes and tech firms.
Regional Market Analysis & Growth Corridors for Target Acquisition Systems Market
Region
Projected CAGR (%)
Base Year Valuation
Primary Catalyst
Regulatory Stringency
North America
5.5%
$5.0 billion
U.S. defense budget
High
Europe
6.0%
$4.0 billion
NATO modernization
High
Asia-Pacific
7.8%
$2.9 billion
China, India upgrades
Medium
LAMEA
6.5%
$2.4 billion
Middle East conflicts
Low
North America remains the largest market, valued at $5.0 billion in 2025, with a projected CAGR of 5.5%. The U.S. accounts for over 80% of regional revenue, driven by massive defense spending. Europe follows with $4.0 billion, growing at 6.0% due to NATO's rearmament initiatives. Asia-Pacific is the fastest-growing region at 7.8% CAGR, fueled by China's military modernization and India's procurement programs. LAMEA (Middle East & Africa) grows at 6.5%, with conflicts driving demand. Regulatory stringency is high in North America and Europe, medium in Asia-Pacific, and low in LAMEA.
North America: Mature market, high barriers to entry, focus on technological superiority.
Europe: Increasing budgets, opportunities in Eastern Europe, strong local vendors.
Asia-Pacific: Rapid growth, local manufacturing push, potential for cost-effective solutions.
LAMEA: Volatile but high demand, less stringent regulations, growing Turkish and Israeli exports.
In terms of growth corridors, the Indo-Pacific and Eastern Europe present significant opportunities. The U.S. Indo-Pacific Command's budget for targeting systems increased by 10% in 2025. European countries like Poland and Germany are investing heavily in land-based systems. The Naval Target Acquisition Systems Market is particularly strong in Asia-Pacific due to maritime disputes. The Land Target Acquisition Systems Market dominates in LAMEA due to ongoing conflicts. The Airborne Target Acquisition Systems Market is growing in all regions.
Pricing Dynamics, Cost Structures & Margin Pressure in Target Acquisition Systems Market
The average selling price (ASP) of target acquisition systems varies widely, from $50,000 for simple thermal sights to over $5 million for advanced airborne radar systems. ASPs have been rising at 2-3% annually due to increased functionality and inflation. Cost breakdown for a typical system: raw materials 35% (including rare earths, semiconductors, optics), labor 25%, R&D 20%, manufacturing overhead 15%, and logistics 5%. Margin structures vary: prime contractors enjoy 15-20% gross margins, while sub-tier suppliers have 10-15%. Pricing power is strongest for differentiated, high-tech systems. Inflationary pressures from raw materials, especially rare earths, are squeezing margins. The Rare Earth Materials Market has seen price volatility, with neodymium prices increasing 30% in 2024. Companies are passing some costs to customers, but long-term contracts limit flexibility. Competitive bidding also pressures prices. The Defense Electronics Market faces similar dynamics. To mitigate, firms are investing in automation and supply chain resilience.
Export, Cross-Border Trade & Tariff Impact on Target Acquisition Systems Market
Global trade in target acquisition systems is dominated by a few net exporters: the United States, France, Israel, and Germany. The U.S. accounts for approximately 40% of global defense exports, with target acquisition systems a key category. Major importers include Saudi Arabia, India, Japan, and Australia. Trade corridors: U.S. to NATO and Asia-Pacific allies; Europe to Middle East and North Africa; Israel to Asia and Europe. Tariff barriers are generally low for defense goods, but non-tariff barriers such as ITAR and EU dual-use regulations are significant. ITAR restricts export of certain technologies, impacting U.S. firms' market access. In 2024, U.S. defense exports totaled $200 billion, with target acquisition systems estimated at $15 billion. The Ukraine conflict has increased demand for U.S. and European systems in Eastern Europe. Tariffs on steel and aluminum have minor impact. Geopolitical tensions with China restrict exports of advanced systems to certain countries. The Military Targeting Systems Market is heavily influenced by these trade flows.
Target Acquisition Systems Market Segmentation
1. Platform
1.1. Land
1.2. Airborne
1.3. Naval
Target Acquisition Systems Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Target Acquisition Systems Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 6.04% from 2020-2034
Segmentation
By Platform
Land
Airborne
Naval
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Platform
5.1.1. Land
5.1.2. Airborne
5.1.3. Naval
5.2. Market Analysis, Insights and Forecast - by Region
5.2.1. North America
5.2.2. South America
5.2.3. Europe
5.2.4. Middle East & Africa
5.2.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Platform
6.1.1. Land
6.1.2. Airborne
6.1.3. Naval
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Platform
7.1.1. Land
7.1.2. Airborne
7.1.3. Naval
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Platform
8.1.1. Land
8.1.2. Airborne
8.1.3. Naval
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Platform
9.1.1. Land
9.1.2. Airborne
9.1.3. Naval
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Platform
10.1.1. Land
10.1.2. Airborne
10.1.3. Naval
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Aselsan AS
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. BAE Systems PLC
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Elbit Systems Ltd
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Hensoldt
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Instro Precision Limited
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Israel Aerospace Industries
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Wuhan JOHO Technology Co Ltd
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Leonardo SpA
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Lockheed Martin Corporation
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Raytheon Technologies Corporation
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. Rheinmetall AG
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.1.12. Safran SA
11.1.12.1. Company Overview
11.1.12.2. Products
11.1.12.3. Company Financials
11.1.12.4. SWOT Analysis
11.1.13. Thales Grou
11.1.13.1. Company Overview
11.1.13.2. Products
11.1.13.3. Company Financials
11.1.13.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Target Acquisition Systems Market Revenue Breakdown (billion, %) by Region 2026 & 2034
Figure 2: North America Target Acquisition Systems Market Revenue (billion), by Platform 2026 & 2034
Figure 3: North America Target Acquisition Systems Market Revenue Share (%), by Platform 2026 & 2034
Figure 4: North America Target Acquisition Systems Market Revenue (billion), by Country 2026 & 2034
Figure 5: North America Target Acquisition Systems Market Revenue Share (%), by Country 2026 & 2034
Figure 6: South America Target Acquisition Systems Market Revenue (billion), by Platform 2026 & 2034
Figure 7: South America Target Acquisition Systems Market Revenue Share (%), by Platform 2026 & 2034
Figure 8: South America Target Acquisition Systems Market Revenue (billion), by Country 2026 & 2034
Figure 9: South America Target Acquisition Systems Market Revenue Share (%), by Country 2026 & 2034
Figure 10: Europe Target Acquisition Systems Market Revenue (billion), by Platform 2026 & 2034
Figure 11: Europe Target Acquisition Systems Market Revenue Share (%), by Platform 2026 & 2034
Figure 12: Europe Target Acquisition Systems Market Revenue (billion), by Country 2026 & 2034
Figure 13: Europe Target Acquisition Systems Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Middle East & Africa Target Acquisition Systems Market Revenue (billion), by Platform 2026 & 2034
Figure 15: Middle East & Africa Target Acquisition Systems Market Revenue Share (%), by Platform 2026 & 2034
Figure 16: Middle East & Africa Target Acquisition Systems Market Revenue (billion), by Country 2026 & 2034
Figure 17: Middle East & Africa Target Acquisition Systems Market Revenue Share (%), by Country 2026 & 2034
Figure 18: Asia Pacific Target Acquisition Systems Market Revenue (billion), by Platform 2026 & 2034
Figure 19: Asia Pacific Target Acquisition Systems Market Revenue Share (%), by Platform 2026 & 2034
Figure 20: Asia Pacific Target Acquisition Systems Market Revenue (billion), by Country 2026 & 2034
Figure 21: Asia Pacific Target Acquisition Systems Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Target Acquisition Systems Market Revenue billion Forecast, by Platform 2020 & 2034
Table 2: Target Acquisition Systems Market Revenue billion Forecast, by Region 2020 & 2034
Table 3: North America Target Acquisition Systems Market Revenue billion Forecast, by Platform 2020 & 2034
Table 4: North America Target Acquisition Systems Market Revenue billion Forecast, by Country 2020 & 2034
Table 5: United States Target Acquisition Systems Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 6: Canada Target Acquisition Systems Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 7: Mexico Target Acquisition Systems Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 8: South America Target Acquisition Systems Market Revenue billion Forecast, by Platform 2020 & 2034
Table 9: South America Target Acquisition Systems Market Revenue billion Forecast, by Country 2020 & 2034
Table 10: Brazil Target Acquisition Systems Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 11: Argentina Target Acquisition Systems Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 12: Rest of South America Target Acquisition Systems Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 13: Europe Target Acquisition Systems Market Revenue billion Forecast, by Platform 2020 & 2034
Table 14: Europe Target Acquisition Systems Market Revenue billion Forecast, by Country 2020 & 2034
Table 15: United Kingdom Target Acquisition Systems Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 16: Germany Target Acquisition Systems Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 17: France Target Acquisition Systems Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 18: Italy Target Acquisition Systems Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 19: Spain Target Acquisition Systems Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 20: Russia Target Acquisition Systems Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 21: Benelux Target Acquisition Systems Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 22: Nordics Target Acquisition Systems Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 23: Rest of Europe Target Acquisition Systems Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 24: Middle East & Africa Target Acquisition Systems Market Revenue billion Forecast, by Platform 2020 & 2034
Table 25: Middle East & Africa Target Acquisition Systems Market Revenue billion Forecast, by Country 2020 & 2034
Table 26: Turkey Target Acquisition Systems Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 27: Israel Target Acquisition Systems Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 28: GCC Target Acquisition Systems Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 29: North Africa Target Acquisition Systems Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 30: South Africa Target Acquisition Systems Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 31: Rest of Middle East & Africa Target Acquisition Systems Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 32: Asia Pacific Target Acquisition Systems Market Revenue billion Forecast, by Platform 2020 & 2034
Table 33: Asia Pacific Target Acquisition Systems Market Revenue billion Forecast, by Country 2020 & 2034
Table 34: China Target Acquisition Systems Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 35: India Target Acquisition Systems Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 36: Japan Target Acquisition Systems Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 37: South Korea Target Acquisition Systems Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 38: ASEAN Target Acquisition Systems Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 39: Oceania Target Acquisition Systems Market Revenue (billion) Forecast, by Application 2020 & 2034
Table 40: Rest of Asia Pacific Target Acquisition Systems Market Revenue (billion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
We conducted over 500 interviews with industry experts across the value chain, including electro-optical sensor manufacturers, radar and LiDAR system integrators, fire control system developers, precision optics suppliers, and defense electronics contract manufacturers.
Interviews targeted stakeholders such as Director of Defense Procurement, Program Manager for Targeting Systems, Chief Technology Officer (Defense Electronics), and Supply Chain Manager for Military Sensors.
Primary research accounted for 70-80% of total research effort, ensuring granular insights into demand drivers, pricing, and supply chain dynamics.
Data was validated through cross-referencing with secondary sources and triangulation.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Director of Defense Procurement
30%
Program Manager for Targeting Systems
30%
Chief Technology Officer (Defense Electronics)
20%
Supply Chain Manager for Military Sensors
20%
Industry Ecosystem Breakdown
Company Type
Representation (%)
Electro-optical sensor manufacturers
25%
Radar and LiDAR system integrators
20%
Fire control system developers
20%
Precision optics suppliers
20%
Defense electronics contract manufacturers
15%
Secondary Research & Industry Benchmarking
We analyzed 20-30% of data from secondary sources, including Bloomberg, Factiva, Hoovers, and PitchBook for financial and market data.
We avoided market research websites, relying on primary and authoritative secondary sources.
All reports are updated to the date of purchase, ensuring the latest data.
Demand Modeling & Market Estimation
We employed both top-down and bottom-up methodologies simultaneously, validated via multi-level data triangulation.
Bottom-up estimation used quantitative metrics such as number of active military platforms requiring targeting systems, average unit price of thermal imaging modules, annual defense procurement budgets by region, and number of new defense contracts awarded for targeting systems.
Top-down approach leveraged aggregated defense spending and segment shares.
The model achieved a guaranteed estimated data accuracy level of 85-90%.
Data Accuracy & Quality Check
All data points were cross-validated through at least three independent sources.
We conducted sanity checks against historical trends and industry benchmarks.
Final figures were reviewed by senior analysts and subject matter experts.
Any discrepancies were resolved through follow-up interviews or additional data collection.
Frequently Asked Questions
1. What raw materials are critical for target acquisition systems and how are supply chains managed?
Target acquisition systems rely on rare earth elements like neodymium and dysprosium for magnets in sensors and motors. Supply chains are concentrated in China, which controls over 80% of rare earth refining. Companies such as Lockheed Martin and Thales are diversifying sourcing through recycling and partnerships with Australian miners.
2. Which region is the fastest-growing for target acquisition systems and why?
Asia-Pacific is the fastest-growing region, projected to expand at a CAGR of 7.8% from 2025 to 2033. This growth is driven by military modernization programs in India, China, and South Korea. Emerging opportunities exist in Southeast Asia as nations upgrade their defense capabilities.
3. Which region dominates the target acquisition systems market and what factors contribute to its leadership?
North America holds the largest share at 35% in 2025, driven by the U.S. Department of Defense's extensive procurement budgets. The region's leadership stems from advanced R&D ecosystems, with companies like Raytheon and Lockheed Martin investing heavily in next-generation systems.
4. How do export-import dynamics shape the target acquisition systems market?
The United States and Europe are net exporters, with the U.S. accounting for approximately 40% of global defense exports in this segment. Key importers include India, Saudi Arabia, and Japan, which rely on foreign suppliers for advanced targeting technologies. Trade flows are influenced by ITAR and other export control regimes.
5. What is the level of investment activity and venture capital interest in target acquisition systems?
Venture capital interest is growing, particularly in startups developing AI-enhanced targeting and autonomous systems. In 2024, defense tech startups raised over $3 billion globally, with companies like Anduril and Palantir attracting significant funding. Traditional defense primes continue to dominate M&A, with $12 billion in deals announced in 2024.
6. What sustainability and ESG factors affect the target acquisition systems market?
Environmental impact is mainly from rare earth mining and electronic waste. Companies like Leonardo and Rheinmetall are implementing recycling programs to reduce reliance on virgin materials. ESG reporting is becoming a requirement for defense contractors, with the EU's taxonomy pushing for sustainable practices.