Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Injection Molding Machine Market: Who Wins 2025–2033?
Injection Molding Machine Market
Injection Molding Machine Market: Who Wins 2025–2033?
Injection Molding Machine Market by Clamping Force (Less Than 200 Tons Force, 200-500 Tons Force and More Than 200-500 Tons Force), by Machine Type (All-electric, Hydraulic and Hybrid), by Solution (New Sales and Aftermarket), by Pressure Type (Low Pressure and High Pressure), by Application (Automotive, Packaging, Electronics, Healthcare, Consumer Goods, Toy Making, Building & Construction, Home Appliances, Other), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Jul 31, 2026|Base Year : 2025|Pages : 501
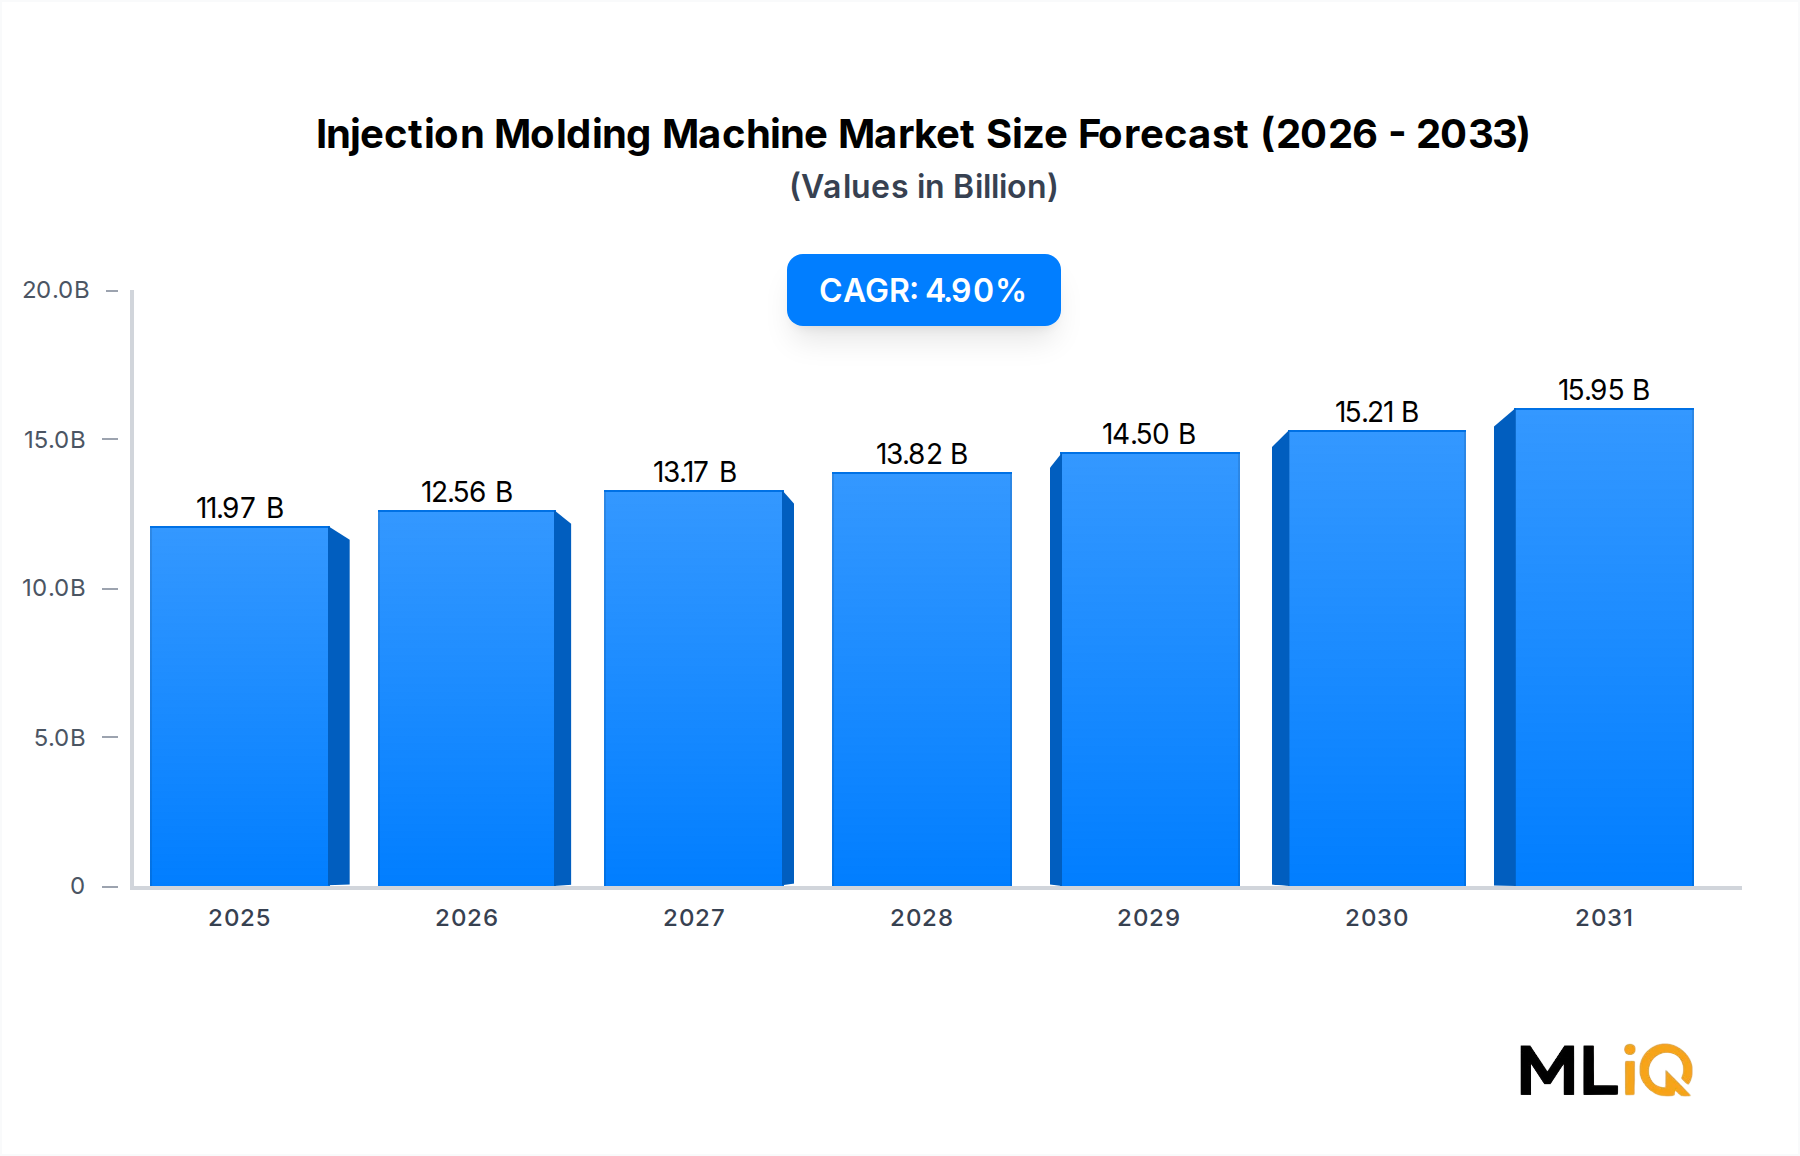
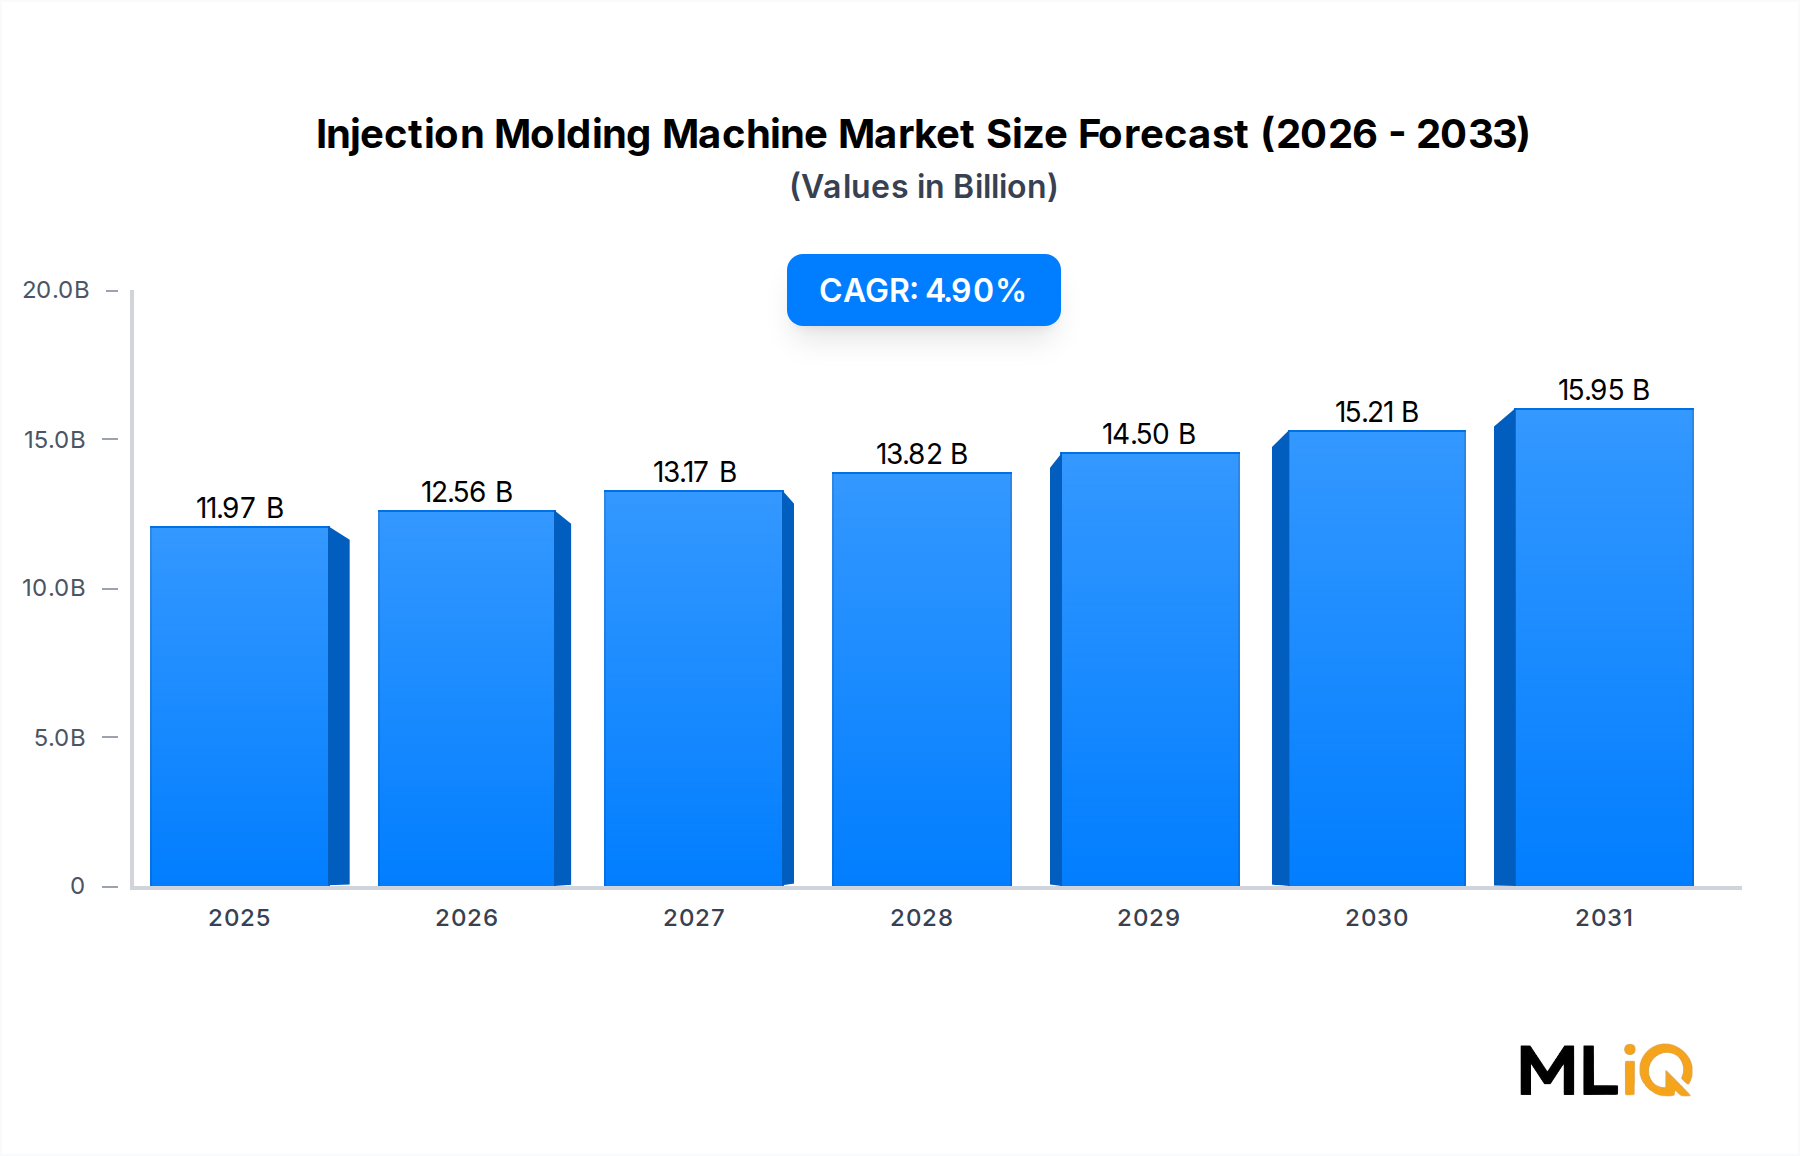
The global injection molding machine market is positioned for sustained, compounding expansion across the 2025–2033 forecast horizon, underpinned by accelerating industrialization, evolving end-use demand across high-volume sectors, and a structural pivot toward energy-efficient and precision-driven equipment. Valued at USD 11,971.53 million in the base year, the market is projected to advance at a CAGR of 4.9%, representing a multi-billion-dollar value creation opportunity for OEMs, technology integrators, and investment stakeholders.
Injection Molding Machine Market Size (In Billion)
20.0B
15.0B
10.0B
5.0B
0
11.97 B
2025
12.56 B
2026
13.17 B
2027
13.82 B
2028
14.50 B
2029
15.21 B
2030
15.95 B
2031
At its core, the market's momentum is driven by three macro-level forces: (1) the relentless expansion of automotive lightweighting programs demanding high-precision plastic component production; (2) the post-pandemic surge in medical device and pharmaceutical packaging manufacturing requiring sterile, repeatable molding cycles; and (3) the rapid infrastructure buildout across Asia Pacific markets fueling demand for construction and consumer goods plastics. These converging tailwinds are redefining capital expenditure cycles across the plastics processing sector.
From a technology standpoint, the transition from conventional hydraulic systems to all-electric and hybrid configurations is reshaping total cost of ownership calculations for procurement teams globally. All-electric machines, commanding premium price points, are achieving faster payback periods through energy savings of 40–70% versus hydraulic equivalents, driving accelerated adoption in precision-sensitive verticals such as electronics and healthcare.
The competitive landscape remains concentrated among established Japanese, European, and increasingly dominant Chinese manufacturers, with firms such as ENGEL, ARBURG, HAITIAN, and HUSKY anchoring respective niches through differentiated technology portfolios. Meanwhile, the Plastics Processing Machinery Market — of which injection molding machines represent the largest single equipment category — continues to attract cross-sector M&A activity as consolidation reshapes vendor hierarchies.
Geopolitically, trade tensions and near-shoring mandates are prompting regional capacity realignment, particularly in North America and Southeast Asia, creating new investment corridors for domestic machine manufacturers and system integrators. Supply chain resilience, rare earth dependencies in servo motor systems, and raw polymer price dynamics are emerging as critical operational risk vectors that procurement and operations leaders must proactively manage through 2033.
Segment Deep-Dive: Automotive Application Dominance in Injection Molding Machine Market
The automotive application segment represents the single largest end-use vertical within the global injection molding machine industry, accounting for an estimated 28–32% of total market revenue in the base year. Its dominance is structural rather than cyclical: every modern light vehicle contains between 1,500 and 2,000 individual injection-molded plastic components, from dashboard assemblies and bumper fascias to intake manifolds, fluid reservoirs, and increasingly complex battery housing structures for electric vehicles (EVs).
Lightweighting as a Structural Demand Driver
Regulatory pressure across the European Union, United States, and China to reduce vehicle emissions has accelerated the substitution of metal components with engineered plastics, directly expanding the addressable market for high-clamping-force injection molding machines. OEM programs targeting 10–15% weight reduction per vehicle generation are demanding machines with enhanced shot consistency, multi-material capability, and real-time process monitoring — capabilities that command significant premium pricing. Machines in the 200–500 tons clamping force range and above are experiencing disproportionate demand growth within this segment, as structural automotive components require both large tonnage and precise control.
EV Transition and Battery Component Manufacturing
The global shift toward battery electric vehicles is catalyzing a secondary demand wave within the automotive sub-segment. Battery enclosures, thermal management module housings, high-voltage connector bodies, and busbars all require injection molding at tolerances previously associated only with aerospace applications. This is driving procurement interest in hybrid and all-electric injection molding machines capable of delivering sub-micron repeatability. Companies such as ENGEL Austria and ARBURG have specifically launched automotive-focused machine platforms with integrated process documentation for traceability compliance under IATF 16949 quality standards.
Sub-Segment: Hydraulic vs. All-Electric Machines in Automotive
Large-tonnage hydraulic machines continue to dominate automotive structural part production due to their superior force generation and cost-per-ton economics at scale. However, the electronics-intensive interior component and connector sub-segment is rapidly migrating toward all-electric platforms. SUMITOMO HEAVY INDUSTRIES and NISSEI PLASTIC INDUSTRIAL CO. have established particularly strong positions in the all-electric automotive sub-segment in Asia, while MILACRON (under Hillenbrand Inc.) retains significant share in North American hydraulic machine installations for Tier 1 and Tier 2 suppliers.
Margin Dynamics and Competitive Pressure
While the automotive segment commands volume, margin pressure is intensifying as Chinese manufacturers — notably HAITIAN INTERNATIONAL — aggressively price entry-level and mid-range machines for cost-sensitive Tier 2 suppliers in emerging markets. This pricing dynamic is compressing margins for traditional European and Japanese vendors in standard machine categories, accelerating their portfolio pivot toward high-mix, low-volume precision platforms and solution-selling models that bundle machine hardware with digital process monitoring software, tooling support, and lifecycle service contracts.
The Automotive Plastics Market itself is growing at a CAGR exceeding 5.2% through the early 2030s, providing a direct and quantifiable demand signal for injection molding machine procurement planners. The correlation between automotive platform launches — particularly EV-dedicated architectures — and machine investment cycles is increasingly tight, making automotive OEM production calendars a leading indicator for injection molding machine order intake at major vendors.
1. Escalating Demand from Packaging and Healthcare Verticals
The Plastic Packaging Market is expanding robustly, driven by e-commerce fulfillment requirements, food safety regulations, and pharmaceutical cold-chain logistics growth. Injection molding machines are indispensable for producing caps, closures, vials, pre-forms, and thin-wall containers at high cycle rates. The global pharmaceutical packaging sector alone is projected to exceed USD 150 billion by 2028, creating sustained machine investment demand.
2. All-Electric Machine Adoption and Total Cost of Ownership Economics
Government energy efficiency mandates — including the EU's Ecodesign Regulation and China's GB energy labeling standards — are compelling manufacturers to upgrade legacy hydraulic fleets. All-electric injection molding machines reduce energy consumption by 40–70% and eliminate hydraulic fluid lifecycle costs, delivering compelling ROI for high-shift production environments. The Electric Injection Molding Machine Market is consequently outpacing the broader market's CAGR.
3. Asia Pacific Industrialization and Manufacturing FDI
Foreign direct investment into Southeast Asian manufacturing hubs — Vietnam, Thailand, Indonesia, and India — is generating greenfield machine installation demand at a pace not seen since China's WTO-era expansion. Local governments are offering capital subsidy programs for precision manufacturing infrastructure, further catalyzing machine procurement.
Primary Restraints
1. High Capital Expenditure and Extended Payback Periods
Premium all-electric and hybrid injection molding machines carry price premiums of 30–60% over comparable hydraulic systems, creating adoption barriers for SME manufacturers in price-sensitive emerging markets. Financing access and working capital constraints significantly dampen replacement cycle velocity.
2. Skilled Operator Shortage
Advanced machines with multi-axis servo systems, integrated Industry 4.0 connectivity, and real-time SPC (Statistical Process Control) require operators with mechatronics and data analytics competencies that are scarce across most manufacturing labor markets. This skills gap slows deployment velocity and increases post-installation integration costs.
3. Raw Material Price Volatility
Fluctuations in polymer resin prices — particularly polyethylene, polypropylene, and engineering-grade polymers — directly affect the economics of injection molding operations, periodically suppressing machine investment appetite when resin costs compress processor margins.
The competitive landscape of the global injection molding machine industry is characterized by a tiered structure: a small group of technologically dominant European and Japanese OEMs competing on precision and innovation, flanked by high-volume Chinese manufacturers leveraging cost advantages and rapidly improving technical capabilities.
ARBURG GmbH + CO KG: A privately held German precision machine builder, ARBURG is globally recognized for its ALLROUNDER series, which spans hydraulic, hybrid, and all-electric configurations. The company maintains a strong position in the medical, electronics, and micro-molding segments, supported by its Gestica control system with Industry 4.0 integration.
HUSKY INJECTION MOLDING SYSTEMS LTD.: The Canadian specialist dominates the global PET preform and beverage closure injection molding segment, operating an estimated 40%+ market share in high-output preform systems. Husky's integrated hot runner systems and HyCAP platform differentiate it in packaging-intensive production environments.
HAITIAN INTERNATIONAL HOLDING LIMITED: China's largest injection molding machine manufacturer by volume, Haitian has successfully disrupted mid-market price segments globally with its Jupiter, Mars, and Zhafir series. The company is aggressively expanding its all-electric Zhafir Plastics Machinery brand to compete in precision-sensitive verticals previously dominated by Japanese and European vendors.
HILLENBRAND INC. (MILACRON HOLDINGS CORP.): An American industrial conglomerate that acquired Milacron to establish a plastics processing machinery platform. Milacron's MAGNA-TOGGLE and MAXIMA series serve large-tonnage automotive and durable goods segments, with a significant aftermarket parts and service revenue stream.
SHIBAURA MACHINE CO. LTD: Formerly Toshiba Machine, Shibaura is a respected Japanese manufacturer with particular strength in precision all-electric machines for electronics and optical component applications. Its EC-SXIII and EC-CL series incorporate proprietary closed-loop servo controls.
SUMITOMO HEAVY INDUSTRIES, LTD.: A leading Japanese all-electric injection molding machine manufacturer, Sumitomo's SE series is a benchmark platform for the electronics and medical sectors in Asia and Europe. The company has formed strategic alliances with Demag to extend its European market reach.
BMB S.P.A.: An Italian specialty manufacturer known for high-performance hybrid machines, BMB serves niche European automotive and technical parts segments with customized large-tonnage solutions.
THE JAPAN STEEL WORKS, LTD. (JSW): JSW manufactures a comprehensive range of all-electric injection molding machines under its J-ADS series, with significant penetration in automotive and optical disk manufacturing applications in Japan and Southeast Asia.
UBE INDUSTRIES, LTD.: A diversified Japanese industrial company, UBE's injection molding machine division focuses on die-casting and hybrid machine technologies, serving automotive aluminum and magnesium component manufacturers.
NIIGON MACHINES LTD.: A Canadian manufacturer of ultra-high-speed injection molding systems, Niigon targets the PET preform and thin-wall packaging segments with machines engineered for cycle times below 2 seconds.
ENGEL AUSTRIA GmbH: Austria-based ENGEL is one of Europe's largest injection molding machine manufacturers, renowned for its tie-bar-less technology and extensive portfolio spanning micro-injection to large-tonnage systems. ENGEL's digital inject 4.0 platform is among the most advanced Industry 4.0 machine ecosystems commercially available.
NISSEI PLASTIC INDUSTRIAL CO., LTD.: A Japanese manufacturer with deep expertise in micro-injection molding and ultra-high-precision all-electric machines, Nissei serves the medical device, connector, and optical sectors with machines capable of shot weights below 0.01 grams.
CHINA NATIONAL CHEMICAL CORPORATION LTD. (KRAUSSMAFFEI GROUP GmbH): ChemChina's acquisition of KraussMaffei brought one of Germany's most storied injection molding machine brands under Chinese state ownership. KraussMaffei continues to operate with German engineering leadership and serves premium automotive, construction, and packaging segments globally with its CX, MX, and PX series.
Strategic Milestones & Recent Developments in Injection Molding Machine Market
January 2024: ENGEL Austria launched its new e-mac 3 all-electric injection molding machine series at Fakuma Asia, featuring a 20% reduction in energy consumption versus the previous generation and integrated digital process optimization via its iQ weight control module.
March 2024: Hillenbrand Inc. announced a strategic restructuring of its Milacron segment, consolidating injection molding machine manufacturing operations across its North American facilities to improve production efficiency and reduce lead times for automotive customers.
May 2024: HAITIAN INTERNATIONAL reported record annual revenues exceeding RMB 14 billion for fiscal 2023, attributing growth to accelerating demand for its Zhafir all-electric series in European and Southeast Asian markets, where energy efficiency mandates are tightening.
August 2024: KraussMaffei Group unveiled its PX 50-180 SilcoSet injection molding system, targeting liquid silicone rubber (LSR) medical component production, reinforcing its position in the growing healthcare manufacturing segment.
October 2024: ARBURG expanded its digital services portfolio through the launch of arburgXworld 3.0, an enhanced machine connectivity and predictive maintenance platform now compatible with third-party peripheral equipment, broadening its MES integration capabilities.
January 2025: SUMITOMO HEAVY INDUSTRIES announced a joint technology development agreement with a leading Japanese automotive OEM to co-develop large-format all-electric injection molding machines specifically engineered for next-generation EV battery housing production.
March 2025: HUSKY INJECTION MOLDING SYSTEMS completed commissioning of a major capacity expansion at its Bolton, Ontario headquarters facility, increasing hot runner system manufacturing throughput by an estimated 25% to address growing demand from beverage and pharmaceutical packaging customers.
Asia Pacific is both the largest and the fastest-growing regional market for injection molding machines, commanding an estimated 55–60% of global revenue share in the base year. China remains the undisputed epicenter of global machine production and consumption, housing the world's largest concentration of plastic processing facilities. Government industrial policy under Made in China 2025 and its successor frameworks is directing capital toward advanced manufacturing automation, sustaining demand for high-specification machines. India is emerging as the region's secondary growth corridor, with its manufacturing sector expansion, rising consumer goods demand, and government PLI (Production Linked Incentive) schemes creating fertile conditions for both domestic and imported machine investment. ASEAN nations — particularly Vietnam, Thailand, and Indonesia — are experiencing accelerating greenfield investment as global supply chains diversify away from single-country concentration.
Europe: Precision and Sustainability Premium
Europe represents the second-largest regional market, characterized by strong demand for all-electric and hybrid machines driven by stringent energy efficiency regulations and high-value end-use applications in automotive, medical devices, and premium consumer goods. Germany, Italy, and Austria host the majority of the region's machine manufacturing capacity. The Hydraulic Injection Molding Machine Market in Europe faces regulatory headwinds as the EU Taxonomy and Ecodesign frameworks increasingly disadvantage energy-intensive hydraulic systems, accelerating fleet upgrade cycles toward all-electric alternatives.
North America: Reshoring and EV Infrastructure Buildout
North America is experiencing a structural uplift in injection molding machine demand driven by manufacturing reshoring initiatives, the CHIPS and Science Act's semiconductor supply chain buildout, and the EV transition requiring domestic battery component manufacturing. The United States and Mexico are primary demand centers, with automotive Tier 1 suppliers in the USMCA trade zone accelerating capital expenditure on advanced molding systems. The Industrial Automation Market is a critical co-investment driver, as manufacturers simultaneously deploy injection molding equipment and robotic automation infrastructure.
Latin America, Middle East & Africa: Emerging Opportunity Markets
Brazil leads Latin American demand, supported by its diversified manufacturing base in automotive, packaging, and consumer goods. The Middle East is investing in polymer conversion capacity to move downstream from petrochemical feedstock exports, creating new demand for injection molding machines. South Africa and Turkey represent the most developed machinery markets within their respective sub-regions, though infrastructure constraints temper near-term growth velocity.
The global trade architecture for injection molding machines reflects the broader industrial geography of high-value capital goods: a small number of technologically advanced nations dominate exports,
Injection Molding Machine Market Segmentation
1. Clamping Force
1.1. Less Than 200 Tons Force
1.2. 200-500 Tons Force and More Than 200-500 Tons Force
2. Machine Type
2.1. All-electric
2.2. Hydraulic and Hybrid
3. Solution
3.1. New Sales and Aftermarket
4. Pressure Type
4.1. Low Pressure and High Pressure
5. Application
5.1. Automotive
5.2. Packaging
5.3. Electronics
5.4. Healthcare
5.5. Consumer Goods
5.6. Toy Making
5.7. Building & Construction
5.8. Home Appliances
5.9. Other
Injection Molding Machine Market Segmentation By Geography
Table 64: Rest of Asia Pacific Injection Molding Machine Market Revenue (million) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
The research framework for the Injection Molding Machine Market (2026–2034) report is anchored on a robust primary research base, constituting 70–80% of the total research effort. This ensures that market estimates, competitive intelligence, and demand projections are grounded in verified, first-hand industry knowledge rather than extrapolated assumptions.
Primary research was conducted through structured interviews, online surveys, and expert panel discussions with key decision-makers and technical specialists across the injection molding machine value chain. The following company types were specifically targeted to ensure comprehensive value-chain coverage:
OEM Injection Molding Machine Manufacturers (e.g., producers of all-electric, hydraulic, and hybrid machines with clamping forces ranging from <200 tons to >500 tons)
Injection Molding Contract Manufacturers & Processors (facilities producing automotive components, medical devices, and consumer packaging using purchased machines)
Mold & Tooling Fabricators (precision tool shops supplying molds compatible with high-pressure and low-pressure machine configurations)
Polymer & Raw Material Suppliers (resin compounders and masterbatch suppliers whose material specifications directly influence machine selection and clamping force requirements)
Aftermarket Parts Distributors & Service Providers (firms specializing in hydraulic pump refurbishment, servo-motor upgrades, and predictive maintenance solutions for installed machine bases)
The following primary stakeholder profiles were interviewed to capture both strategic and operational market perspectives:
Plant Engineering Managers at Tier-1 Automotive Suppliers – responsible for machine procurement decisions, clamping force specification, and cycle-time optimization across automotive injection molding lines
Process Development Engineers at Medical Device OEMs – overseeing clean-room-grade, all-electric machine adoption for healthcare and regulated-environment applications
Procurement Directors at Consumer Packaging & FMCG Manufacturers – managing high-volume, multi-cavity mold operations and evaluating total cost of ownership between hydraulic and hybrid machine types
Chief Technology Officers at Injection Molding Machine OEMs – providing forward-looking perspectives on electrification trends, Industry 4.0 integration, and energy-efficiency mandates shaping product roadmaps through 2034
Primary data collection spanned respondents across North America, Europe, Asia Pacific, South America, and the Middle East & Africa, ensuring geographic representativeness aligned with the report's regional segmentation framework.
Aftermarket Parts Distributors & Service Providers
14%
Secondary Research & Industry Benchmarking
Secondary research constitutes the remaining 20–30% of the research effort and serves as a critical validation and contextual layer for all primary findings. Sources were rigorously selected to exclude general market research aggregator websites, prioritizing authoritative financial databases, government portals, trade associations, and peer-reviewed technical publications.
Financial & Corporate Databases Utilized:
Bloomberg Terminal – for company financials, M&A activity tracking, and capital expenditure trends among machine OEMs and end-user industries
Factiva (Dow Jones) – for news flow analysis, product launch announcements, and regional regulatory developments
Hoovers (Dun & Bradstreet) – for competitive landscape profiling, revenue benchmarking, and company segmentation
PitchBook – for venture capital and private equity investment tracking in electric machine technology startups and smart manufacturing ecosystems
Market sizing and forecasting for the Injection Molding Machine Market (2026–2034) employed a dual-methodology approach combining top-down and bottom-up estimation models, cross-validated through multi-level data triangulation to ensure internal consistency across segments, geographies, and time horizons.
Top-Down Approach:
The global plastics processing equipment market size was established using authoritative industry databases and trade association production data. Injection molding machines were then isolated as a sub-segment using category-specific shipment ratios and capital expenditure allocations sourced from OEM annual reports and government manufacturing surveys. Regional shares were derived from macroeconomic indicators including industrial output indices, polymer consumption volumes, and manufacturing GDP contributions across all covered geographies.
Bottom-Up Approach:
The bottom-up model was constructed by aggregating demand at the application-segment and machine-specification level. The following four key metrics and variables were used as core inputs for bottom-up market size calculation:
Installed Machine Base by Clamping Force Category – estimated number of active injection molding machines (<200 tons, 200–500 tons, >500 tons) by region, derived from OEM shipment data and industry association records, used to calculate replacement demand and aftermarket revenue pools
Average Selling Price (ASP) by Machine Type – weighted average transaction prices for all-electric, hydraulic, and hybrid machines segmented by clamping force, validated through distributor interviews and OEM list price benchmarking
Machine Utilization Rate & Replacement Cycle – average operational lifespan (typically 10–15 years for hydraulic; 8–12 years for all-electric) and utilization rates by end-use application (automotive, packaging, healthcare), used to project new sales vs. aftermarket demand through 2034
End-Use Industry Capital Expenditure Growth Rates – sector-specific capex growth trajectories for automotive lightweighting programs, pharmaceutical-grade molding investments, and electronics miniaturization demand, correlated with machine procurement volumes by pressure type (low vs. high pressure)
Multi-Level Data Triangulation:
All estimates underwent three independent triangulation layers: (1) cross-referencing primary interview data against secondary trade and government datasets; (2) validating regional segment totals against country-level import/export data for injection molding equipment (HS Code 8477); and (3) reconciling bottom-up application-level aggregates with top-down macro-industry benchmarks to eliminate structural inconsistencies.
Data Accuracy & Quality Check
All data inputs, model outputs, and forecast projections are subject to a guaranteed estimated accuracy level of 85–90%, achieved through a multi-stage quality assurance protocol embedded throughout the research lifecycle.
Iterative Respondent Validation: Preliminary market size estimates and segment share findings were shared with a subset of senior primary respondents for factual verification and directional confirmation before finalization.
Statistical Outlier Screening: Survey responses and interview data were subjected to statistical cleaning protocols to identify and neutralize outlier inputs that could distort segment-level averages, particularly for niche application areas such as toy making and building & construction.
Forecast Sensitivity Analysis: All 2026–2034 forecast projections were stress-tested against three macroeconomic scenarios (base, optimistic, and conservative), incorporating variables such as polymer price volatility, energy cost trajectories, and trade policy shifts impacting cross-border machine procurement.
Continuous Data Currency: Every version of this report is updated up to the date of purchase, ensuring that the most recent OEM announcements, regulatory changes, macroeconomic shifts, and competitive developments are reflected in the final deliverable. Real-time monitoring of key market signals is maintained through Bloomberg alerts, trade press tracking via Factiva, and association bulletin subscriptions throughout the report lifecycle.
Frequently Asked Questions
1. How are technological innovations shaping R&D trends in injection molding machines?
All-electric injection molding machines are displacing hydraulic models due to 30–70% lower energy consumption and higher repeatability tolerances. Manufacturers like ARBURG and ENGEL AUSTRIA are investing in servo-driven systems and Industry 4.0 integration, embedding real-time process monitoring directly into machine controllers. Hybrid machine platforms are also gaining traction where hydraulic clamping force requirements exceed what all-electric systems economically deliver.
2. Which companies hold the strongest competitive positions in the injection molding machine market?
HAITIAN INTERNATIONAL HOLDING LIMITED commands significant volume share in Asia-Pacific, leveraging cost-competitive manufacturing and broad product lines spanning clamping forces from sub-200 tons to heavy-duty configurations. ENGEL AUSTRIA GmbH and ARBURG GmbH lead in Europe with premium all-electric and hybrid systems. HUSKY INJECTION MOLDING SYSTEMS LTD. dominates the packaging-grade high-speed segment, while KraussMaffei Group GmbH—operating under CHINA NATIONAL CHEMICAL CORPORATION—bridges European engineering with Asian scale.
3. What end-user industries are driving downstream demand for injection molding machines?
Automotive remains the highest-value application segment, with lightweighting mandates for EV structural and interior components sustaining capital investment in large-tonnage machines. Packaging is the highest-volume application, particularly rigid packaging for food and pharmaceuticals requiring high-speed, high-precision cycles. Healthcare and electronics are fast-growing segments, with medical device molding requiring ISO-class clean-room-compatible all-electric machines, and consumer electronics driving miniaturization of mold tooling.
4. Why are purchasing patterns shifting toward all-electric injection molding machines among manufacturers?
Total cost of ownership analysis increasingly favors all-electric machines: energy savings of up to 70% versus hydraulic equivalents reduce operating expenditure over a 10-year asset life by a material margin. Regulatory pressure on factory-floor energy intensity in the EU and China's industrial efficiency mandates are accelerating fleet replacement cycles. Precision-sensitive sectors—healthcare, electronics—further pull demand toward all-electric platforms due to zero hydraulic fluid contamination risk and tighter shot-weight repeatability.
5. What are the key segments defining the injection molding machine market by clamping force and machine type?
By clamping force, machines below 200 tons serve electronics and consumer goods applications, while the 200–500 ton and above bracket addresses automotive structural parts and thick-wall industrial components. By machine type, all-electric machines are the fastest-growing sub-segment, while hydraulic machines retain dominance in high-tonnage applications where force-to-cost ratios still favor fluid power. The aftermarket and services solution layer is growing as installed base expansion increases demand for mold changes, retrofits, and predictive maintenance contracts.
6. What is the current market size, valuation, and projected CAGR for the injection molding machine market through 2033?
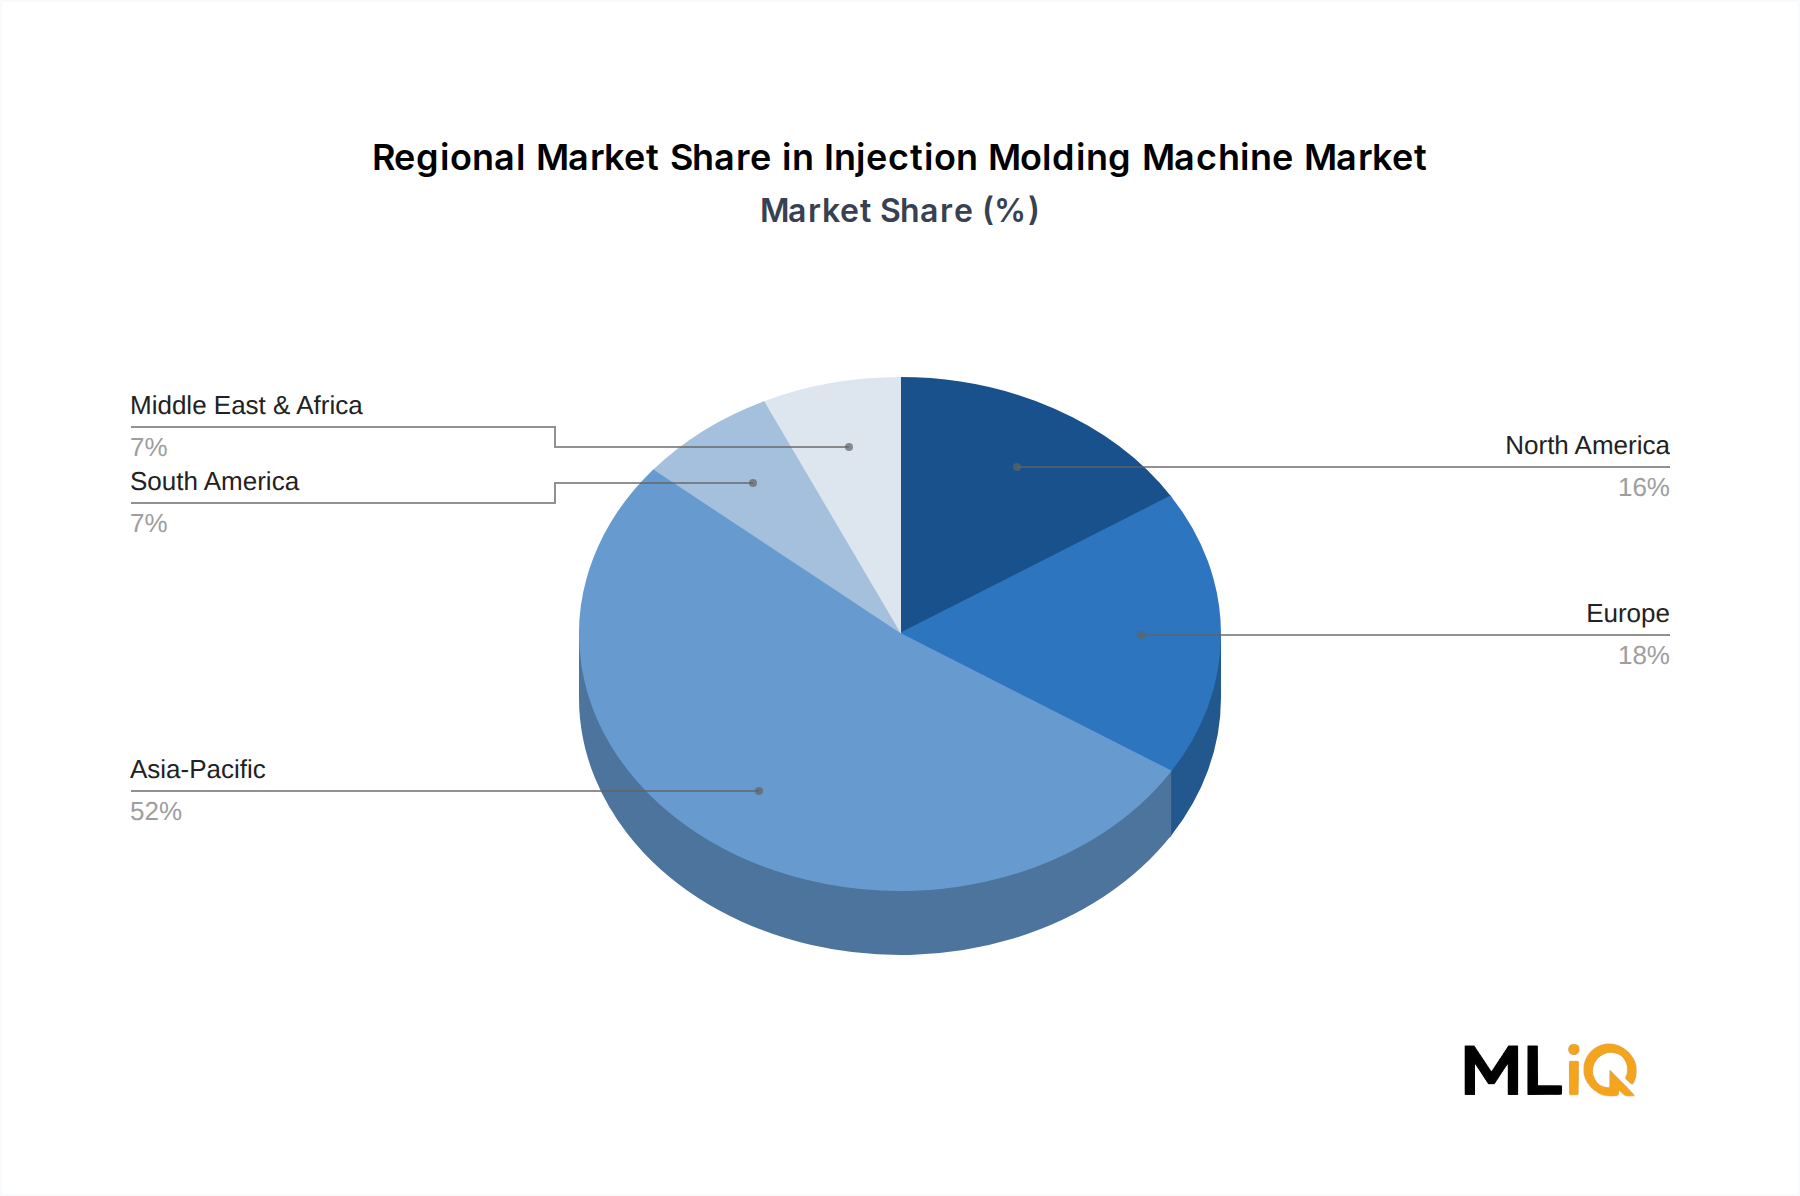
The global injection molding machine market is valued at approximately $11,971.53 million and is projected to grow at a CAGR of 4.9% through 2033. Asia-Pacific accounts for an estimated 52% of global market share, anchored by China's manufacturing base and expanding demand from India and ASEAN production hubs. North America and Europe together represent roughly 34% of the market, driven by re-shoring initiatives and premium machine segment upgrades rather than volume growth.