Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
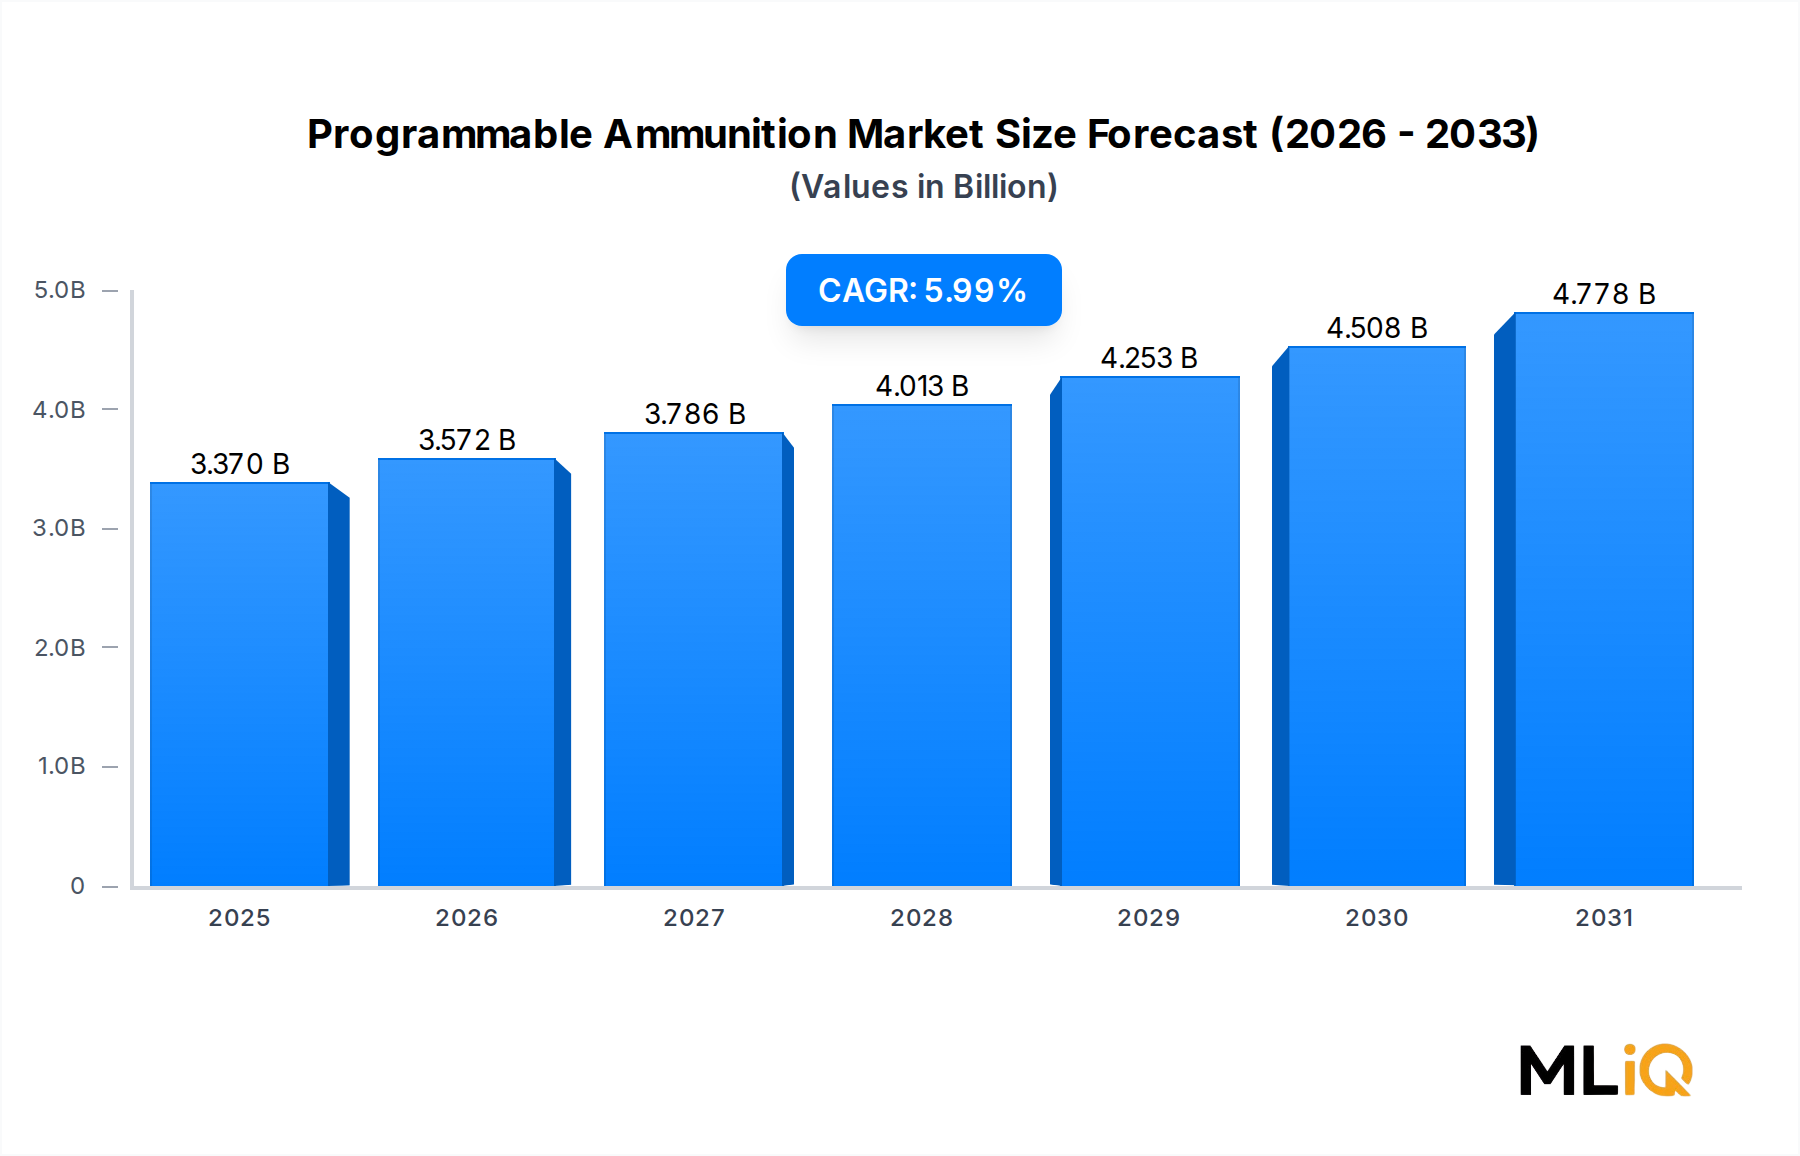
Programmable Ammunition Market CAGR 5.99% Through 2034
Programmable Ammunition Market
Programmable Ammunition Market CAGR 5.99% Through 2034
Programmable Ammunition Market by Detonation Type (Time Programmable, Impact Self-Destruct, Proximity, Remote Wireless), by Caliber (Medium-Caliber, Large-Caliber), by Type (Guided, Target Sensing), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 25, 2026|Base Year : 2025|Pages : 234
The Programmable Ammunition Market is valued at USD 3.37 billion in 2025 and is projected to reach USD 5.69 billion by 2034, adding roughly USD 2.32 billion in incremental revenue over nine years.
Growth is procurement-cycle driven rather than speculative: a 5.99% CAGR tracks defence budget lines, not commercial volatility.
Programmable rounds now sit inside the Aerospace and Defense Market's counter-drone and short-range air-defense budgets, where fuze logic rather than warhead mass decides lethality.
Momentum Drivers
The XM1223 Multi-Mode Proximity Airburst (MMPA) effort, tied to US Manoeuvre-Short Range Air Defense Increment 3, is the most visible demand catalyst for the Counter-UAS Systems Market.
European stockpile replenishment (Rheinmetall AG, Nammo AS, JUNGHANS Microtec GmbH) plus Turkish and Israeli fuze lines have expanded capacity since 2023.
Medium-caliber demand outpaces large-caliber because 30–57 mm cannon systems are the default counter-drone effector on new armored and naval platforms.
Constraints to Watch
Unit economics: programmable airburst rounds cost 3–8x more than standard high-explosive rounds of identical caliber.
Export licensing under ITAR and the Wassenaar Arrangement adds 6–18 months to cross-border delivery cycles.
Fuze electronics rely on constrained inputs: tungsten powder, GaN RF components, and precision MEMS timing circuits.
Segment Snapshot
Dimension
Fastest-Growing Segment
Estimated Share of 2025 Value
Caliber
Medium-Caliber
~46%
Detonation Type
Time Programmable
~41%
Type
Guided
~29%
Segment Deep-Dive: Medium-Caliber Segment Dominance in Programmable Ammunition Market
Segment Analysis Matrix
Segment
Projected CAGR (%)
Market Share (%)
Key Demand Driver
Medium-Caliber (30–57 mm)
7.1%
46%
Counter-UAS airburst effectors on SHORAD and naval mounts
Large-Caliber (76–155 mm)
4.6%
38%
Artillery modernization and precision airburst for area suppression
Time Programmable (detonation type)
6.6%
41%
Accurate burst timing above or beside the target
Guided (type)
7.4%
29%
Precision defeat of moving and relocatable targets
Share percentages are measured within each dimension; caliber shares sum to 100% for the year, as do detonation-type and type shares.
Why Medium-Caliber Sets the Pace
The Medium-Caliber Ammunition Market is the primary revenue engine of the category. Three structural reasons explain the lead:
Feed-system compatibility. Programmable fuzes drop into existing 30x113 mm, 30x173 mm, 35 mm, 40 mm, and 57 mm cannon feed paths with limited platform modification, holding integration cost to an estimated 10–20% of a new weapon station.
Platform pull. Every new armored vehicle, SHORAD truck, and naval close-in mount purchased since 2020 is specified with an airburst-capable cannon.
Mission pull. The Airburst Ammunition Market grows fastest inside medium caliber because burst-range setting replaces precise aim, which matters against small, fast, low-signature drones.
Sub-Segment Dynamics
Time Programmable: largest detonation sub-segment at approximately 41% share; demand concentrated in naval CIWS and 40 mm L/70 air-defense mounts, including the upgraded Serbian Pasars-16 configuration.
Impact Self-Destruct: stable, range-compliance-driven volume; mandated for training in several NATO and EU member states to limit unexploded ordnance.
Proximity: the fastest area of overlap with the Counter-UAS Systems Market, using radio-frequency or optical fuzing to trigger on target proximity.
Remote Wireless: smallest and highest-margin sub-segment; also the most exposed to electronic-warfare jamming of fuze command links.
Margin Pressures
Fuze electronics represent 40–60% of round unit cost; MEMS oscillators and precision capacitors are frequently single-sourced.
Safety, insensitive-munitions, and environmental qualification consume 18–30 months, a fixed cost amortized over relatively small production lots.
Government multi-year awards trade unit margin for volume; suppliers recover through spares, fuze retrofits, and test-set sales.
Primary Market Drivers & Growth Restraints in Programmable Ammunition Market
Market Dynamics Impact Analysis
Factor Type
Description
Impact Level
Timeline
Driver
Small-UAS proliferation forces 30–57 mm airburst adoption on SHORAD and vehicle-mounted cannon
High
Short term
Driver
Allied budget expansion (2% GDP targets, several members moving to 3%) funds ammunition stockpile rebuilding through 2030
High
Medium term
Driver
Fuze retrofit into existing cannon feed systems cuts adoption cost versus new weapon station procurement
High
Short term
Driver
Guided and target-sensing types create premium price points and lift blended average selling price
Medium
Long term
Restraint
Programmable rounds priced at 3–8x conventional HE restrict use in high-volume suppression roles
High
Short term
Restraint
ITAR, Wassenaar Arrangement, and MTCR controls add 6–18 months to transfer timelines
Medium
Long term
Restraint
Tungsten powder and GaN feedstock concentration creates single-source dependency
Medium
Medium term
Restraint
Limited live-fire range and telemetry capacity constrains qualification throughput
Medium
Long term
Quantitative Read on Catalysts
The strongest catalyst is numeric: fielding of counter-drone ammunition across an installed base of tens of thousands of medium-caliber cannon systems. Within the Precision-Guided Munitions Market, programmable airburst rounds represent the lowest-cost per engagement option, typically USD 1,200–3,500 per round against tens of thousands for interceptors. That cost asymmetry sustains procurement even under budget pressure.
Where Growth Bottlenecks
In the Air Defense Systems Market, programmable rounds compete with missile interceptors for the same line items; ammunition usually wins on cost per shot but loses on range.
Qualification infrastructure is the binding constraint, not demand: test ranges and telemetry slots are booked out 12–24 months in several NATO states.
Component lead times for MEMS timing circuits and tungsten powder extend 6–12 months in tight markets.
40 mm and 57 mm programmable airburst rounds and fuzes
Land and naval programs
Leader
Rheinmetall AG
Medium-caliber cannon plus ammunition integration
European land forces
Leader
Northrop Grumman Corporation
Airburst and proximity fuze electronics, missile-defence payloads
US Department of Defense
Leader
Nammo AS
Nordic ammunition and fuze production, insensitive munitions
NATO customers
Leader
RTX Corporation
Proximity fuzes and guided projectile seekers
US and allied militaries
Leader
JUNGHANS Microtec GmbH
Precision mechanical and electronic fuzes
Artillery and mortar OEMs
Challenger
Leonardo S.p.A.
Naval gun mounts and programmable ammunition
Naval fleets
Challenger
Nexter Systems (KNDS)
40 mm airburst and vehicle weapon stations
French and German land programs
Challenger
General Dynamics Corporation
Medium-caliber ammunition production at scale
US Army
Challenger
ASELSAN A.Ş.
Airburst fuze and fire-control integration
Turkey and export markets
Niche
Fuchs Electronics (Pty) Ltd
Fuze electronic modules and safety devices
Fuze primes and integrators
Niche
Vendor Profiles
BAE Systems plc: holds a broad portfolio spanning 40 mm airburst, naval gun ammunition, and fuze electronics, giving it bundling leverage in multi-platform awards.
Rheinmetall AG: pairs cannon manufacturing with ammunition supply, which shortens integration risk for European buyers modernizing armored fleets.
Northrop Grumman Corporation: supplies fuze electronics and proximity sensing technology to US air-defense and counter-UAS programs.
Nammo AS: Nordic production base with strong insensitive-munitions credentials and growing NATO framework contract participation.
RTX Corporation: leverages guided-projectile seeker experience to compete in target-sensing and proximity fuze segments.
JUNGHANS Microtec GmbH: fuze specialist selling to artillery and mortar primes rather than directly to armed forces.
Leonardo S.p.A.: anchors the naval side of the market through 76 mm mounts and associated programmable ammunition.
Nexter Systems (KNDS): positions 40 mm airburst capability inside Franco-German vehicle programs.
General Dynamics Corporation: scale producer of medium-caliber ammunition, advantaged on unit cost for high-volume awards.
ASELSAN A.Ş.: vertically integrates fuze, fire control, and cannon for Turkish platforms and export customers.
Fuchs Electronics (Pty) Ltd: niche supplier of fuze electronic modules, dependent on prime contractor qualification cycles.
Strategic Milestones & Recent Developments in Programmable Ammunition Market
Latest Strategic Moves
Date
Company
Event Type
Impact
Sep 2023
Serbian Military Technical Institute (MTI)
Launch
Updated Pasars-16 self-propelled anti-aircraft system fielding a single-barrel 40 mm L/70 Bofors autocannon, expanding the addressable base for programmable 40 mm rounds
Apr 2023
US Army
Program Development
Announcement of the XM1223 Multi-Mode Proximity Airburst high-explosive proximity round for Manoeuvre-Short Range Air Defense Increment 3
2023–2025
NATO member states
Procurement Policy
Multi-year ammunition framework contracts convert spot demand into forecastable volume, supporting fuze line expansion
Development Detail
April 2023 — XM1223 MMPA. The US Army signaled intent to develop ammunition that can programmatically defeat small unmanned aircraft systems and ground vehicle targets. The round functions as a high-explosive proximity solution inside Manoeuvre-Short Range Air Defense Increment 3, which is the clearest single demand signal for the programmable category.
September 2023 — Pasars-16 iteration. Serbia's Military Technical Institute introduced an upgraded variant of its self-propelled anti-aircraft gun and missile system incorporating advanced weapon systems and a single-barrel 40 mm L/70 Bofors autocannon. The configuration requires programmable 40 mm ammunition, adding a European demand node outside the largest NATO buyers.
2023–2025 — Procurement restructuring. Replenishment contracts shifted from annual orders to multi-year frameworks, which lengthens backlog visibility for fuze suppliers but compresses per-unit pricing.
Structural read-through. Both 2023 events point the same direction: airburst and proximity functionality is being specified at the platform level, which forces ammunition suppliers into earlier design conversations.
Regional Market Analysis & Growth Corridors for Programmable Ammunition Market
Regional Growth Comparison
Region
Projected CAGR (%)
Base Year Valuation (2025)
Primary Catalyst
Regulatory Stringency
North America
5.2%
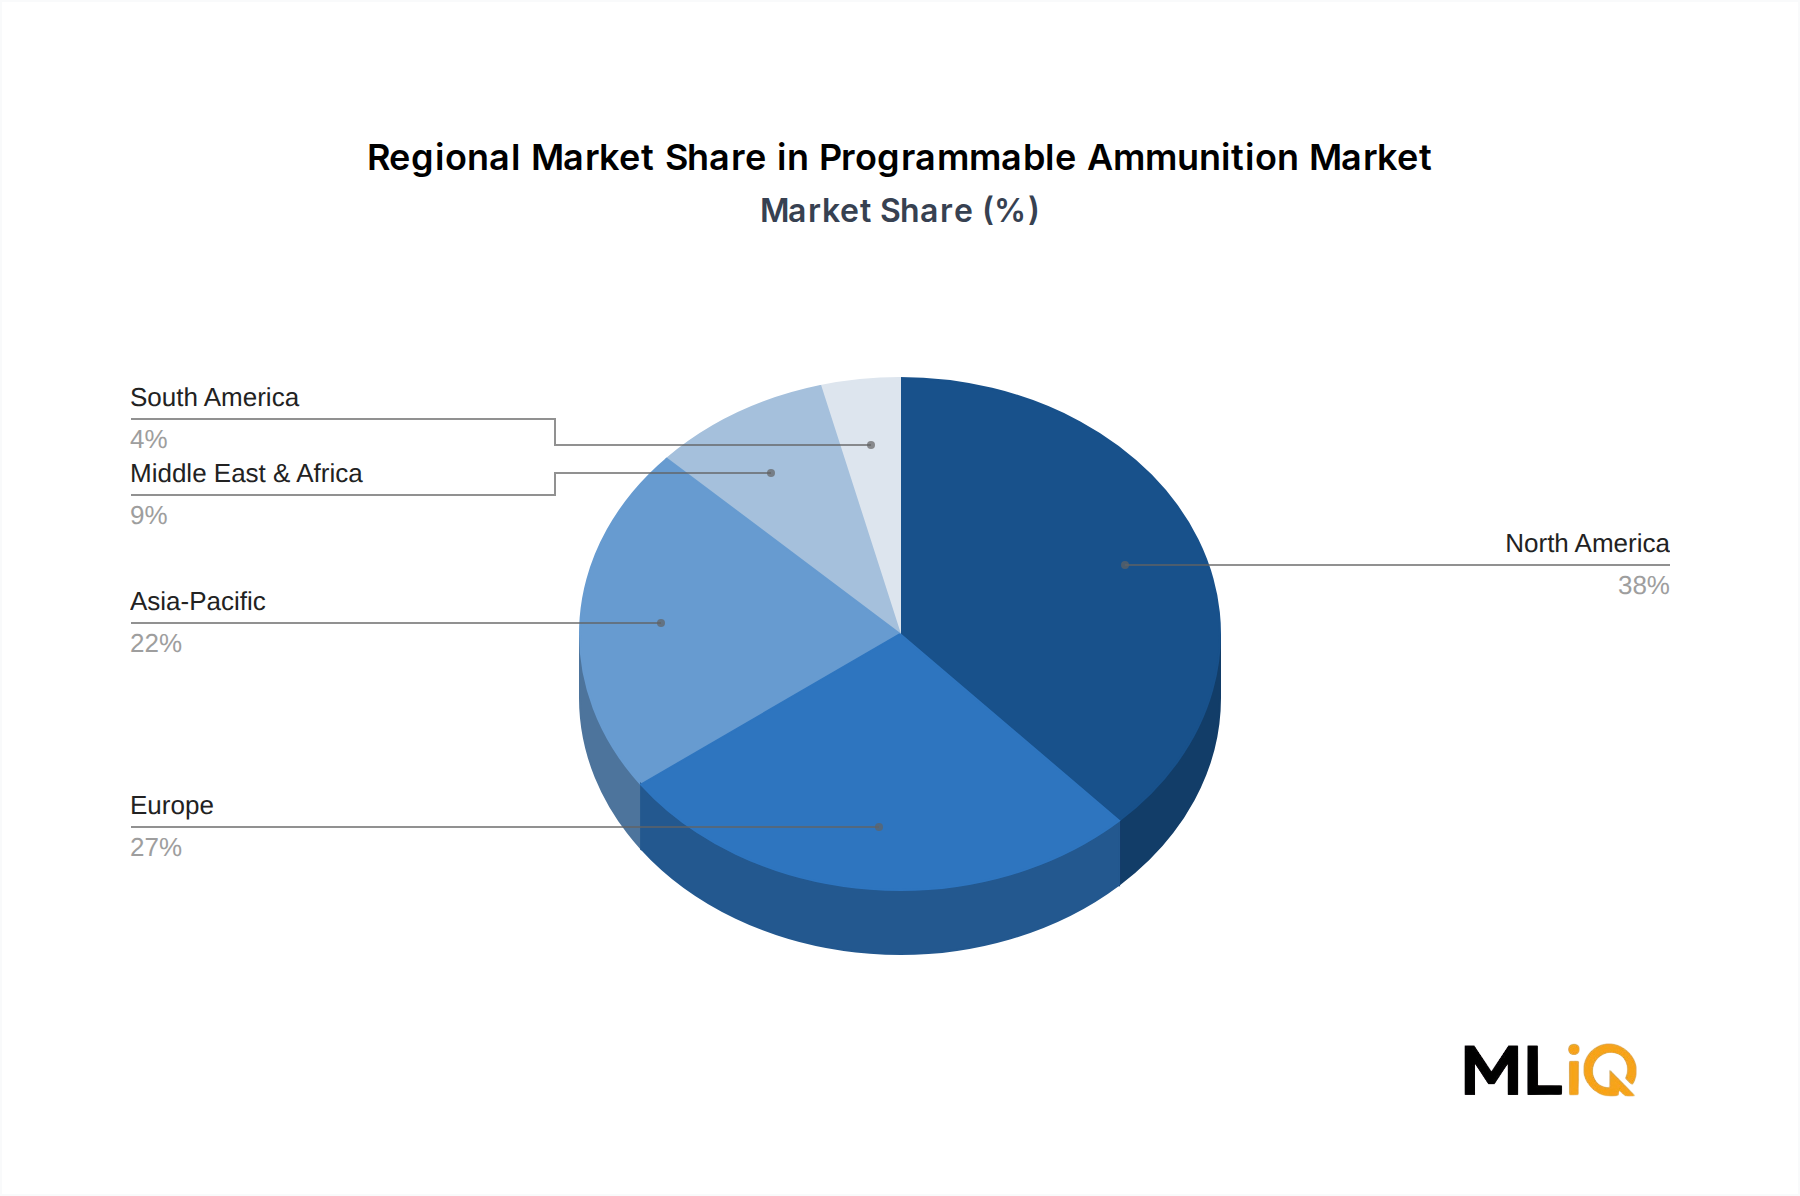
USD 1.15 billion
XM1223 MMPA, M-SHORAD Increment 3, 30×113 mm fleet sustainment
High (ITAR)
Europe
6.6%
USD 0.91 billion
Stockpile replenishment, 40 mm airburst, NATO framework contracts
High (EU dual-use and Wassenaar)
Asia-Pacific
6.9%
USD 0.81 billion
Indigenous fuze programs in China, South Korea, and India; naval expansion
Medium-High
LAMEA
5.1%
USD 0.50 billion
Import-led modernization in the GCC, Turkish local production, Brazilian programs
Medium
Fastest-Growing Versus Most Mature
Asia-Pacific (6.9% CAGR) is the fastest-growing corridor. South Korea and China both operate domestic fuze and medium-caliber production, which lowers import dependence and accelerates fielding cycles. India's artillery and air-defense modernization adds import volume on top of domestic development.
Europe (6.6% CAGR) is the fastest-growing high-value corridor. Replenishment of donated stockpiles and new 40 mm airburst specifications have reopened ammunition lines idled since the 1990s.
North America is the most mature and largest market at roughly USD 1.15 billion in 2025. Growth of 5.2% trails the global rate because the installed base is already airburst-capable; incremental revenue comes from inventory depth and guided-type upgrades.
LAMEA is the most price-sensitive region. Turkey functions as both producer and exporter through ASELSAN, while GCC states and Brazil remain import-driven, with volumes tied to individual modernization programs rather than standing demand.
Cross-regional pattern. The correlation between regional CAGR and domestic fuze capability is strong: regions with local fuze production grow 1.5 to 1.8 percentage points faster than purely import-dependent ones.
Technology Innovation & R&D Trajectory in Programmable Ammunition Market
Three technology families dominate development activity.
Solid-State Programmable Fuzing
MEMS-based timing circuits are replacing mechanical clockwork and pyrotechnic delay trains. Benefits include tighter burst-timing tolerance, lower part count, and the ability to reprogram the round at the breech rather than at the factory. The Electronic Fuze Market is where this shift is most visible, with vendors competing on timing accuracy, power draw, and resistance to shock loading above 30,000 g.
Multi-Mode Sensing
Proximity and target-sensing rounds combine radio-frequency, optical, and in some cases millimeter-wave sensing to trigger on target proximity regardless of aspect angle. These designs sit at the intersection of the Defense Electronics Market and traditional fuze engineering, and they require new qualification protocols because the fuze makes the engagement decision rather than the gunner.
Materials and Manufacturing
Additive manufacturing of fuze housings and tungsten-carbide liners is shortening prototype cycles, though it has not yet displaced pressed-and-sintered production for high-volume rounds. Adoption timelines are long: qualification for a new fuze typically runs 18 to 30 months, so technologies entering prototype in 2025 will reach fielded status around 2028–2029. Incumbent business models are reinforced rather than threatened, because qualification cost favours established suppliers with existing test infrastructure.
Export, Cross-Border Trade & Tariff Impact on Programmable Ammunition Market
Trade Corridors and Balance of Trade
Flow
Leading Participants
Characteristics
Net exporters
United States, Germany, Norway, Israel, Turkey, South Korea
Fuze and round technology exports under government-to-government approval
Net importers
India, Poland, GCC states, Brazil
Program-linked purchases, often bundled with platform procurement
Intra-alliance transfers
NATO and EU member states
Framework contracts, expedited licensing under emergency provisions
Barriers and Policy Effects
Tariffs are not the binding constraint. Ammunition lines typically carry 0–2% duties. The real friction is licensing: ITAR, the Wassenaar Arrangement, and MTCR controls add 6–18 months to transfers and can halt a sale entirely.
Critical-materials policy is becoming trade policy. Tungsten is central to the Tungsten Alloy Market and to penetrator and liner performance; China's roughly 80% share of global mine supply has pushed the United States and EU toward stockpiling and allied-sourcing mandates.
Emergency provisions shortened timelines selectively. Post-2022 replenishment transfers within NATO moved through expedited channels, compressing what is normally a multi-quarter approval process.
Non-tariff barriers favour incumbents. End-user certificates, offset requirements, and local-content thresholds in India and GCC procurement push exporters toward licensed local production rather than finished-round shipment.
Quantified policy impact. Licensing friction plausibly suppresses 8–12% of potential cross-border volume annually in the programmable segment, concentrated in guided and target-sensing types where technology-transfer controls are strictest.
Technology Innovation & Read-Through for Buyers
Procurement teams should treat fuze qualification capacity, not round demand, as the planning constraint for 2026–2030. Programs that begin fuze qualification in 2025 should expect fielding in the 2028–2029 window. Buyers that bundle fuze selection with cannon procurement reduce integration risk materially compared with retrofitting programmable rounds onto legacy feed systems later.
Outlook and Strategic Implications
Base case. The Programmable Ammunition Market reaches USD 5.69 billion by 2034 at a 5.99% CAGR, with medium-caliber rounds contributing close to half of total value across the forecast.
Upside case. Faster counter-drone fielding rates and earlier NATO stockpile targets could push the CAGR toward 7%.
Downside case. Relaxation of air-defense procurement urgency or successful low-cost drone countermeasures could hold growth near 4.5%.
Strategic priority. Vendors should invest in fuze electronics capacity and test-range throughput, because both are harder to scale than projectile assembly.
Programmable Ammunition Market Segmentation
1. Detonation Type
1.1. Time Programmable
1.2. Impact Self-Destruct
1.3. Proximity
1.4. Remote Wireless
2. Caliber
2.1. Medium-Caliber
2.2. Large-Caliber
3. Type
3.1. Guided
3.2. Target Sensing
Programmable Ammunition Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Programmable Ammunition Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 5.99% from 2020-2034
Segmentation
By Detonation Type
Time Programmable
Impact Self-Destruct
Proximity
Remote Wireless
By Caliber
Medium-Caliber
Large-Caliber
By Type
Guided
Target Sensing
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Detonation Type
5.1.1. Time Programmable
5.1.2. Impact Self-Destruct
5.1.3. Proximity
5.1.4. Remote Wireless
5.2. Market Analysis, Insights and Forecast - by Caliber
5.2.1. Medium-Caliber
5.2.2. Large-Caliber
5.3. Market Analysis, Insights and Forecast - by Type
5.3.1. Guided
5.3.2. Target Sensing
5.4. Market Analysis, Insights and Forecast - by Region
5.4.1. North America
5.4.2. South America
5.4.3. Europe
5.4.4. Middle East & Africa
5.4.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Detonation Type
6.1.1. Time Programmable
6.1.2. Impact Self-Destruct
6.1.3. Proximity
6.1.4. Remote Wireless
6.2. Market Analysis, Insights and Forecast - by Caliber
6.2.1. Medium-Caliber
6.2.2. Large-Caliber
6.3. Market Analysis, Insights and Forecast - by Type
6.3.1. Guided
6.3.2. Target Sensing
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Detonation Type
7.1.1. Time Programmable
7.1.2. Impact Self-Destruct
7.1.3. Proximity
7.1.4. Remote Wireless
7.2. Market Analysis, Insights and Forecast - by Caliber
7.2.1. Medium-Caliber
7.2.2. Large-Caliber
7.3. Market Analysis, Insights and Forecast - by Type
7.3.1. Guided
7.3.2. Target Sensing
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Detonation Type
8.1.1. Time Programmable
8.1.2. Impact Self-Destruct
8.1.3. Proximity
8.1.4. Remote Wireless
8.2. Market Analysis, Insights and Forecast - by Caliber
8.2.1. Medium-Caliber
8.2.2. Large-Caliber
8.3. Market Analysis, Insights and Forecast - by Type
8.3.1. Guided
8.3.2. Target Sensing
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Detonation Type
9.1.1. Time Programmable
9.1.2. Impact Self-Destruct
9.1.3. Proximity
9.1.4. Remote Wireless
9.2. Market Analysis, Insights and Forecast - by Caliber
9.2.1. Medium-Caliber
9.2.2. Large-Caliber
9.3. Market Analysis, Insights and Forecast - by Type
9.3.1. Guided
9.3.2. Target Sensing
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Detonation Type
10.1.1. Time Programmable
10.1.2. Impact Self-Destruct
10.1.3. Proximity
10.1.4. Remote Wireless
10.2. Market Analysis, Insights and Forecast - by Caliber
10.2.1. Medium-Caliber
10.2.2. Large-Caliber
10.3. Market Analysis, Insights and Forecast - by Type
10.3.1. Guided
10.3.2. Target Sensing
11. Competitive Analysis
11.1. Company Profiles
11.1.1. BAE Systems plc
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Rheinmetall AG
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Northrop Grumman Corporation
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Nammo AS
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. ASELSAN A Ş
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Fuchs Electronics (Pty) Ltd
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. JUNGHANS Microtec GmbH
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. RTX Corporation
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Nexter Systems (KNDS)
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Leonardo S p A
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.1.11. General Dynamics Corporatio
11.1.11.1. Company Overview
11.1.11.2. Products
11.1.11.3. Company Financials
11.1.11.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Programmable Ammunition Market Revenue Breakdown (billion, %) by Region 2026 & 2034
Figure 2: North America Programmable Ammunition Market Revenue (billion), by Detonation Type 2026 & 2034
Figure 3: North America Programmable Ammunition Market Revenue Share (%), by Detonation Type 2026 & 2034
Figure 4: North America Programmable Ammunition Market Revenue (billion), by Caliber 2026 & 2034
Figure 5: North America Programmable Ammunition Market Revenue Share (%), by Caliber 2026 & 2034
Figure 6: North America Programmable Ammunition Market Revenue (billion), by Type 2026 & 2034
Figure 7: North America Programmable Ammunition Market Revenue Share (%), by Type 2026 & 2034
Figure 8: North America Programmable Ammunition Market Revenue (billion), by Country 2026 & 2034
Figure 9: North America Programmable Ammunition Market Revenue Share (%), by Country 2026 & 2034
Figure 10: South America Programmable Ammunition Market Revenue (billion), by Detonation Type 2026 & 2034
Figure 11: South America Programmable Ammunition Market Revenue Share (%), by Detonation Type 2026 & 2034
Figure 12: South America Programmable Ammunition Market Revenue (billion), by Caliber 2026 & 2034
Figure 13: South America Programmable Ammunition Market Revenue Share (%), by Caliber 2026 & 2034
Figure 14: South America Programmable Ammunition Market Revenue (billion), by Type 2026 & 2034
Figure 15: South America Programmable Ammunition Market Revenue Share (%), by Type 2026 & 2034
Figure 16: South America Programmable Ammunition Market Revenue (billion), by Country 2026 & 2034
Figure 17: South America Programmable Ammunition Market Revenue Share (%), by Country 2026 & 2034
Figure 18: Europe Programmable Ammunition Market Revenue (billion), by Detonation Type 2026 & 2034
Figure 19: Europe Programmable Ammunition Market Revenue Share (%), by Detonation Type 2026 & 2034
Figure 20: Europe Programmable Ammunition Market Revenue (billion), by Caliber 2026 & 2034
Figure 21: Europe Programmable Ammunition Market Revenue Share (%), by Caliber 2026 & 2034
Figure 22: Europe Programmable Ammunition Market Revenue (billion), by Type 2026 & 2034
Figure 23: Europe Programmable Ammunition Market Revenue Share (%), by Type 2026 & 2034
Figure 24: Europe Programmable Ammunition Market Revenue (billion), by Country 2026 & 2034
Figure 25: Europe Programmable Ammunition Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Middle East & Africa Programmable Ammunition Market Revenue (billion), by Detonation Type 2026 & 2034
Figure 27: Middle East & Africa Programmable Ammunition Market Revenue Share (%), by Detonation Type 2026 & 2034
Figure 28: Middle East & Africa Programmable Ammunition Market Revenue (billion), by Caliber 2026 & 2034
Figure 29: Middle East & Africa Programmable Ammunition Market Revenue Share (%), by Caliber 2026 & 2034
Figure 30: Middle East & Africa Programmable Ammunition Market Revenue (billion), by Type 2026 & 2034
Figure 31: Middle East & Africa Programmable Ammunition Market Revenue Share (%), by Type 2026 & 2034
Figure 32: Middle East & Africa Programmable Ammunition Market Revenue (billion), by Country 2026 & 2034
Figure 33: Middle East & Africa Programmable Ammunition Market Revenue Share (%), by Country 2026 & 2034
Figure 34: Asia Pacific Programmable Ammunition Market Revenue (billion), by Detonation Type 2026 & 2034
Figure 35: Asia Pacific Programmable Ammunition Market Revenue Share (%), by Detonation Type 2026 & 2034
Figure 36: Asia Pacific Programmable Ammunition Market Revenue (billion), by Caliber 2026 & 2034
Figure 37: Asia Pacific Programmable Ammunition Market Revenue Share (%), by Caliber 2026 & 2034
Figure 38: Asia Pacific Programmable Ammunition Market Revenue (billion), by Type 2026 & 2034
Figure 39: Asia Pacific Programmable Ammunition Market Revenue Share (%), by Type 2026 & 2034
Figure 40: Asia Pacific Programmable Ammunition Market Revenue (billion), by Country 2026 & 2034
Figure 41: Asia Pacific Programmable Ammunition Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Programmable Ammunition Market Revenue billion Forecast, by Detonation Type 2020 & 2034
Table 52: Rest of Asia Pacific Programmable Ammunition Market Revenue (billion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Primary research accounts for 70–80% of total input; secondary desk research accounts for the remaining 20–30%. Findings from the two streams are reconciled before any figure enters the model.
Structured interviews and surveys were conducted with five company types across the programmable ammunition value chain: 40–57 mm medium-caliber airburst projectile integrators; electronic fuze and MEMS timing-circuit OEMs; multi-mode proximity and target-sensing payload developers; gun-launched guided projectile guidance-kit suppliers; and tungsten, tungsten-carbide, and specialty alloy material suppliers.
Stakeholder interviews targeted specific decision roles: Program Executive Officer, Short-Range Air Defense (SHORAD); Director of Fuze Electronics Engineering; Ammunition Program Procurement Manager, Land Systems; and Chief of Ballistics and Terminal Effects, Test and Evaluation Command.
Regulatory and standards consultation covered the National Defense Industrial Association (NDIA) ndia.org, the NATO Support and Procurement Agency (NSPA) nspa.nato.int, the European Defence Agency (EDA) eda.europa.eu, the Wassenaar Arrangement Secretariat wassenaar.org, and the US Directorate of Defense Trade Controls (DDTC) pmddtc.state.gov.
Response validation included re-contact of at least 15% of respondents to confirm segment-level volume and pricing statements.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Program Executive Officer, SHORAD
24%
Director of Fuze Electronics Engineering
26%
Ammunition Program Procurement Manager
28%
Chief of Ballistics & Terminal Effects, Test & Evaluation
Public and institutional sources include defence ministry budget documents and procurement notices (.gov), SIPRI arms transfer data sipri.org, NATO documentation nato.int, and trade association publications from NDIA and the Association of the United States Army ausa.org. Market research aggregator websites were deliberately excluded from the source set.
Company filings, investor presentations, and annual reports for BAE Systems plc, Rheinmetall AG, Northrop Grumman Corporation, Nammo AS, RTX Corporation, Leonardo S.p.A., Nexter Systems (KNDS), General Dynamics Corporation, ASELSAN A.Ş., JUNGHANS Microtec GmbH, and Fuchs Electronics (Pty) Ltd were benchmarked for segment revenue, backlog, and capital expenditure on fuze and ammunition lines.
Secondary findings are used to frame hypotheses and price bands, never as the sole basis for a reported valuation.
Every report is updated to the date of purchase, with any subsequent revision to base-year data reflected in the delivered file.
Demand Modeling & Market Estimation
Top-down and bottom-up methodologies are applied simultaneously. The top-down view starts from global defence ammunition spending and applies programmable-round share by caliber, while the bottom-up view builds volume from platform-level consumption and multiplies by verified unit pricing. The two estimates are reconciled through multi-level data triangulation at global, regional, segment, and sub-segment levels.
Bottom-up quantitative inputs include: annual medium-caliber and large-caliber programmable round procurement volumes by NATO and allied member state; the installed base of 30–57 mm cannon systems in active service by platform class; average fuze resupply and replacement cycle per firing unit, expressed in rounds per tube per year; and per-unit pricing of programmable airburst rounds by caliber and detonation type.
Segment builds are computed independently for Detonation Type (Time Programmable, Impact Self-Destruct, Proximity, Remote Wireless), Caliber (Medium-Caliber, Large-Caliber), and Type (Guided, Target Sensing), then cross-checked against regional totals for North America, South America, Europe, the Middle East and Africa, and Asia Pacific.
Currency effects, defence budget escalation indices, and order backlog conversion rates are applied as overlays rather than embedded in baseline growth rates.
Data Accuracy & Quality Check
The research process carries a guaranteed estimated data accuracy level of 85–90%, supported by source triangulation and respondent re-verification.
Quality checks include: variance testing between top-down and bottom-up outputs at each segment node; rejection of any segment estimate deviating more than 12% from the triangulated midpoint; and consistency review of pricing assumptions against contracted award values.
Each data point is traced to at least two independent sources, with at least one being primary where the segment exceeds 10% of total market value.
Reports are refreshed to the purchase date; where a revision changes a base-year valuation by more than 3%, the affected segment and regional tables are recalculated rather than adjusted proportionally.
Frequently Asked Questions
1. Which region leads the Programmable Ammunition Market and why?
North America holds the largest share at roughly 34% of 2025 global value, equivalent to about USD 1.15 billion. Leadership rests on funded US programs such as the XM1223 Multi-Mode Proximity Airburst round for Manoeuvre-Short Range Air Defense Increment 3 and the fielding of 30x113 mm and 40 mm airburst ammunition across Stryker and naval mounts. Europe is the fastest-closing region at a projected 6.6% CAGR as NATO stockpile targets are rebuilt.
2. How do sustainability and ESG requirements affect programmable ammunition production?
Environmental scrutiny concentrates on tungsten powder handling, lead-based priming compounds, and range contamination from unexploded ordnance. Impact self-destruct fuzes are now mandatory on many training ranges in Germany, Norway, and the United States specifically to cut UXO remediation costs and soil contamination. Insensitive munitions qualification, which reduces unintended detonation risk in storage and transport, has become a standard ESG-adjacent procurement criterion in EU defence tenders.
3. How are purchasing behaviours shifting among defence buyers?
Buyers are moving from single-year spot purchases to multi-year framework contracts and indefinite-delivery vehicles that trade price for guaranteed production capacity. NATO members committing 2% of GDP to defence, with several moving toward 3%, have shifted ammunition line items from training stocks to operational reserves. There is also a shift away from unitary high-explosive rounds toward multi-mode programmable rounds that perform airburst, point-detonate, and delay functions from a single inventory item.
4. What disruptive technologies could reshape this market?
MEMS-based electronic timing circuits and multi-mode proximity airburst fuzes are the core disruptors, replacing mechanical clockwork fuzes at lower unit cost and higher reliability. Radio-frequency and optical proximity sensing, combined with small radar or lidar target-sensing payloads, allow a single round to classify and engage drones without external targeting updates. Additive manufacturing of fuze housings and tungsten-carbide liners is shortening development cycles, though qualification timelines of 18 to 30 months still gate adoption.
5. Which raw materials dominate the supply chain and where are the risks?
Tungsten, tungsten carbide, copper, and specialty steels dominate projectile and penetrator content, while fuze electronics depend on gallium for GaN RF components and rare-earth elements in sensors and actuators. China accounts for roughly 80% of global tungsten mine supply, creating a single-point concentration that defence ministries in the United States and EU have flagged in critical-materials reviews. Qualified second-source suppliers outside China remain limited, extending lead times for tungsten powder to 6 to 12 months in tight markets.
6. What do export-import dynamics look like for programmable ammunition?
The market is dominated by a small group of net exporters: the United States, Germany, Norway, Israel, Turkey, and South Korea, with Norway's Nammo and Germany's JUNGHANS Microtec and Rheinmetall supplying fuze and round technology worldwide. Major importers include India, Poland, the GCC states, and Brazil, where domestic fuze capability is still developing. Tariffs on ammunition are typically low, between 0% and 2%, but non-tariff barriers such as ITAR licensing, the Wassenaar Arrangement, and end-user certificate requirements add 6 to 18 months to cross-border transfers.