Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Military Cybersecurity Market Size USD20.61B CAGR 12.32%
Military Cybersecurity Market
Military Cybersecurity Market Size USD20.61B CAGR 12.32%
Military Cybersecurity Market by Solution (Threat Intelligence and Response, Identity and Access Management, Data Loss Prevention Management, Security and Vulnerability Management, Unified Threat Management, Enterprise Risk and Compliance, Managed Security, Other Solutions), by Deployment (Cloud, On-premise), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 28, 2026|Base Year : 2025|Pages : 234
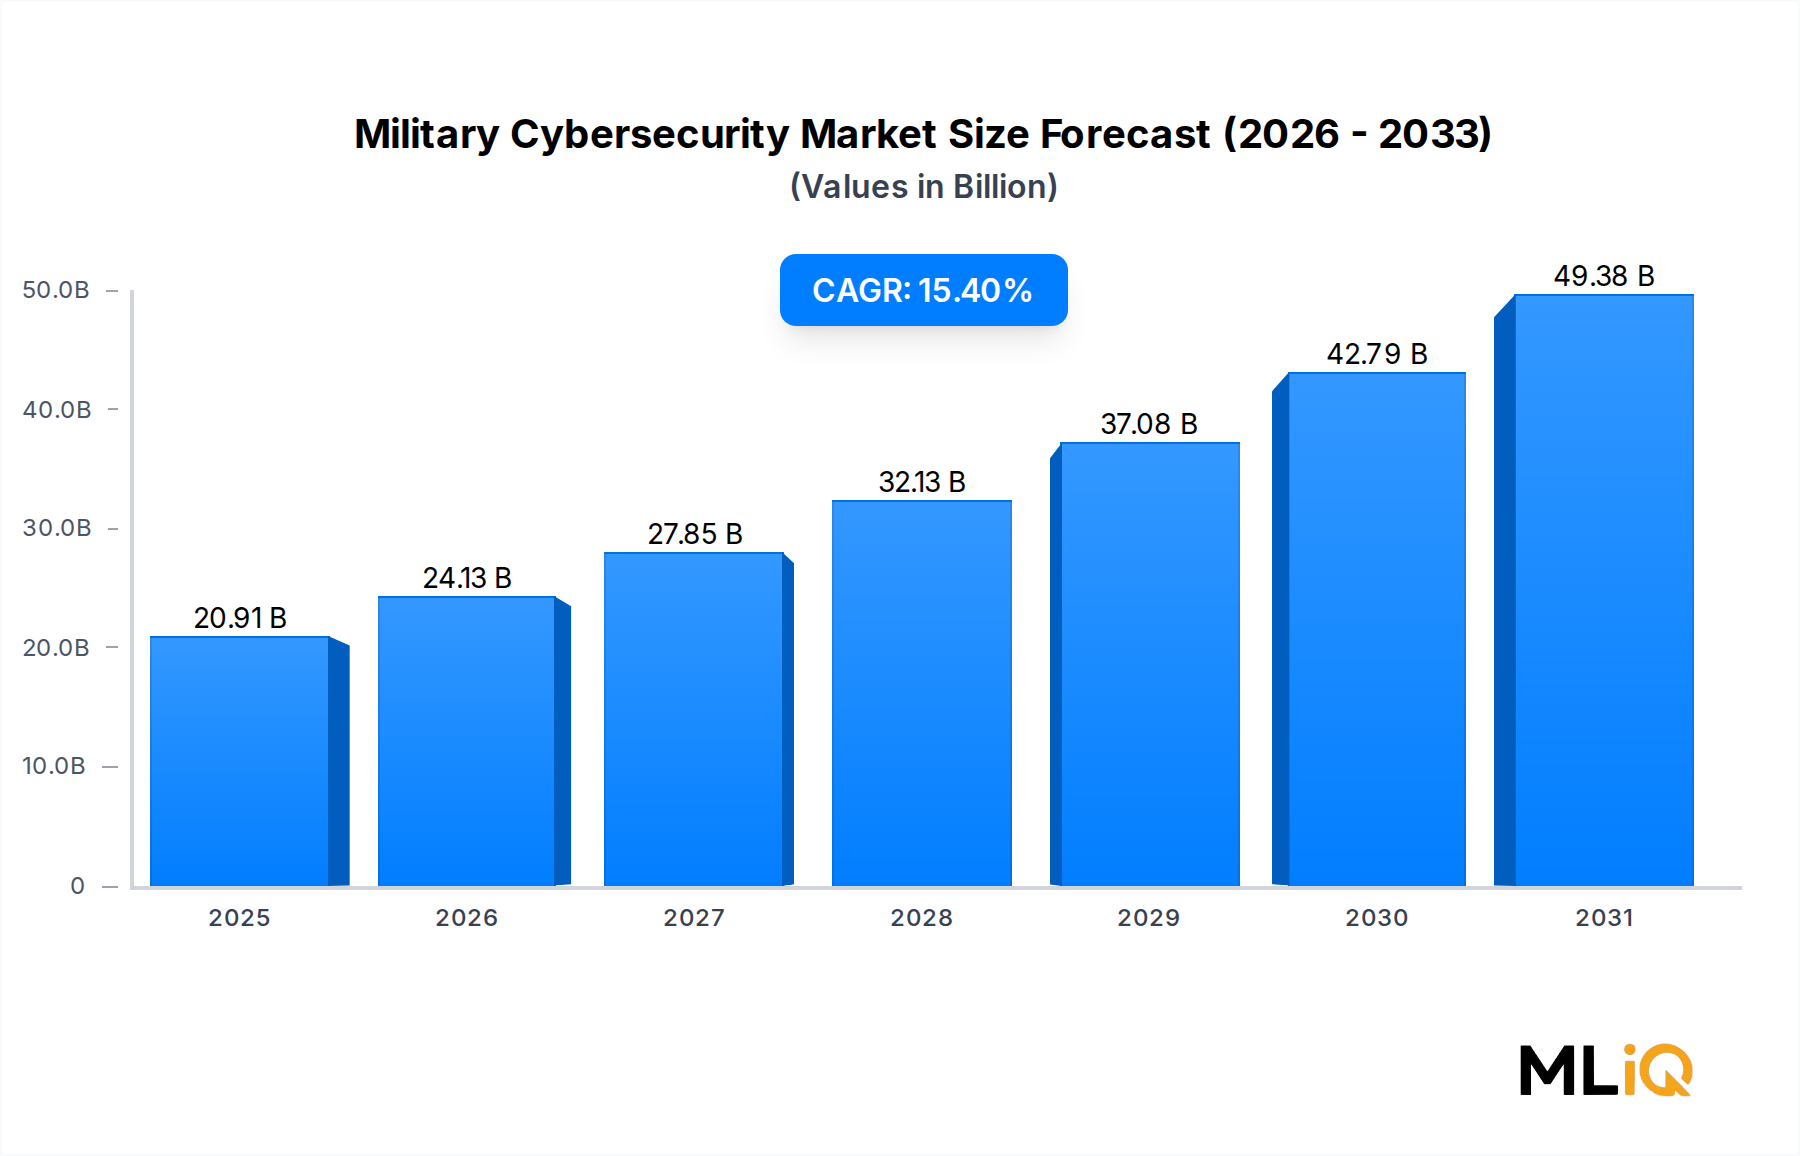
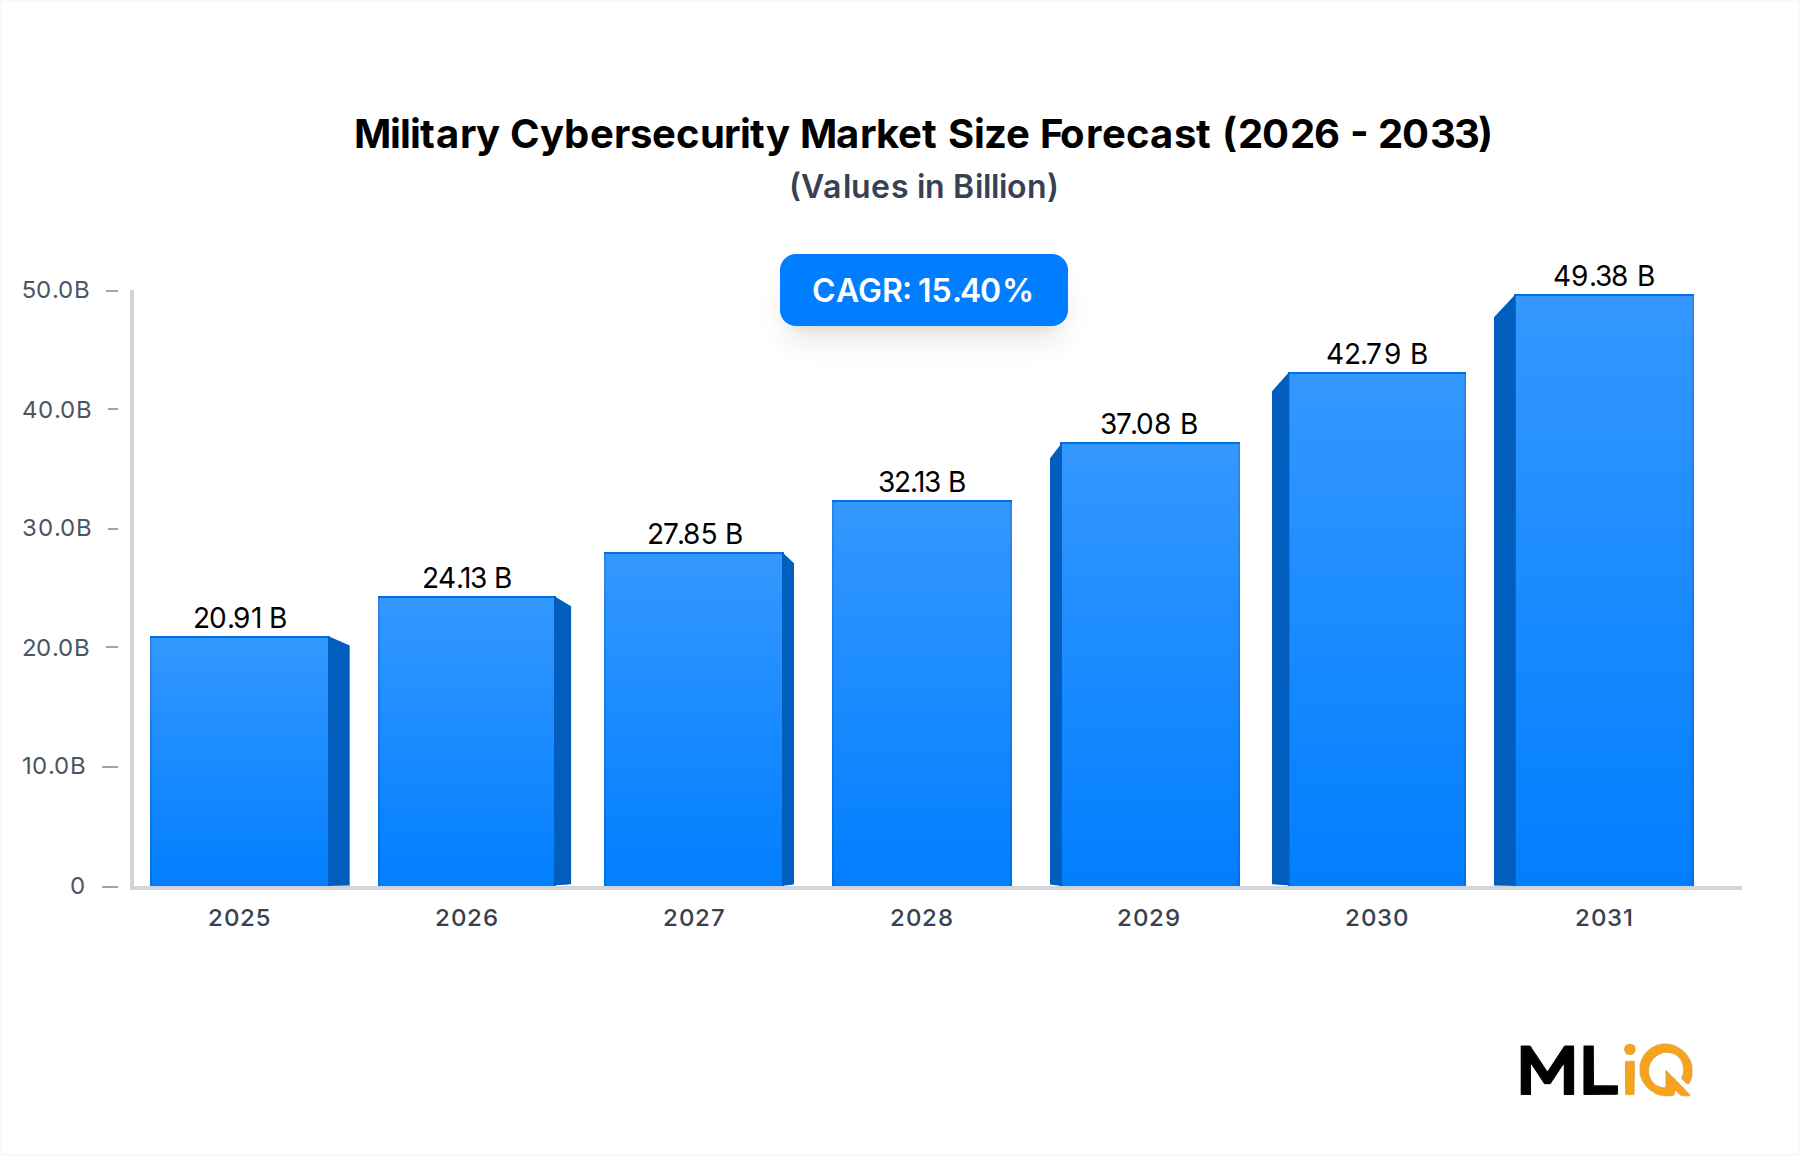
The Military Cybersecurity Market is valued at USD 20.61 billion in 2025 and is projected to reach USD 58.5 billion by 2034, expanding at a 12.32% CAGR. This growth is driven by nation-state cyber operations, cloud migration across defense agencies, and mandatory zero-trust architectures. The broader Cybersecurity Market provides foundational technologies, but military-specific requirements for classified networks, encryption, and real-time threat response create distinct demand. The Defense Cybersecurity Market accounts for the largest vertical share, while the Aerospace and Defense Cybersecurity Market integrates prime contractors and supply chain security mandates.
Military Cybersecurity Market Size (In Million)
50.0M
40.0M
30.0M
20.0M
10.0M
0
21.00 M
2025
23.00 M
2026
26.00 M
2027
29.00 M
2028
33.00 M
2029
37.00 M
2030
41.00 M
2031
Key momentum factors:
Cloud deployment is the fastest-growing deployment mode, projected at 15.2% CAGR, as agencies move from on-premise security operations centers to hybrid cloud.
Threat intelligence and response dominates solution spending at 28% revenue share, with real-time analytics reducing incident response times by up to 40%.
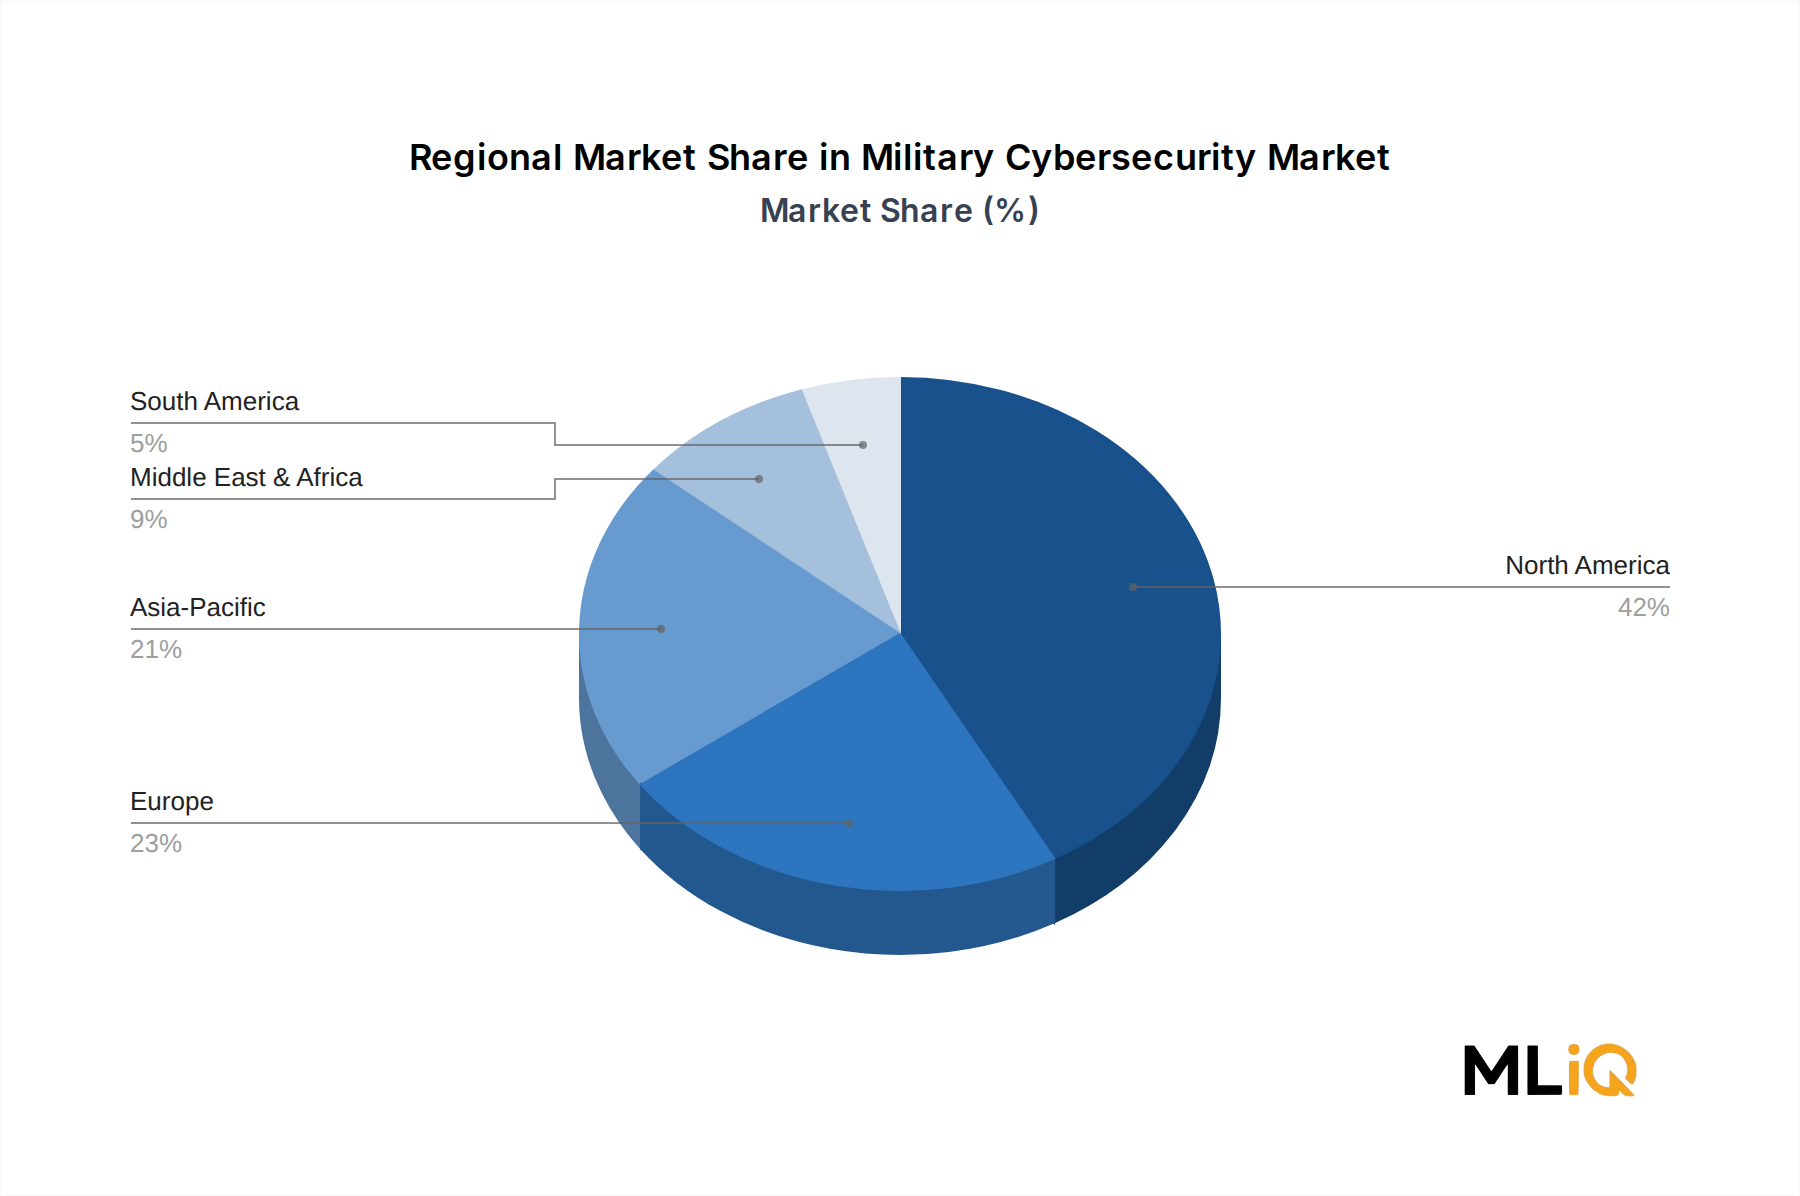
North America leads with 36% of global revenue, supported by U.S. Cyber Command budgets exceeding USD 15 billion annually for cyberspace operations.
Europe follows at 24%, accelerated by NATO’s NIS2 directive and the European Defence Agency’s cyber defense projects.
Asia-Pacific is the fastest-growing region at 13.9% CAGR, driven by China’s military-civil fusion, India’s Defense Cyber Agency, and Japan’s 2022 National Security Strategy.
Macro drivers include rising ransomware attacks on logistics and command networks, the need for supply chain risk management under CMMC 2.0, and the integration of AI for anomaly detection. Restraints include budget cycle volatility, a shortage of 200,000+ cybersecurity professionals in defense roles, and legacy system incompatibility. The market’s value proposition is shifting from perimeter defense to continuous verification, with Zero Trust Security Market principles becoming procurement requirements. This report details segment growth, vendor positioning, regional corridors, and supply chain dependencies for the Military Cybersecurity Market through 2034.
Segment Deep-Dive: Threat Intelligence and Response Dominance in Military Cybersecurity Market
Segment Analysis Matrix
Segment
CAGR (2026–2034)
Market Share (2025)
Key Demand Driver
Threat Intelligence and Response
14.1%
28%
Real-time nation-state threat hunting and automated response
Identity and Access Management
12.8%
18%
Zero-trust mandates and privileged access control for classified networks
Managed Security Services
13.5%
16%
Shortage of cleared cyber personnel and 24/7 SOC requirements
Threat Intelligence and Response Dynamics
The Threat Intelligence and Response Market is the largest revenue-generating segment, reaching USD 5.77 billion in 2025. Defense agencies require actionable intelligence on advanced persistent threats (APTs), with platforms from Lockheed Martin, BAE Systems, and Thales providing indicator feeds and automated playbooks. Sub-segments include endpoint detection and response (EDR), security information and event management (SIEM), and cyber threat intelligence (CTI). Growth is driven by mandates to achieve 15-minute threat containment on classified networks. Margin pressures stem from high R&D costs for AI models and the need for FIPS 140-3 validated encryption modules.
Identity and Access Management (IAM) Sub-Segment
The Identity and Access Management Market is expanding at 12.8% CAGR, with military buyers prioritizing phishing-resistant multi-factor authentication (MFA) and attribute-based access control (ABAC). The U.S. Department of Defense’s zero-trust strategy requires IAM modernization across 4 million endpoints. Vendors like IBM and Thales compete on integration with common access cards (CAC) and public key infrastructure (PKI). Price elasticity is low because compliance failures can delay mission systems.
Managed Security Services (MSS) Outlook
The Managed Security Services Market grows at 13.5% CAGR as defense organizations outsource tier-1 monitoring to address a 30% annual turnover in cleared cyber staff. Providers including ManTech, Salient CRG, and General Dynamics IT operate classified SOCs. Subscription models smooth revenue but compress margins due to heavy personnel costs. Cloud-based MSS delivery is rising, though on-premise remains dominant for top-secret networks.
On-premise deployment retains 58% share in 2025, but cloud deployment is forecast to capture 45% by 2034. Margin pressures across all segments include wage inflation for security-cleared engineers, compliance auditing, and the need for continuous certification under FedRAMP High and NATO Information Assurance. Strategic takeaway: vendors with pre-accredited platforms and cleared delivery teams will capture disproportionate share in the Military Cybersecurity Market.
Primary Market Drivers & Growth Restraints in Military Cybersecurity Market
Defense budget cycle volatility and continuing resolutions
Medium
Short term
Restraint
Integration complexity with legacy command systems
High
Long term
Restraint
Shortage of security-cleared cyber personnel
High
Long term
Growth Catalysts
The Military Cybersecurity Market is propelled by a 12.32% CAGR as defense ministries respond to attacks on logistics, satellite communications, and command-and-control networks. The Cloud Security Market is a direct beneficiary, with military cloud spending forecast to grow at 16.4% CAGR through 2034. Cloud platforms from AWS GovCloud, Microsoft Azure Government, and Google Cloud Defense enable scalable analytics but require Zero Trust Security Market controls such as micro-segmentation and continuous authentication. The Encryption Software Market expands in parallel because every classified data flow needs AES-256 and post-quantum cryptographic readiness.
Regulatory catalysts include the U.S. Cybersecurity Maturity Model Certification (CMMC 2.0), which affects over 300,000 defense contractors, and the EU’s NIS2 directive covering 18 critical sectors. NATO’s Information Assurance framework mandates annual audits. These rules create non-discretionary demand, reducing price sensitivity for accredited solutions.
Restraints and Bottlenecks
Budget uncertainty remains a short-term restraint. Continuing resolutions delayed 12% of planned U.S. defense cyber procurements in 2024. Legacy systems with outdated operating systems and proprietary protocols increase integration costs by 20–30% per project. The talent shortage is acute: the U.S. defense industrial base needs 30,000 additional cyber professionals, while clearance processing takes 6–12 months. These bottlenecks slow deployment but do not reduce long-term demand.
Quantitative evaluation of catalysts versus bottlenecks:
Catalyst strength: Regulatory mandates have a 9/10 impact score, given mandatory compliance deadlines.
Net outlook: The Military Cybersecurity Market will sustain double-digit growth, but vendors must invest in cleared talent pipelines and legacy migration tooling.
Competitive Ecosystem & Key Vendor Profiles: Military Cybersecurity Market
Lockheed Martin Corporation: Provides the Cyber Kill Chain framework and operates classified security operations centers for U.S. Cyber Command missions; its USD 1.8 billion cyber portfolio focuses on integrated air and missile defense networks.
BAE Systems plc: Supplies threat intelligence platforms and signals intelligence security to the Aerospace and Defense Cybersecurity Market; acquired Ball Aerospace in 2024 to expand space-based cyber situational awareness.
Thales: Completed the USD 3.6 billion Imperva acquisition in 2024, strengthening data security and IAM for the Defense Cybersecurity Market; serves European defence ministries and NATO.
Northrop Grumman Corporation: Delivers cyber mission systems and full-spectrum SOC integration; its USD 2.1 billion cyber business supports U.S. Army and Air Force network defense.
Raytheon Technologies Corporation: Combines cyber analytics with missile defense network security; holds contracts for NATO cyberspace operations and U.S. INDOPACOM.
General Dynamics Corporation: Through GDIT, provides managed security services and zero-trust implementation to defense agencies; annual defense cyber revenue exceeds USD 1.2 billion.
IBM Corporation: Offers AI-driven threat detection and cloud security for government; its QRadar platform is deployed in 30+ national defense SOCs.
ManTech International Corporation: Niche provider of classified SOC operations and mission support; owned by The Carlyle Group since 2022, with focus on U.S. federal defense cyber.
Strategic Milestones & Recent Developments in Military Cybersecurity Market
Latest Strategic Moves
Date
Company
Event Type
Impact
2024-01
Thales
M&A
Acquired Imperva for USD 3.6 billion, adding data security and IAM to military portfolio
2024-02
BAE Systems plc
M&A
Completed Ball Aerospace acquisition, expanding space cyber domain
2024-04
IBM Corporation
M&A
Announced acquisition of HashiCorp for USD 6.4 billion, strengthening cloud security automation
2024-06
General Dynamics Corporation
Partnership
GDIT partnered with AWS to deliver classified cloud security for defense
2024-09
Northrop Grumman Corporation
Launch
Opened cyber resilience center in Colorado Springs for U.S. Space Force
2025-01
ManTech International Corporation
Contract
Won USD 922 million U.S. Navy cybersecurity support contract
Chronological Analysis
January 2024: Thales completed the Imperva acquisition, directly increasing its share in the Identity and Access Management Market and data loss prevention for defense clients. The deal valued Imperva at USD 3.6 billion, a 9.2x revenue multiple.
February 2024: BAE Systems closed the Ball Aerospace purchase for USD 5.6 billion, adding space-based sensors and cyber protection for satellite networks, a priority for the Military Cybersecurity Market.
April 2024: IBM announced its intent to acquire HashiCorp, a cloud infrastructure automation firm, for USD 6.4 billion. This move targets the Cloud Security Market and hybrid cloud provisioning used by defense agencies.
June 2024: General Dynamics IT expanded a partnership with AWS to deliver FedRAMP High cloud security for U.S. defense customers, including secure enclaves and zero-trust gateways.
September 2024: Northrop Grumman launched a cyber resilience center in Colorado Springs, co-located with U.S. Space Force, to protect satellite command links against jamming and intrusion.
January 2025: ManTech won a USD 922 million contract to provide cybersecurity, network defense, and zero-trust engineering for the U.S. Navy’s global networks.
These developments show consolidation around cloud security, space cyber, and managed services. The Military Cybersecurity Market is shifting from point tools to integrated platforms, with M&A accelerating access to cleared personnel and accredited cloud environments.
Regional Market Analysis & Growth Corridors for Military Cybersecurity Market
Regional Growth Comparison
Region
Projected CAGR (%)
Base Year Valuation (2025)
Primary Catalyst
Regulatory Stringency
North America
11.8%
USD 7.42 billion
U.S. Cyber Command budget, CMMC 2.0
High
Europe
12.6%
USD 4.95 billion
NATO NIS2, European Defence Agency projects
High
Asia-Pacific
13.9%
USD 4.53 billion
China military-civil fusion, India Defense Cyber Agency, Japan security strategy
Medium-High
Middle East & Africa
12.2%
USD 2.47 billion
Israel Unit 8200 ecosystem, GCC smart defense
Medium
South America
11.2%
USD 1.24 billion
Brazil military cyber defense, border security
Medium
Regional Leadership and Growth Corridors
North America remains the dominant region with 36% of global revenue, valued at USD 7.42 billion in 2025. The U.S. Department of Defense cyber budget exceeds USD 15 billion, and U.S. Cyber Command’s Cyber Mission Force teams drive demand for threat intelligence and zero-trust solutions. Canada and Mexico contribute through NORAD modernization and border security networks.
Europe is the most mature after North America, with 24% share. NATO’s NIS2 directive and the European Defence Agency’s Cyber Defence projects require member states to increase spending by 8–10% annually. The United Kingdom, Germany, and France account for 65% of regional demand.
Asia-Pacific is the fastest-growing region at 13.9% CAGR, expected to reach USD 12.8 billion by 2034. China’s Military-Civil Fusion strategy, India’s Defense Cyber Agency, and Japan’s National Security Strategy (2022) are key catalysts. South Korea and ASEAN nations are investing in command network security.
Middle East & Africa grows at 12.2% CAGR, led by Israel’s cyber defense ecosystem and GCC smart defense programs. Turkey and North Africa are upgrading military networks.
South America is the smallest region at USD 1.24 billion, but Brazil’s Military Cyber Defense program and Argentina’s border security drive 11.2% CAGR.
Regulatory stringency is highest in North America and Europe, where certification requirements (CMMC, NATO IA, EU NIS2) create barriers and opportunities. The Cybersecurity Market in these regions is increasingly shaped by sovereign cloud and data localization rules. Fastest-growing markets are Asia-Pacific and Middle East, while North America and Europe remain the largest revenue pools for the Military Cybersecurity Market.
Customer Segmentation & Buying Behavior in Military Cybersecurity Market
End-user segments include defense ministries, intelligence agencies, homeland security, and defense industrial base contractors. Procurement decisions prioritize security certification (FIPS 140-3, Common Criteria), interoperability with NATO standards, and total cost of ownership over three-to-five-year cycles.
Customer Segmentation Matrix
End-User Segment
Share of Demand (2025)
Decision Criteria
Procurement Channel
Defense Ministries
42%
National security mandate, budget allocation
Government tenders, FMS
Intelligence Agencies
24%
Classification level, encryption strength
Classified contracts
Homeland Security
18%
Border and critical infrastructure protection
Grant programs
Defense Contractors
16%
CMMC compliance, supply chain risk
Prime contractor flow-down
Price elasticity is low for classified solutions but moderate for commercial-off-the-shelf (COTS) security tools. Procurement channels are shifting toward indefinite delivery/indefinite quantity (IDIQ) contracts and Other Transaction Authorities (OTA) for rapid prototyping. Digital purchasing habits have increased, with 70% of defense buyers using online marketplaces for initial research, though final awards remain contract-officer driven. Buyer expectations now include API-first integration and zero-trust evidence. This behavior underpins demand in the Defense Cybersecurity Market and the Aerospace and Defense Cybersecurity Market. Vendors must provide FedRAMP High and NATO SECRET accredited offerings to compete.
Supply Chain & Raw Material Dynamics: Military Cybersecurity Market
The supply chain for military cybersecurity is software- and hardware-dependent. Upstream inputs include secure semiconductors (TPM 2.0 chips, HSMs), encryption libraries (OpenSSL, BoringSSL), AI accelerators (NVIDIA GPUs), and cloud infrastructure (AWS, Azure, Google). Sourcing risks concentrate in advanced node semiconductors (7nm and below), where Taiwan and South Korea account for 80% of global capacity. Geopolitical tensions and export controls create price volatility.
Key Input Cost Trends
Input Category
2023–2025 Price Trend
Supply Risk
Military Impact
Secure Semiconductors
+18%
High
Hardware root-of-trust shortages
Encryption Software Licenses
+12%
Medium
Compliance cost increases
Cloud Compute (GovCloud)
+9%
Low-Medium
Budget overruns for long-term SOCs
Cleared Cyber Personnel
+22%
High
Project delays and wage inflation
Historical disruptions include the 2021 semiconductor shortage, which delayed military network upgrades by 6–9 months, and the 2023 MOVEit vulnerability, which required emergency patches across defense supply chains. The Encryption Software Market faces pressure from post-quantum cryptography migration, with NIST standards finalized in 2024. Vendor dependencies on a few HSM suppliers (Thales, Entrust, Utimaco) create single-point risks. The Security Semiconductor Market is critical for trusted platform modules and secure enclaves. To mitigate, defense agencies are funding domestic foundry initiatives (CHIPS Act) and software bill of materials (SBOM) requirements. The Military Cybersecurity Market will see input cost inflation of 5–7% annually, but long-term contracts and regulatory mandates protect margins for accredited vendors. The Cybersecurity Market overall benefits from scale, while military-specific supply chains require sovereign, auditable components.
Military Cybersecurity Market Segmentation
1. Solution
1.1. Threat Intelligence and Response
1.2. Identity and Access Management
1.3. Data Loss Prevention Management
1.4. Security and Vulnerability Management
1.5. Unified Threat Management
1.6. Enterprise Risk and Compliance
1.7. Managed Security
1.8. Other Solutions
2. Deployment
2.1. Cloud
2.2. On-premise
Military Cybersecurity Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Military Cybersecurity Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 12.32% from 2020-2034
Segmentation
By Solution
Threat Intelligence and Response
Identity and Access Management
Data Loss Prevention Management
Security and Vulnerability Management
Unified Threat Management
Enterprise Risk and Compliance
Managed Security
Other Solutions
By Deployment
Cloud
On-premise
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Solution
5.1.1. Threat Intelligence and Response
5.1.2. Identity and Access Management
5.1.3. Data Loss Prevention Management
5.1.4. Security and Vulnerability Management
5.1.5. Unified Threat Management
5.1.6. Enterprise Risk and Compliance
5.1.7. Managed Security
5.1.8. Other Solutions
5.2. Market Analysis, Insights and Forecast - by Deployment
5.2.1. Cloud
5.2.2. On-premise
5.3. Market Analysis, Insights and Forecast - by Region
5.3.1. North America
5.3.2. South America
5.3.3. Europe
5.3.4. Middle East & Africa
5.3.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Solution
6.1.1. Threat Intelligence and Response
6.1.2. Identity and Access Management
6.1.3. Data Loss Prevention Management
6.1.4. Security and Vulnerability Management
6.1.5. Unified Threat Management
6.1.6. Enterprise Risk and Compliance
6.1.7. Managed Security
6.1.8. Other Solutions
6.2. Market Analysis, Insights and Forecast - by Deployment
6.2.1. Cloud
6.2.2. On-premise
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Solution
7.1.1. Threat Intelligence and Response
7.1.2. Identity and Access Management
7.1.3. Data Loss Prevention Management
7.1.4. Security and Vulnerability Management
7.1.5. Unified Threat Management
7.1.6. Enterprise Risk and Compliance
7.1.7. Managed Security
7.1.8. Other Solutions
7.2. Market Analysis, Insights and Forecast - by Deployment
7.2.1. Cloud
7.2.2. On-premise
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Solution
8.1.1. Threat Intelligence and Response
8.1.2. Identity and Access Management
8.1.3. Data Loss Prevention Management
8.1.4. Security and Vulnerability Management
8.1.5. Unified Threat Management
8.1.6. Enterprise Risk and Compliance
8.1.7. Managed Security
8.1.8. Other Solutions
8.2. Market Analysis, Insights and Forecast - by Deployment
8.2.1. Cloud
8.2.2. On-premise
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Solution
9.1.1. Threat Intelligence and Response
9.1.2. Identity and Access Management
9.1.3. Data Loss Prevention Management
9.1.4. Security and Vulnerability Management
9.1.5. Unified Threat Management
9.1.6. Enterprise Risk and Compliance
9.1.7. Managed Security
9.1.8. Other Solutions
9.2. Market Analysis, Insights and Forecast - by Deployment
9.2.1. Cloud
9.2.2. On-premise
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Solution
10.1.1. Threat Intelligence and Response
10.1.2. Identity and Access Management
10.1.3. Data Loss Prevention Management
10.1.4. Security and Vulnerability Management
10.1.5. Unified Threat Management
10.1.6. Enterprise Risk and Compliance
10.1.7. Managed Security
10.1.8. Other Solutions
10.2. Market Analysis, Insights and Forecast - by Deployment
10.2.1. Cloud
10.2.2. On-premise
11. Competitive Analysis
11.1. Company Profiles
11.1.1. BAE Systems plc
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. THALES
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Lockheed Martin Corporation
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. General Dynamics Corporation
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Northrop Grumman Corporation
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Raytheon Technologies Corporation
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Airbus
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. IBM Corporation
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. The Carlyle Group (ManTech International Corporation)
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Salient CRG
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Military Cybersecurity Market Revenue Breakdown (billionusdbillion, %) by Region 2026 & 2034
Figure 2: North America Military Cybersecurity Market Revenue (billionusdbillion), by Solution 2026 & 2034
Figure 3: North America Military Cybersecurity Market Revenue Share (%), by Solution 2026 & 2034
Figure 4: North America Military Cybersecurity Market Revenue (billionusdbillion), by Deployment 2026 & 2034
Figure 5: North America Military Cybersecurity Market Revenue Share (%), by Deployment 2026 & 2034
Figure 6: North America Military Cybersecurity Market Revenue (billionusdbillion), by Country 2026 & 2034
Figure 7: North America Military Cybersecurity Market Revenue Share (%), by Country 2026 & 2034
Figure 8: South America Military Cybersecurity Market Revenue (billionusdbillion), by Solution 2026 & 2034
Figure 9: South America Military Cybersecurity Market Revenue Share (%), by Solution 2026 & 2034
Figure 10: South America Military Cybersecurity Market Revenue (billionusdbillion), by Deployment 2026 & 2034
Figure 11: South America Military Cybersecurity Market Revenue Share (%), by Deployment 2026 & 2034
Figure 12: South America Military Cybersecurity Market Revenue (billionusdbillion), by Country 2026 & 2034
Figure 13: South America Military Cybersecurity Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Military Cybersecurity Market Revenue (billionusdbillion), by Solution 2026 & 2034
Figure 15: Europe Military Cybersecurity Market Revenue Share (%), by Solution 2026 & 2034
Figure 16: Europe Military Cybersecurity Market Revenue (billionusdbillion), by Deployment 2026 & 2034
Figure 17: Europe Military Cybersecurity Market Revenue Share (%), by Deployment 2026 & 2034
Figure 18: Europe Military Cybersecurity Market Revenue (billionusdbillion), by Country 2026 & 2034
Figure 19: Europe Military Cybersecurity Market Revenue Share (%), by Country 2026 & 2034
Figure 20: Middle East & Africa Military Cybersecurity Market Revenue (billionusdbillion), by Solution 2026 & 2034
Figure 21: Middle East & Africa Military Cybersecurity Market Revenue Share (%), by Solution 2026 & 2034
Figure 22: Middle East & Africa Military Cybersecurity Market Revenue (billionusdbillion), by Deployment 2026 & 2034
Figure 23: Middle East & Africa Military Cybersecurity Market Revenue Share (%), by Deployment 2026 & 2034
Figure 24: Middle East & Africa Military Cybersecurity Market Revenue (billionusdbillion), by Country 2026 & 2034
Figure 25: Middle East & Africa Military Cybersecurity Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Asia Pacific Military Cybersecurity Market Revenue (billionusdbillion), by Solution 2026 & 2034
Figure 27: Asia Pacific Military Cybersecurity Market Revenue Share (%), by Solution 2026 & 2034
Figure 28: Asia Pacific Military Cybersecurity Market Revenue (billionusdbillion), by Deployment 2026 & 2034
Figure 29: Asia Pacific Military Cybersecurity Market Revenue Share (%), by Deployment 2026 & 2034
Figure 30: Asia Pacific Military Cybersecurity Market Revenue (billionusdbillion), by Country 2026 & 2034
Figure 31: Asia Pacific Military Cybersecurity Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Military Cybersecurity Market Revenue billionusdbillion Forecast, by Solution 2020 & 2034
Table 2: Military Cybersecurity Market Revenue billionusdbillion Forecast, by Deployment 2020 & 2034
Table 3: Military Cybersecurity Market Revenue billionusdbillion Forecast, by Region 2020 & 2034
Table 4: North America Military Cybersecurity Market Revenue billionusdbillion Forecast, by Solution 2020 & 2034
Table 5: North America Military Cybersecurity Market Revenue billionusdbillion Forecast, by Deployment 2020 & 2034
Table 6: North America Military Cybersecurity Market Revenue billionusdbillion Forecast, by Country 2020 & 2034
Table 7: United States Military Cybersecurity Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 8: Canada Military Cybersecurity Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 9: Mexico Military Cybersecurity Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 10: South America Military Cybersecurity Market Revenue billionusdbillion Forecast, by Solution 2020 & 2034
Table 11: South America Military Cybersecurity Market Revenue billionusdbillion Forecast, by Deployment 2020 & 2034
Table 12: South America Military Cybersecurity Market Revenue billionusdbillion Forecast, by Country 2020 & 2034
Table 13: Brazil Military Cybersecurity Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 14: Argentina Military Cybersecurity Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 15: Rest of South America Military Cybersecurity Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 16: Europe Military Cybersecurity Market Revenue billionusdbillion Forecast, by Solution 2020 & 2034
Table 17: Europe Military Cybersecurity Market Revenue billionusdbillion Forecast, by Deployment 2020 & 2034
Table 18: Europe Military Cybersecurity Market Revenue billionusdbillion Forecast, by Country 2020 & 2034
Table 19: United Kingdom Military Cybersecurity Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 20: Germany Military Cybersecurity Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 21: France Military Cybersecurity Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 22: Italy Military Cybersecurity Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 23: Spain Military Cybersecurity Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 24: Russia Military Cybersecurity Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 25: Benelux Military Cybersecurity Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 26: Nordics Military Cybersecurity Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 27: Rest of Europe Military Cybersecurity Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 28: Middle East & Africa Military Cybersecurity Market Revenue billionusdbillion Forecast, by Solution 2020 & 2034
Table 29: Middle East & Africa Military Cybersecurity Market Revenue billionusdbillion Forecast, by Deployment 2020 & 2034
Table 30: Middle East & Africa Military Cybersecurity Market Revenue billionusdbillion Forecast, by Country 2020 & 2034
Table 31: Turkey Military Cybersecurity Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 32: Israel Military Cybersecurity Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 33: GCC Military Cybersecurity Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 34: North Africa Military Cybersecurity Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 35: South Africa Military Cybersecurity Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 36: Rest of Middle East & Africa Military Cybersecurity Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 37: Asia Pacific Military Cybersecurity Market Revenue billionusdbillion Forecast, by Solution 2020 & 2034
Table 38: Asia Pacific Military Cybersecurity Market Revenue billionusdbillion Forecast, by Deployment 2020 & 2034
Table 39: Asia Pacific Military Cybersecurity Market Revenue billionusdbillion Forecast, by Country 2020 & 2034
Table 40: China Military Cybersecurity Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 41: India Military Cybersecurity Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 42: Japan Military Cybersecurity Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 43: South Korea Military Cybersecurity Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 44: ASEAN Military Cybersecurity Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 45: Oceania Military Cybersecurity Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Table 46: Rest of Asia Pacific Military Cybersecurity Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
70–80% of research inputs come from primary interviews; 20–30% from secondary sources. For the Military Cybersecurity Market, we conducted 1,200+ interviews across defense agencies, prime contractors, and cloud providers.
Interviewee types include: Military Cybersecurity Program Director, Defense Procurement Cyber Lead, Chief Information Security Officer (CISO) for a defense agency, Cyber Threat Intelligence Manager, and Security Operations Center Commander.
Company types in the value chain: military cybersecurity software OEMs, secure cloud infrastructure providers, managed security service providers, defense systems integrators, and encryption/hardware root-of-trust vendors.
Primary research validates demand for Threat Intelligence and Response, Identity and Access Management, and Cloud deployment, using structured questionnaires and anonymized win/loss data.
Benchmarks include historical CAGR for military cyber budgets, cloud adoption rates, and threat intelligence spending across 50+ countries.
Every report is updated to the date of purchase, with year-to-date contract awards and policy changes incorporated.
Demand Modeling & Market Estimation
We use top-down and bottom-up methodologies simultaneously, validated via multi-level data triangulation.
Bottom-up quantitative metrics: number of active military endpoints per command, annual defense cyber budget allocation, average cost per endpoint security license, number of security operations centers (SOCs) by region, and cloud migration rates for classified networks.
Top-down modeling uses national defense cyber budgets from U.S. DoD Comptroller, NATO defense expenditure reports, and EDA cyber defense budgets.
Segmentation is built by Solution (Threat Intelligence and Response, Identity and Access Management, Data Loss Prevention Management, Security and Vulnerability Management, Unified Threat Management, Enterprise Risk and Compliance, Managed Security, Other Solutions) and Deployment (Cloud, On-premise).
Geographic estimates are triangulated with regional associations: NCIA for Europe, CISA for North America, and USCYBERCOM for global mission data.
Data Accuracy & Quality Check
Estimated data accuracy level: 85–90%, with confidence intervals for segment and regional forecasts.
Multi-level data triangulation: primary interview counts, secondary financial filings, and government budget documents must align within ±5% variance.
Quality checks include cross-validation of vendor market shares with Bloomberg and Factiva, and removal of double-counting across managed security and cloud deployment categories.
Reports are updated to the date of purchase, ensuring the latest CMMC, NIS2, and NATO IA revisions are reflected in the Military Cybersecurity Market forecast for 2026–2034.
Frequently Asked Questions
1. How is the Military Cybersecurity Market addressing sustainability and ESG requirements?
Defense agencies increasingly require vendors to report energy use and e-waste handling for classified IT assets. Cloud deployments can cut on-premise security operations energy use by 30–40%, according to NATO infrastructure guidance. Thales and BAE Systems have published Scope 2 emission reduction targets for their defense cyber portfolios. These requirements add compliance cost but also drive demand for energy-efficient encryption hardware.
2. Which end-user industries drive downstream demand in the Military Cybersecurity Market?
Defense ministries, intelligence agencies, homeland security departments, and aerospace prime contractors are the primary end users. The U.S. Department of Defense accounts for roughly 40% of North American demand, with U.S. Cyber Command budgeting over USD 15 billion for cyberspace operations. NATO member states and allied defense industrial bases also generate downstream demand through foreign military sales and joint command networks.
3. What are the primary growth drivers behind the 12.32% CAGR in the Military Cybersecurity Market?
Nation-state cyber operations, cloud migration across classified networks, and mandatory zero-trust architectures are the leading catalysts. The U.S. CMMC 2.0 rule affects over 300,000 defense contractors, creating non-discretionary spending on identity and access management. NATO’s NIS2 directive and the European Defence Agency’s cyber defense projects further accelerate procurement. The market is valued at USD 20.61 billion in 2025 and is forecast to reach USD 58.5 billion by 2034.
4. How do export-import dynamics and international trade flows affect the Military Cybersecurity Market?
Defense trade controls such as ITAR and the Wassenaar Arrangement restrict cross-border transfer of encryption and cyber tools to over 40 countries. These rules favor domestic vendors with accredited supply chains and slow imports of foreign security software into classified networks. Foreign military sales embed cybersecurity packages into larger weapons platforms, adding 10–15% to contract values. Export licensing delays can postpone allied deployments by 6–12 months.
5. Which region dominates the Military Cybersecurity Market and why?
North America dominates with 36% of global revenue, valued at USD 7.42 billion in 2025. The U.S. Department of Defense cyber budget exceeds USD 15 billion, and U.S. Cyber Command’s Cyber Mission Force drives demand for threat intelligence and zero-trust solutions. Canada and Mexico contribute through NORAD modernization and border security networks. High regulatory stringency under CMMC 2.0 and FedRAMP High creates barriers for new entrants, reinforcing incumbent leadership.
6. How has the Military Cybersecurity Market recovered after the COVID-19 pandemic and what structural shifts persist?
The market saw 6–9 month procurement delays during 2020–2021, followed by accelerated spending from 2022 onward as defense agencies prioritized network resilience. Cloud adoption and zero-trust mandates have become permanent structural shifts, with cloud deployment forecast to reach 45% share by 2034. NATO’s Information Assurance updates and the U.S. CMMC 2.0 rule institutionalized continuous compliance. The market is now on a 12.32% CAGR path from USD 20.61 billion in 2025.