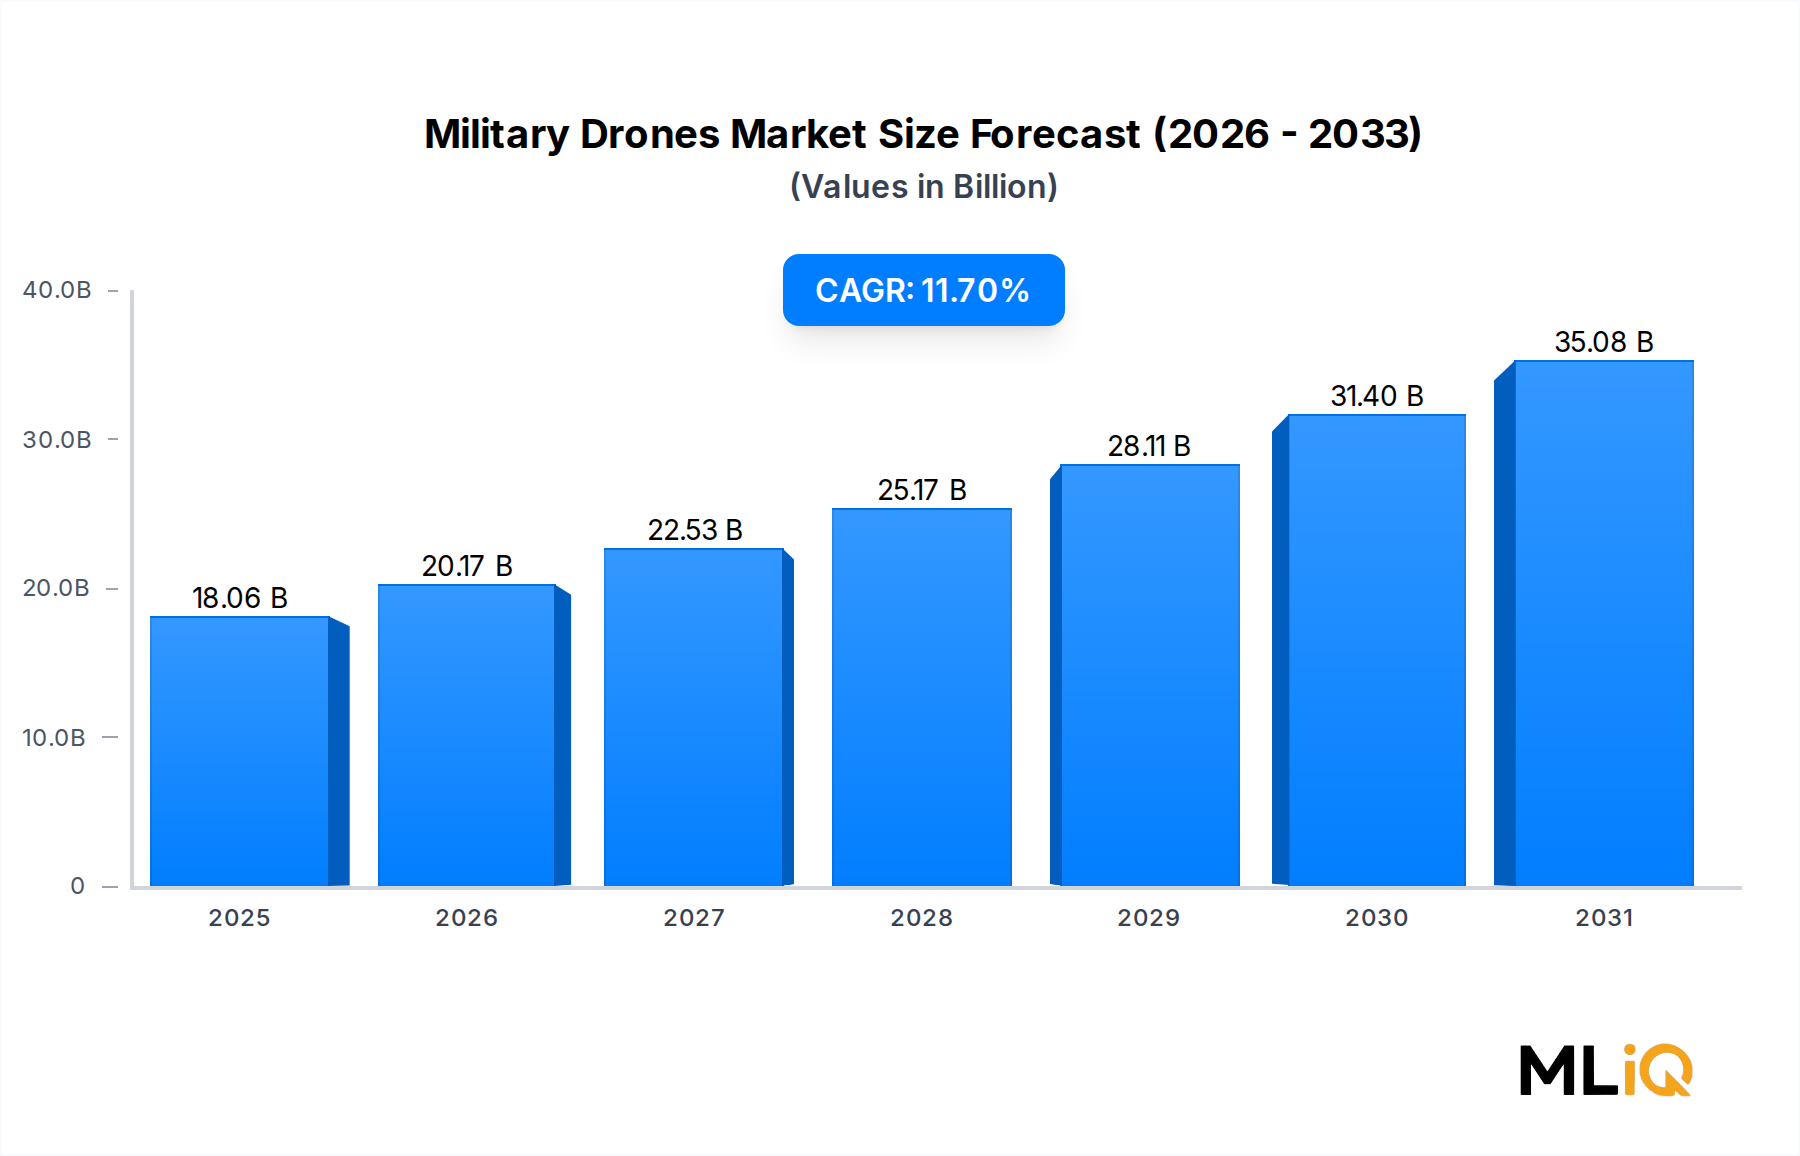
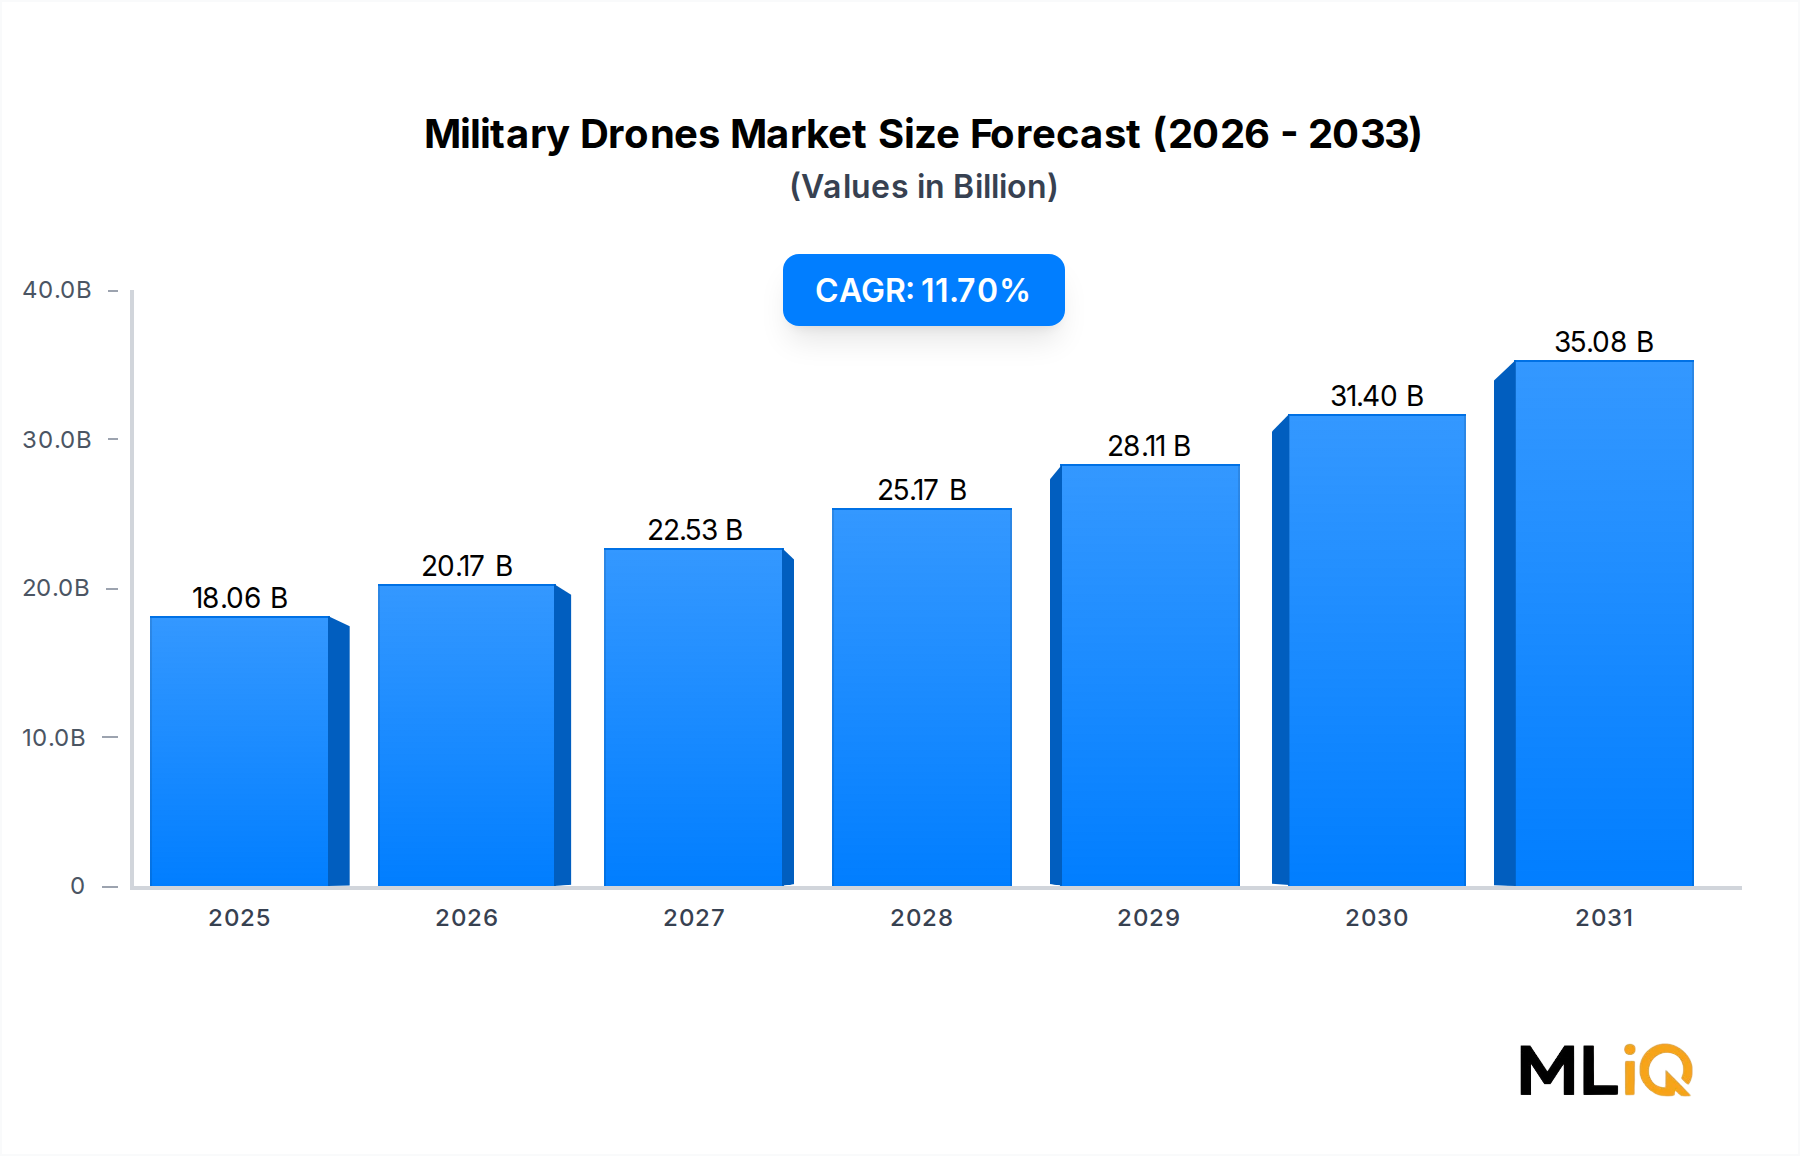
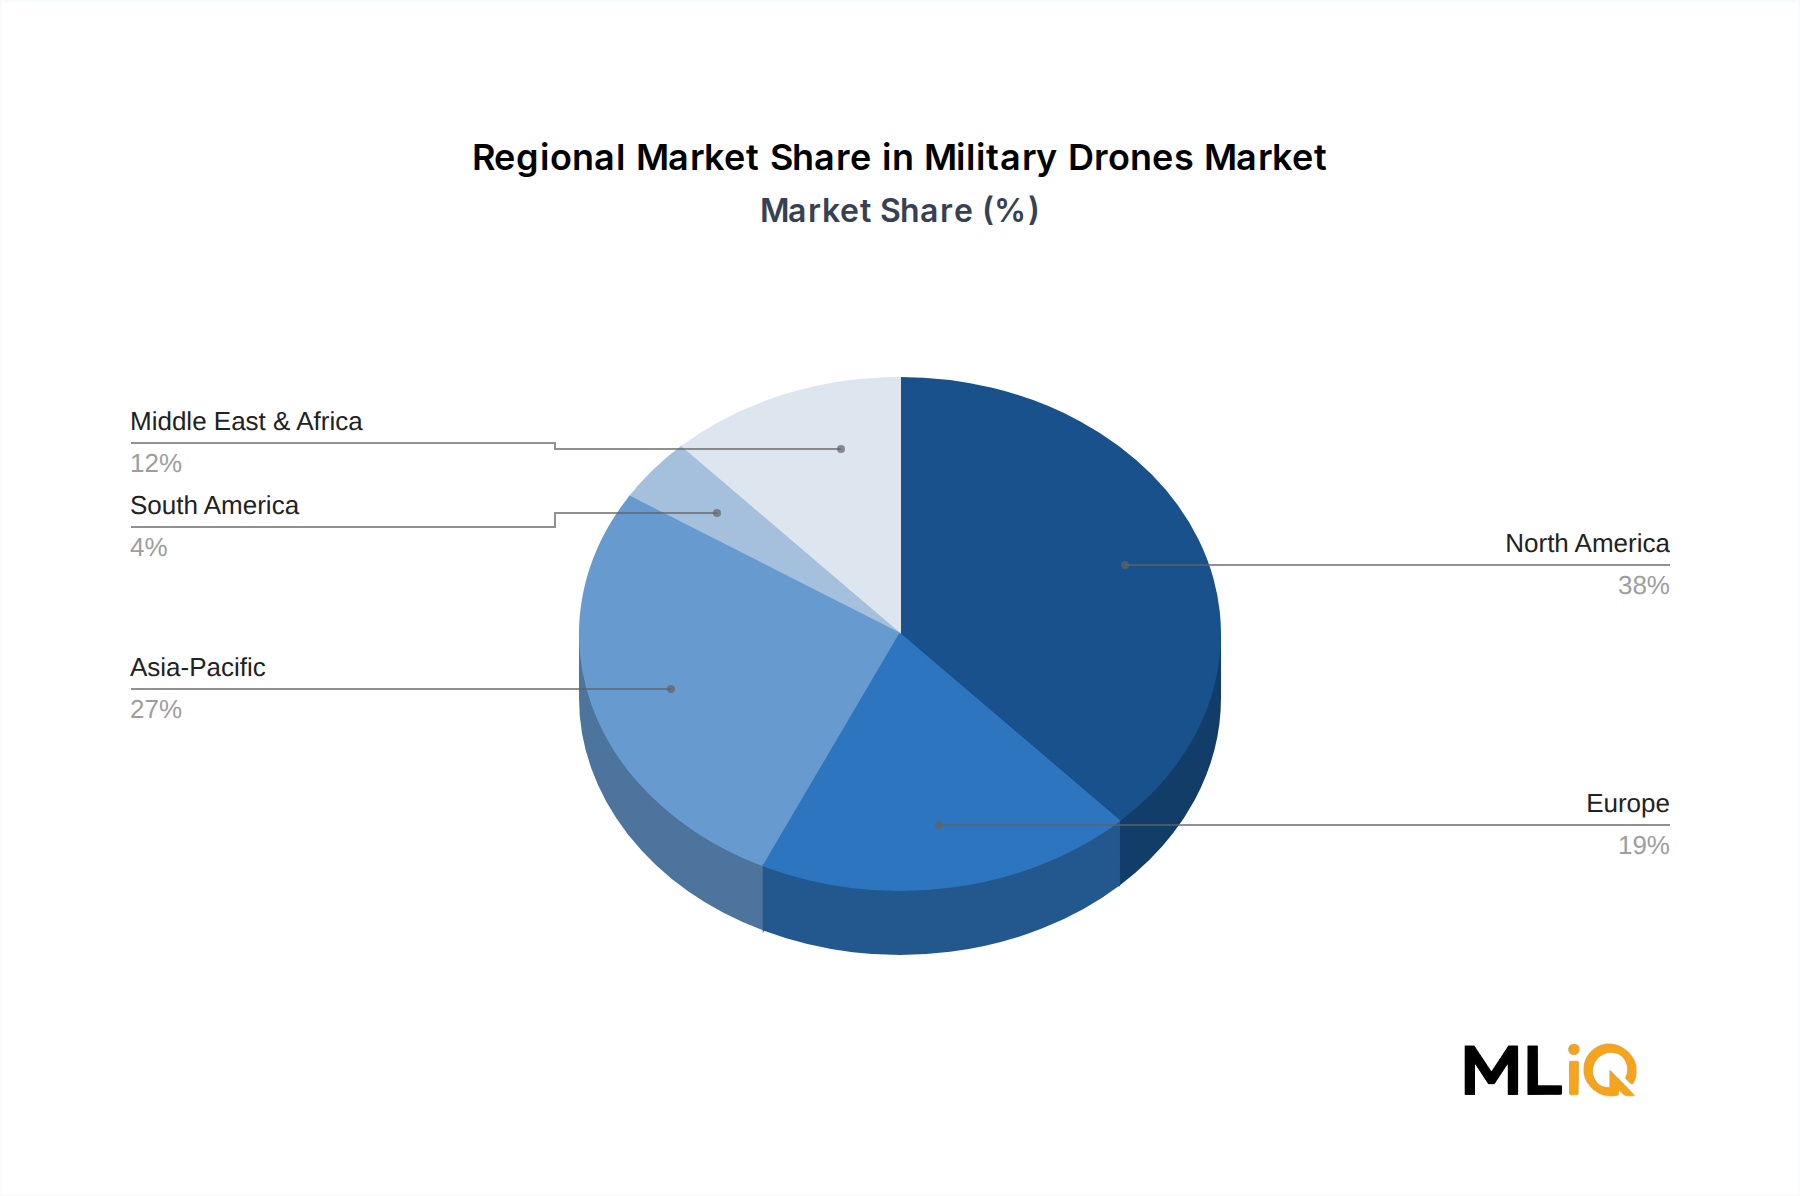
The Military Drones Market exhibits pronounced regional heterogeneity, with demand intensity shaped by threat environment, procurement maturity, and domestic industrial capability.
North America represents the largest single regional revenue pool, accounting for an estimated 38–42% of global market value. The United States remains the world's preeminent investor in military drone technology, sustaining procurement across strategic, operational, and tactical tiers simultaneously. The U.S. Air Force, Navy, and Army each maintain active multi-billion dollar drone acquisition portfolios, and the Replicator Initiative has added incremental urgency to near-term procurement velocity. Canada and Mexico contribute modestly, with Canadian procurement centered on maritime patrol and Arctic surveillance applications.
Asia-Pacific is the fastest-growing regional market, expected to sustain a regional CAGR meaningfully above the global average through the forecast period. China's People's Liberation Army has emerged as the world's second-largest drone operator by fleet size, with an extensive domestically developed capability spanning tactical, MALE, and stealth UCAV categories. India is executing aggressive import substitution and domestic development programs under its Defence Acquisition Procedure framework, with Hindustan Aeronautics Limited leading indigenous MALE drone development. Japan and South Korea are both expanding unmanned capabilities in response to North Korean and Chinese threat dynamics, with South Korea pursuing domestically developed tactical drone fleets and Japan acquiring MQ-9B SeaGuardian platforms from General Atomics.
Europe is experiencing an accelerated procurement cycle driven by the security shock of the Russia-Ukraine conflict. NATO European members collectively increased defense spending by an estimated $100 billion in real terms between 2022 and 2024, with unmanned systems receiving a disproportionate share of incremental investment. The United Kingdom, France, and Germany are the primary revenue contributors, with Turkey representing a distinct dynamic as both a major domestic producer through Baykar and a significant exporter of the Bayraktar TB2 platform to more than two dozen countries.
The Middle East and Africa region is a high-value market driven by active conflict environments and substantial sovereign wealth-backed defense modernization programs. The GCC states, particularly the United Arab Emirates and Saudi Arabia, are among the most active drone importers globally, while Israel functions simultaneously as a domestic innovator and leading global exporter. Turkey's drone exports have penetrated African markets significantly, particularly in sub-Saharan conflict zones.
South America remains a nascent but growing market, with Brazil and Argentina pursuing tactical drone capabilities within constrained defense budgets. The region's growth is primarily driven by border surveillance, counter-narcotics, and disaster response applications rather than high-intensity warfighting requirements.