Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Bone Densitometer Market Outlook 2025
Bone Densitometer Market
Bone Densitometer Market Outlook 2025
Bone Densitometer Market by Technology (Axial Bone Densitometry, Peripheral Bone Densitometry), by Application (Osteoporosis & Osteopenia, Rheumatoid Arthritis, Cystic Fibrosis, Chronic Kidney Disease, Body Composition Measurement), by End-use (Hospitals, Specialty Clinics, Diagnostic Centers, Research Institutions), by North America (USA, Canada, Mexico), by Europe (UK, Germany, France, Italy), by Asia Pacific (China, Japan, India, South Korea), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
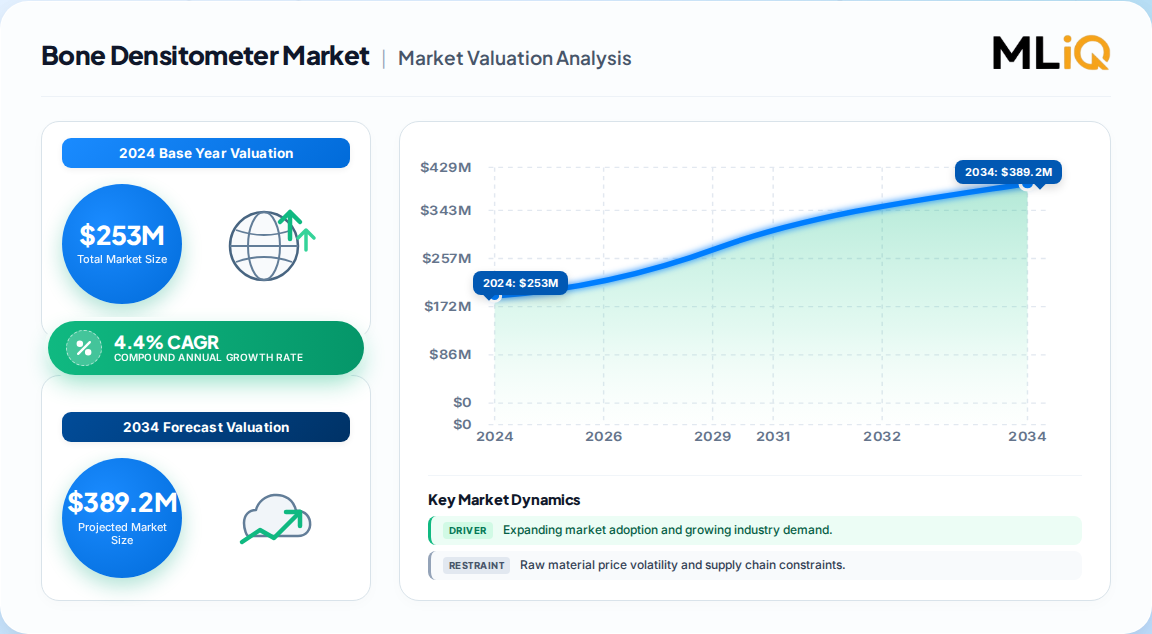
253 Million was the global bone densitometer market value in 2024, with a forecast of 329.3 Million by 2030 at a 4.4% CAGR.
Axial systems dominate with 50.9% of 2024 revenue, but peripheral and portable devices are the fastest-growing technology tier.
North America leads with 45.7% revenue share in 2024, with Asia Pacific the fastest-growing region.
Hospitals remain the anchor end-user at 55.1% share; specialty clinics are the fastest-expanding channel.
Osteoporosis and osteopenia applications generated 30.3% of revenue, underpinned by 8.9 million fractures annually worldwide.
Leaders include GE HealthCare, Hologic, DMS Imaging, and Swissray, competing on DXA accuracy, workflow automation, and AI integration.
Why this matters for decision-makers: Vendors must pivot toward portable, AI-enabled DXA and specialty-clinic distribution to avoid margin compression in saturated hospital accounts.
Bone Densitometer Market Size (In Million)
400.0M
300.0M
200.0M
100.0M
0
253.0 M
2024
264.0 M
2025
278.0 M
2026
290.0 M
2027
302.0 M
2028
316.0 M
2029
329.0 M
2030
Bone Densitometer Market Size (In Million)
Year
Market Size
2024
253.0 M
2025
264.0 M
2026
278.0 M
2027
290.0 M
2028
302.0 M
2029
316.0 M
2030
329.0 M
What is the Bone Densitometer Market?
The bone densitometer market covers medical imaging systems and software that measure bone mineral density (BMD) and assess fracture risk, primarily to diagnose and monitor osteoporosis and osteopenia. Devices use DXA, quantitative ultrasound, or QCT technologies across hospitals, specialty clinics, diagnostic centers, and research institutions.
Scope: what this report covers and excludes
This report covers global and regional revenue for axial and peripheral bone densitometers, segmented by technology, application, and end-use, with a forecast horizon to 2030. It includes hardware, embedded software, and service attach rates. This analysis does not cover standalone osteoporosis pharmaceuticals, orthopedic implants, general radiography systems, or companion DXA-independent biomarkers.
How big is the market for Bone Densitometer Market?
Published estimates diverge on base year and scope, so buyers should anchor on 2024 value and 2024–2030 CAGR rather than headline totals. The table below reconciles the leading figures.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
253.0 Million
2024
2030
4.4%
Global bone densitometers, device revenue
One published estimate
295.3 Million
2022
2032
4.9%
Global bone densitometers, device revenue
A competing analysis
366.7 Million
2025
2035
4.3%
Bone densitometer devices, broader inclusion
A competing analysis
Our analysis suggests the 253 Million (2024) figure is the most defensible base because it is closest to the reporting window, is consistent with 45.7% North American share, and its 4.4% CAGR sits inside the published 4.3–4.9% cluster. The higher 366.7 Million estimate likely bundles service contracts and refurbished units, widening the definitional perimeter. Divergence of this scale confirms buyers should validate scope before comparing vendor forecasts.
How is the market segmented?
The market follows three non-geographic axes — technology, application, and end-use — with axial DXA the revenue anchor and peripheral systems the growth engine.
Parent
Children
2024 revenue share
Technology
Axial bone densitometry, Peripheral bone densitometry
Hospitals, Specialty clinics, Diagnostic centers, Research institutions
55.1% hospitals
Axial DXA remains the clinical gold standard because it measures hip and spine sites with the precision algorithms like FRAX require. Peripheral systems trade precision for portability, unlocking primary care, pharmacy, and mobile screening — a structurally faster-growth but lower-average-selling-price tier.
Which region leads in Bone Densitometer Market?
North America led with 45.7% of 2024 revenue, driven by high healthcare expenditure, dense DXA installed bases, and reimbursement coverage in the US and Canada.
Bone Densitometer Market Regional Market Share
Loading chart...
Bone Densitometer Market Regional Market Share
Region
Market Share (%)
North America
0.42%
Europe
0.27%
Asia-Pacific
0.21%
Latin America
0.06%
Middle East & Africa
0.04%
North America (45.7%)
United States — largest country market, strong R&D and vendor presence
Canada — 2.3 million adults aged 40+ living with osteoporosis
Mexico — emerging contributor
Europe (27%)
United Kingdom — 3 million people affected annually per NHS
Germany — fastest-growing large European market
France, Italy — mature installed bases
Asia Pacific (21%)
China — 402 million people aged 60+ projected by 2040
Japan — advanced diagnostic adoption
India — rising disposable income and infrastructure
South Korea — high scanning penetration
Latin America (6%)
Brazil, Mexico, Argentina
Middle East & Africa (4%)
Saudi Arabia, UAE, South Africa
This divergence implies a maturing Western replacement cycle versus an Asia Pacific volume expansion story. Our analysis suggests Asia Pacific will contribute the majority of incremental units through 2030 even while North America retains revenue leadership — a split that should shape both pricing strategy and distribution investment.
What is driving growth — and what is holding it back?
Aging demographics and expanding osteoporosis screening programs are the dominant demand engines, while device cost and reimbursement gaps constrain adoption in price-sensitive markets.
Factor
Direction
Evidence strength
Mechanism
Aging population
Driver
High
60+ population reaches 2.1 billion by 2050 per WHO
Osteoporosis burden
Driver
High
8.9 million fractures annually worldwide per IOF
Portable and AI-enabled devices
Driver
Medium
Expands screening beyond hospital radiology
Government screening programs
Driver
Medium
20 new DEXA scanners deployed in England (2026)
High device cost
Restraint
Medium
Limits penetration in emerging markets
Reimbursement variability
Restraint
Medium
Caps routine screening volumes
Radiation and operator training concerns
Restraint
Low
Constrains peripheral QUS substitution
The balance of evidence favors structural growth: demographic demand is largely non-cyclical and screening programs are being formalized globally. The constraint is economic rather than clinical — cost per unit and reimbursement design, not diagnostic value. This implies vendors that lower total cost of ownership will convert latent demand fastest.
Who are the leading vendors?
GE HealthCare, Hologic, and DMS Imaging anchor a moderately concentrated market, with regional challengers competing on price and portability.
Vendor
Primary offering
Differentiation
GE HealthCare
Axial DXA platforms
Integrated imaging portfolio, enterprise scale
Hologic
DXA with TBS and VFA
Clinical algorithms, osteoporosis leadership
DMS Imaging
Axial and peripheral systems
Value positioning, European footprint
Swissray International
DXA systems
Digital radiography integration
Xingaoyi Medical Equipment
Peripheral devices
Cost leadership in Asia Pacific
Trivitron Healthcare
Peripheral densitometry
Emerging-market distribution
OsteoSys
Peripheral devices
Portable screening focus
Differentiation is shifting from hardware specifications toward software — trabecular bone score, vertebral fracture assessment, and AI-driven opportunistic screening from routine CT. Hologic's clinical-algorithm moat and GE's installed-base lock-in are the strongest defensible positions, while peripheral vendors compete on price and channel access.
What do buyers and operators need to know?
Procurement decisions hinge on clinical accuracy, reimbursement eligibility, and lifecycle cost rather than upfront price alone. Buyers should confirm DXA site coverage (hip and spine), FRAX compatibility, and regulatory clearance for screening indications before committing.
Switching costs are material: staff training, workflow integration, and service contracts create multi-year lock-in, making vendor due diligence a five-to-seven-year decision. Operators should model service and calibration costs explicitly, and prioritize systems with AI-assisted reading to offset radiologist scarcity. Regulatory compliance — including radiation safety and quality assurance accreditation — varies by jurisdiction and must be validated per site.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a structural-growth thesis, not a cyclical rebound. Demographic demand, formalized screening programs, and AI-enabled opportunistic detection support a durable 4.3–4.9% trajectory. The strongest counter-argument is reimbursement-driven volume stagnation in mature Western markets — a genuine risk, but one that shifts revenue mix rather than eliminating demand.
Our analysis suggests the sharpest opportunity sits at the intersection of portability and software. Peripheral systems unlock primary care and pharmacy channels at lower price points, while AI-based BMD extraction from routine CT creates a new screening funnel without new hardware purchases. Vendors anchored only in hospital DXA will face price pressure; those offering combined hardware-software-screening pathways will capture margin.
Actionable Strategy:
Prioritize portable, AI-enabled DXA solutions to capture specialty-clinic and pharmacy screening channels before incumbents extend downward.
Build reimbursement and service-contract bundles in North America and Europe to defend installed bases against replacement-cycle erosion.
Target Asia Pacific distribution partnerships in China and India, where volume growth outpaces revenue growth.
What would change our conclusion: Evidence of sustained reimbursement cuts or a validated alternative biomarker that displaces DXA as the diagnostic gold standard would materially weaken the growth thesis. Buyers should monitor these signals closely.
Bone Densitometer Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Bone Densitometer Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 4.4% from 2020-2034
Segmentation
By Technology
Axial Bone Densitometry
Peripheral Bone Densitometry
By Application
Osteoporosis & Osteopenia
Rheumatoid Arthritis
Cystic Fibrosis
Chronic Kidney Disease
Body Composition Measurement
By End-use
Hospitals
Specialty Clinics
Diagnostic Centers
Research Institutions
By Geography
North America
USA
Canada
Mexico
Europe
UK
Germany
France
Italy
Asia Pacific
China
Japan
India
South Korea
Latin America
Brazil
Mexico
Argentina
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Bone Densitometer Market Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Bone Densitometer Market Executive Summary
2.1. Market Snapshot
3. Bone Densitometer Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Bone Densitometer Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Bone Densitometer Market Analysis, Insights and Forecast, 2020-2034
5.1. Analysis, Insights and Forecast - by Technology
5.1.1. Axial Bone Densitometry
5.1.2. Peripheral Bone Densitometry
5.2. Analysis, Insights and Forecast - by Application
5.2.1. Osteoporosis & Osteopenia
5.2.2. Rheumatoid Arthritis
5.2.3. Cystic Fibrosis
5.2.4. Chronic Kidney Disease
5.2.5. Body Composition Measurement
5.3. Analysis, Insights and Forecast - by End-use
5.3.1. Hospitals
5.3.2. Specialty Clinics
5.3.3. Diagnostic Centers
5.3.4. Research Institutions
5.4. Analysis, Insights and Forecast - by Region
5.4.1. North America
5.4.2. Europe
5.4.3. Asia Pacific
5.4.4. Latin America
5.4.5. Middle East & Africa
6. Bone Densitometer Market North America Analysis, Insights and Forecast, 2020-2034
6.1. Analysis, Insights and Forecast - by Technology
6.1.1. Axial Bone Densitometry
6.1.2. Peripheral Bone Densitometry
6.2. Analysis, Insights and Forecast - by Application
6.2.1. Osteoporosis & Osteopenia
6.2.2. Rheumatoid Arthritis
6.2.3. Cystic Fibrosis
6.2.4. Chronic Kidney Disease
6.2.5. Body Composition Measurement
6.3. Analysis, Insights and Forecast - by End-use
6.3.1. Hospitals
6.3.2. Specialty Clinics
6.3.3. Diagnostic Centers
6.3.4. Research Institutions
7. Bone Densitometer Market Europe Analysis, Insights and Forecast, 2020-2034
7.1. Analysis, Insights and Forecast - by Technology
7.1.1. Axial Bone Densitometry
7.1.2. Peripheral Bone Densitometry
7.2. Analysis, Insights and Forecast - by Application
7.2.1. Osteoporosis & Osteopenia
7.2.2. Rheumatoid Arthritis
7.2.3. Cystic Fibrosis
7.2.4. Chronic Kidney Disease
7.2.5. Body Composition Measurement
7.3. Analysis, Insights and Forecast - by End-use
7.3.1. Hospitals
7.3.2. Specialty Clinics
7.3.3. Diagnostic Centers
7.3.4. Research Institutions
8. Bone Densitometer Market Asia Pacific Analysis, Insights and Forecast, 2020-2034
8.1. Analysis, Insights and Forecast - by Technology
8.1.1. Axial Bone Densitometry
8.1.2. Peripheral Bone Densitometry
8.2. Analysis, Insights and Forecast - by Application
8.2.1. Osteoporosis & Osteopenia
8.2.2. Rheumatoid Arthritis
8.2.3. Cystic Fibrosis
8.2.4. Chronic Kidney Disease
8.2.5. Body Composition Measurement
8.3. Analysis, Insights and Forecast - by End-use
8.3.1. Hospitals
8.3.2. Specialty Clinics
8.3.3. Diagnostic Centers
8.3.4. Research Institutions
9. Bone Densitometer Market Latin America Analysis, Insights and Forecast, 2020-2034
9.1. Analysis, Insights and Forecast - by Technology
9.1.1. Axial Bone Densitometry
9.1.2. Peripheral Bone Densitometry
9.2. Analysis, Insights and Forecast - by Application
9.2.1. Osteoporosis & Osteopenia
9.2.2. Rheumatoid Arthritis
9.2.3. Cystic Fibrosis
9.2.4. Chronic Kidney Disease
9.2.5. Body Composition Measurement
9.3. Analysis, Insights and Forecast - by End-use
9.3.1. Hospitals
9.3.2. Specialty Clinics
9.3.3. Diagnostic Centers
9.3.4. Research Institutions
10. Bone Densitometer Market Middle East & Africa Analysis, Insights and Forecast, 2020-2034
10.1. Analysis, Insights and Forecast - by Technology
10.1.1. Axial Bone Densitometry
10.1.2. Peripheral Bone Densitometry
10.2. Analysis, Insights and Forecast - by Application
10.2.1. Osteoporosis & Osteopenia
10.2.2. Rheumatoid Arthritis
10.2.3. Cystic Fibrosis
10.2.4. Chronic Kidney Disease
10.2.5. Body Composition Measurement
10.3. Analysis, Insights and Forecast - by End-use
10.3.1. Hospitals
10.3.2. Specialty Clinics
10.3.3. Diagnostic Centers
10.3.4. Research Institutions
11. Bone Densitometer Market Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Bone Densitometer Market Research Methodology
List of Figures
Figure 1: Bone Densitometer Market Revenue Breakdown (Million, %) by Region 2026 & 2034
Figure 2: North America Bone Densitometer Market Revenue (Million), by Technology 2026 & 2034
Figure 3: North America Bone Densitometer Market Revenue Share (%), by Technology 2026 & 2034
Figure 4: North America Bone Densitometer Market Revenue (Million), by Application 2026 & 2034
Figure 5: North America Bone Densitometer Market Revenue Share (%), by Application 2026 & 2034
Figure 6: North America Bone Densitometer Market Revenue (Million), by End-use 2026 & 2034
Figure 7: North America Bone Densitometer Market Revenue Share (%), by End-use 2026 & 2034
Figure 8: North America Bone Densitometer Market Revenue (Million), by Country 2026 & 2034
Figure 9: North America Bone Densitometer Market Revenue Share (%), by Country 2026 & 2034
Figure 10: Europe Bone Densitometer Market Revenue (Million), by Technology 2026 & 2034
Figure 11: Europe Bone Densitometer Market Revenue Share (%), by Technology 2026 & 2034
Figure 12: Europe Bone Densitometer Market Revenue (Million), by Application 2026 & 2034
Figure 13: Europe Bone Densitometer Market Revenue Share (%), by Application 2026 & 2034
Figure 14: Europe Bone Densitometer Market Revenue (Million), by End-use 2026 & 2034
Figure 15: Europe Bone Densitometer Market Revenue Share (%), by End-use 2026 & 2034
Figure 16: Europe Bone Densitometer Market Revenue (Million), by Country 2026 & 2034
Europe Bone Densitometer Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Bone Densitometer Market Revenue Million Forecast, by Technology 2020 & 2034
Table 2: Bone Densitometer Market Revenue Million Forecast, by Application 2020 & 2034
Table 3: Bone Densitometer Market Revenue Million Forecast, by End-use 2020 & 2034
Table 4: Bone Densitometer Market Revenue Million Forecast, by Region 2020 & 2034
Table 5: North America Bone Densitometer Market Revenue Million Forecast, by Technology 2020 & 2034
Table 6: North America Bone Densitometer Market Revenue Million Forecast, by Application 2020 & 2034
Table 7: North America Bone Densitometer Market Revenue Million Forecast, by End-use 2020 & 2034
Table 8: North America Bone Densitometer Market Revenue Million Forecast, by Country 2020 & 2034
Table 9: USA Bone Densitometer Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 10: Canada Bone Densitometer Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 11: Mexico Bone Densitometer Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 12: Europe Bone Densitometer Market Revenue Million Forecast, by Technology 2020 & 2034
Table 13: Europe Bone Densitometer Market Revenue Million Forecast, by Application 2020 & 2034
Table 14: Europe Bone Densitometer Market Revenue Million Forecast, by End-use 2020 & 2034
Table 15: Europe Bone Densitometer Market Revenue Million Forecast, by Country 2020 & 2034
Table 16: UK Bone Densitometer Market Revenue (Million) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. How big is the bone densitometer market?
The global bone densitometer market was valued at 253 Million in 2024 and is projected to reach 329.3 Million by 2030, growing at a 4.4% CAGR over the forecast period.
2. Which technology dominates the bone densitometer market?
Axial bone densitometry, primarily DXA-based central systems, held 50.9% of 2024 revenue. Peripheral systems are the fastest-growing segment due to lower cost, portability, and faster scanning.
3. Which region leads the bone densitometer market?
North America led with 45.7% of 2024 revenue, supported by healthcare expenditure and reimbursement coverage. Asia Pacific is the fastest-growing region on aging demographics and infrastructure investment.
4. Who are the leading bone densitometer vendors?
Key vendors include GE HealthCare, Hologic, DMS Imaging, Swissray International, Xingaoyi Medical Equipment, Trivitron Healthcare, Scanflex Healthcare, and OsteoSys, competing on DXA accuracy, software, and portability.
5. What is driving bone densitometer market growth?
Growth is driven by an aging global population, rising osteoporosis prevalence with 8.9 million fractures annually, government screening programs, and advances in portable and AI-enabled densitometry technology.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the value chain, including DXA component suppliers, densitometer OEMs, contract manufacturing partners, imaging software developers, and global diagnostic distributors. Decision-maker designations interviewed included VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring both clinical and commercial perspectives inform the sizing model.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
R&D & Technical Directors
35%
Procurement & Sourcing Leads
30%
Commercial Operations Leads
20%
Clinical & Regulatory Affairs
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Densitometer OEMs & Component Suppliers
40%
Imaging Software & AI Developers
25%
Global Diagnostic Distributors
20%
Hospital & Clinic Procurement Groups
15%
Secondary Benchmarking & Public Trade Validation
Estimates were cross-validated against UN Comtrade and WTO trade flows, US ITC and Eurostat medical device data, corporate 10-K and SEC filings, annual investor presentations, patent databases, and recognized technical standards from bodies such as the International Society for Clinical Densitometry and ISO. No competitor market-research publications were used in validation.
Demand Modeling & Market Sizing Triangulation
Simultaneous top-down (macroeconomic and segment allocation) and bottom-up (manufacturer capacity, unit pricing, and end-use consumption) modeling was applied. Discrepancies were resolved through weighted triangulation anchored on installed-base replacement cycles and screening-volume data.


 Bone Densitometer Market