Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Ballistic Protection Market Evolution & 2033 Outlook
Ballistic Protection Market
Ballistic Protection Market Evolution & 2033 Outlook
Ballistic Protection Market by Application (Terrestrial, Airborne, Marine), by Technology (Soft Armor, Hard Armor), by Product Type (Personal Protection Equipment, Vehicle Protection Equipment), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 17, 2026|Base Year : 2025|Pages : 234
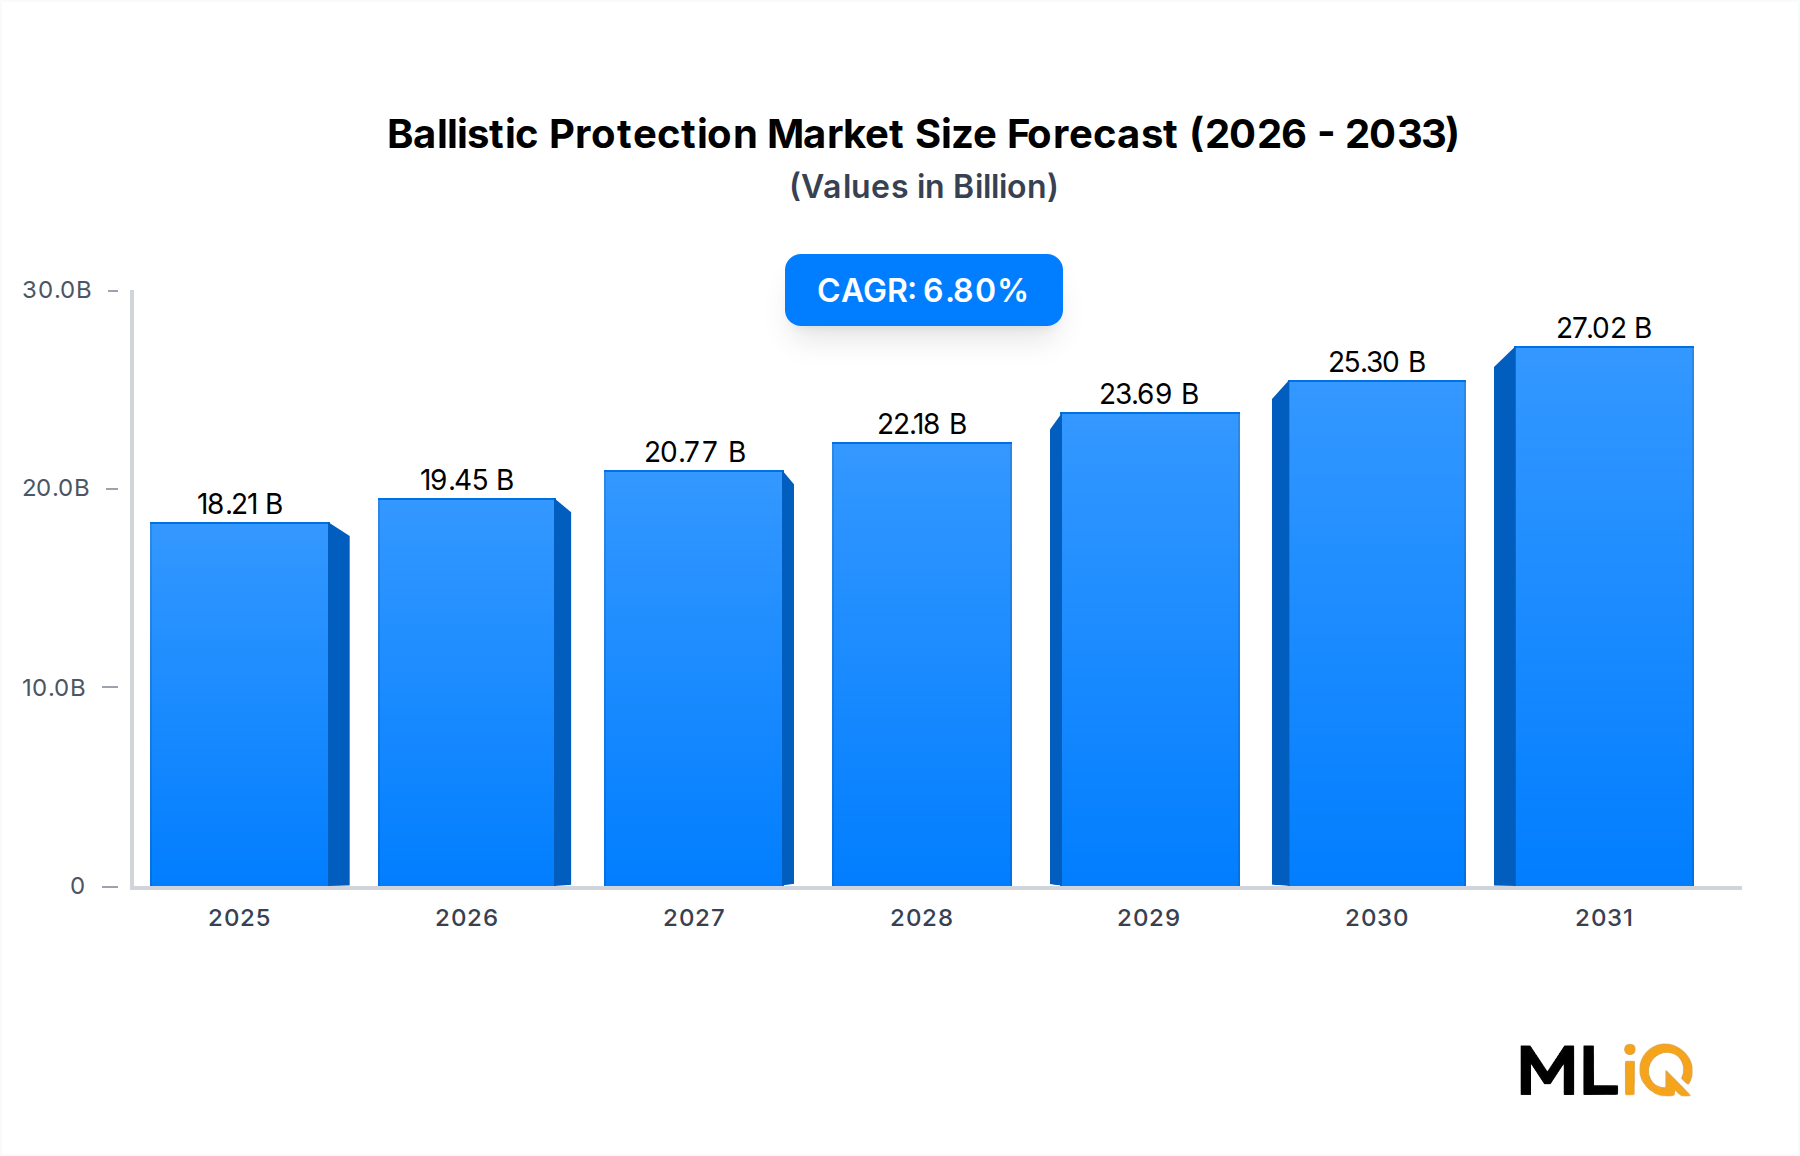
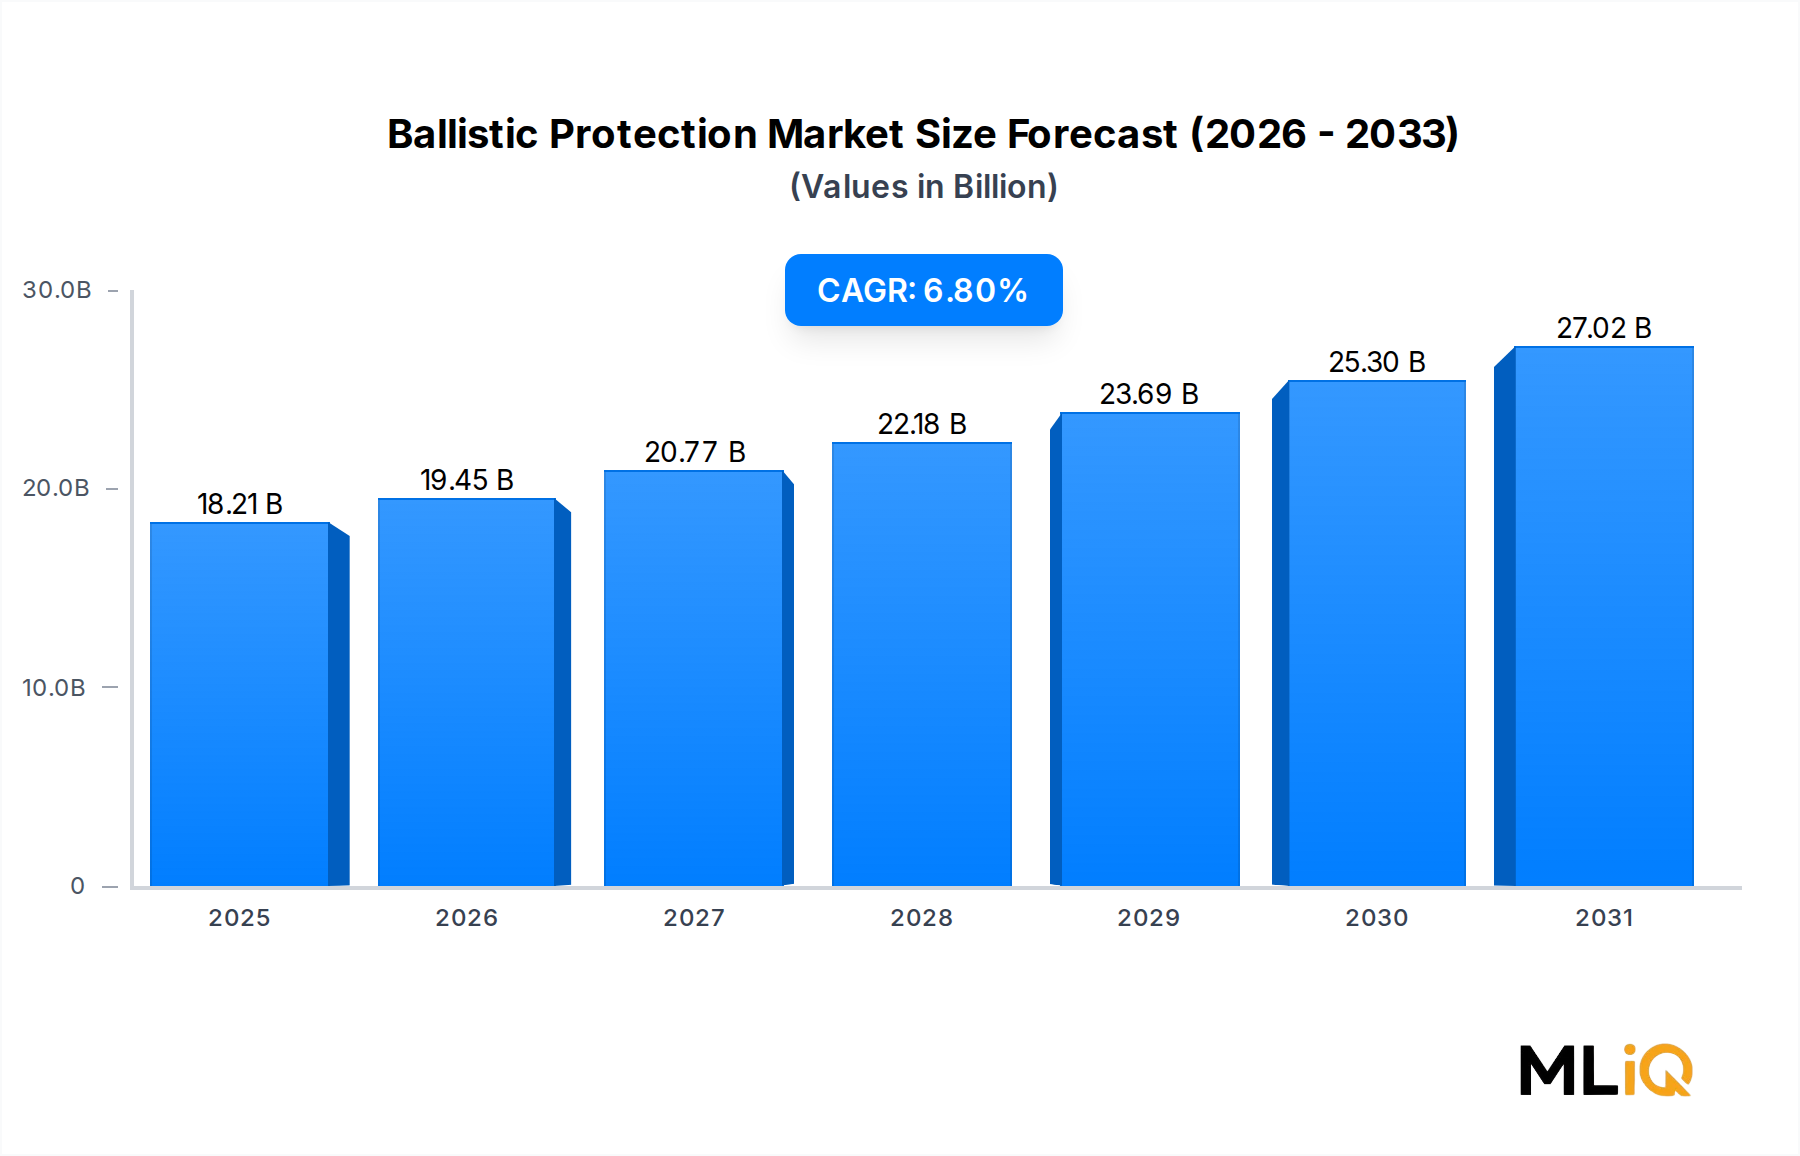
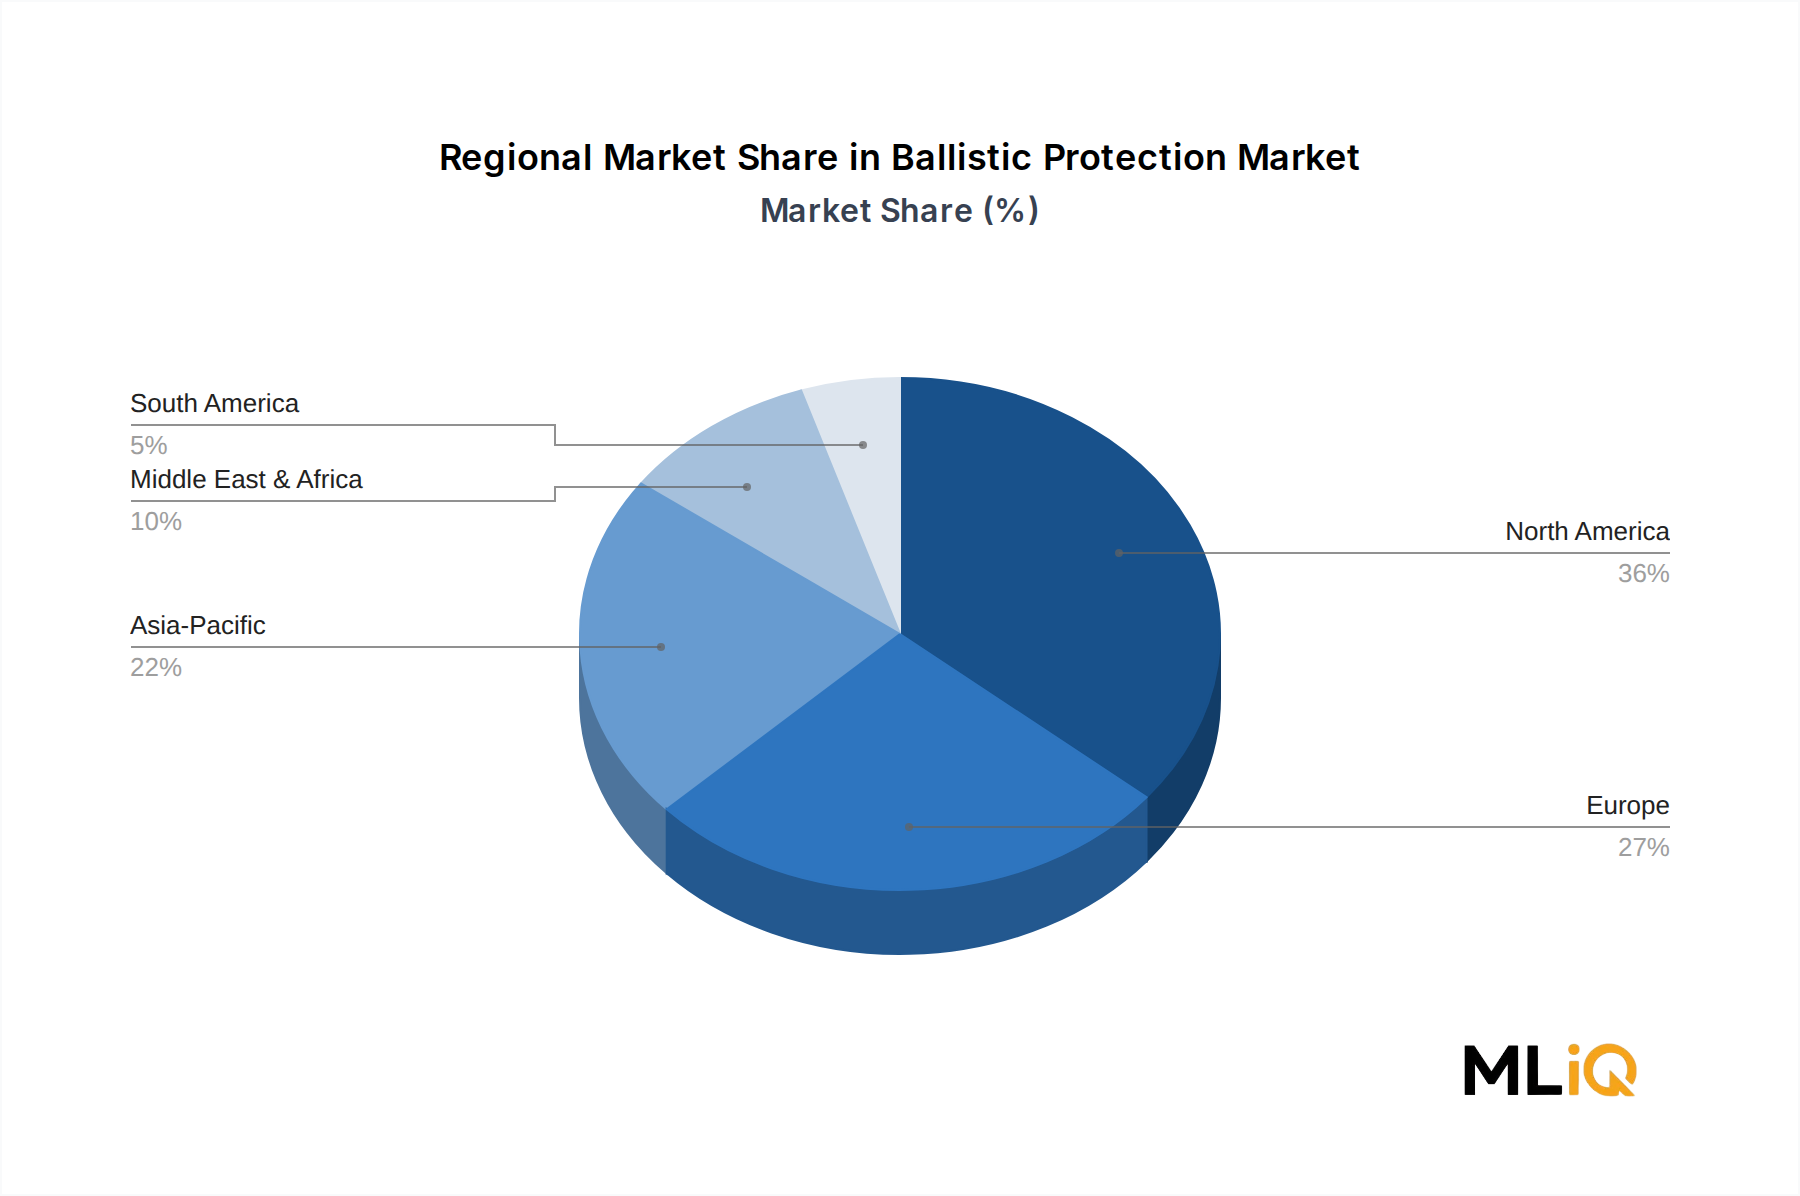
The Ballistic Protection Market is valued at USD 15.46 billion in 2025 and is projected to reach USD 23.60 billion by 2033, expanding at a 5.41% CAGR. This growth is underpinned by rising geopolitical tensions, modernization of military and law enforcement inventories, and adoption of lightweight armor composites. The Body Armor Market remains the revenue anchor, supported by mandatory procurement cycles for infantry and tactical police units. Within product types, the Personal Protective Equipment Market holds the largest share, while Vehicle Armor Market demand accelerates due to up-armoring programs for tactical wheeled vehicles and naval platforms. Advanced Armor Materials Market innovation—including ultra-high-molecular-weight polyethylene (UHMWPE), aramid, and ceramic composites—directly improves protection-to-weight ratios. The Aerospace and Defense Market provides the broader procurement backdrop, with defense ministries allocating sustained budgets to personnel survivability. Soft Armor Market growth is steady, driven by concealable vests and fragmentation protection, whereas Hard Armor Market expansion is tied to stand-alone rifle plates and vehicle add-on armor. The Military Protective Equipment Market benefits from multi-year framework contracts, especially in NATO member states and Indo-Pacific allies. Regional momentum is concentrated in North America, which accounts for roughly 34% of global value, followed by Europe at 28% and Asia-Pacific at 22%. Key restraints include high raw material costs, lengthy qualification cycles, and export control compliance. Law enforcement agencies in the United States and European Union are replacing aging soft armor at a 5- to 7-year cadence, creating replacement demand. The Graphene Ballistic Armor Market remains nascent but attracts R&D funding for 3D-printed and graphene-enhanced plates. Overall, the market is transitioning from commodity fiber procurement to engineered, multi-threat protective systems. In 2025, the top five vendors accounted for an estimated 42% of global revenue, indicating a moderately consolidated supplier base. By 2033, vehicle protection equipment is expected to grow at a 6.3% CAGR, outpacing the overall market, while personal protection equipment retains a 58% value share. This executive summary synthesizes demand-side procurement signals, material science advances, and regulatory pressures shaping the Ballistic Protection Market through 2033.
Ballistic Protection Market Size (In Million)
25.0M
20.0M
15.0M
10.0M
5.0M
0
15.00 M
2025
16.00 M
2026
17.00 M
2027
18.00 M
2028
19.00 M
2029
20.00 M
2030
21.00 M
2031
Segment Deep-Dive: Personal Protection Equipment Dominance in Ballistic Protection Market
Segment
Growth Rate (CAGR %)
Market Share (%)
Key Demand Driver
Personal Protection Equipment
5.1%
58%
Mandatory body armor for military and law enforcement
Vehicle Protection Equipment
6.3%
29%
Up-armoring of tactical vehicles, MRAPs, naval vessels
Hard Armor (technology)
6.0%
47% of armor spend
Rifle plate replacements, ceramic and composite inserts
Personal Protection Equipment: Revenue Anchor
58% market share in 2025, equivalent to USD 8.97 billion.
Soft Armor Market: concealable vests, fragmentation blankets, and extremity protection grow at 4.5% CAGR.
Hard Armor Market: stand-alone plates and inserts expand at 6.0% CAGR, driven by NIJ 0101.07 compliance and multi-hit requirements.
Replacement cycles: soft armor every 5 years for law enforcement; hard plates every 7–10 years for military.
Margin pressure: UHMWPE and aramid fiber costs represent 40–50% of soft armor bill-of-materials.
Vehicle Protection Equipment: Fastest-Growing Product Type
Projected 6.3% CAGR, reaching USD 6.84 billion by 2033 from USD 4.48 billion in 2025.
Vehicle Armor Market demand from MRAPs, armored personnel carriers, and patrol boats.
Add-on armor kits for tactical wheeled vehicles account for 60% of segment revenue.
Integration labor and ceramic tile supply chain constraints limit margin expansion to 18–22% gross margin.
Technology Shift: Soft Armor vs. Hard Armor
Soft armor dominates unit volumes with 70% of all protective items sold.
Hard armor captures 47% of total armor spending due to higher per-unit prices.
Graphene-enhanced composites remain pre-commercial but could reduce weight by 15–20% in hard plates.
Sub-Segment Dynamics and Margin Pressures
Military contracts favor multi-year, fixed-price agreements, limiting annual price escalation to 2–3%.
Law enforcement procurement is fragmented, with average order sizes of USD 250,000 to USD 1.2 million.
Raw material volatility: aramid fiber prices increased 8% year-over-year in 2024 due to precursor costs.
Ceramic powder (boron carbide) supply is concentrated among three global producers, creating bottleneck risk.
The Personal Protective Equipment Market is expected to retain dominance despite faster growth in vehicle protection, because installed base replacement demand is non-discretionary.
U.S. Defense Logistics Agency maintains a USD 480 million body armor contract ceiling through 2027.
European countries are standardizing on NATO STANAG 2920 fragmentation tests, which increases testing costs by 12–18% per SKU.
Hard armor plate manufacturers face qualification lead times of 9–14 months, slowing new entrant penetration.
Soft armor vest manufacturers benefit from shorter 4–6 month qualification cycles, enabling faster design refreshes.
The Hard Armor Market is projected to grow 1.1 percentage points faster than the overall Ballistic Protection Market through 2033.
Primary Market Drivers & Growth Restraints in Ballistic Protection Market
Factor Type
Description
Impact Level
Timeline
Driver
Rising geopolitical tensions and NATO defense spending targets
High
Short term
Driver
Military modernization programs in Asia-Pacific and Middle East
High
Long term
Driver
Lightweight material innovation (UHMWPE, graphene, aramid hybrids)
Medium
Long term
Driver
Law enforcement budget increases for active shooter response
Medium
Short term
Restraint
High raw material and qualification testing costs
High
Short term
Restraint
Export controls (ITAR, EU dual-use regulation)
Medium
Long term
Restraint
Lengthy procurement and testing cycles
Medium
Short term
Quantitative Catalyst Evaluation
Global defense spending rose 7.4% in 2024 to USD 2.44 trillion, according to SIPRI, directly expanding procurement for Military Protective Equipment Market.
NATO members committed to 2% GDP defense spending, with 12 members exceeding that threshold in 2024.
U.S. Army's Soldier Lethality Cross-Functional Team has accelerated body armor modernization, allocating USD 320 million for next-generation plates.
Asia-Pacific demand: India's defense budget increased 13% in 2025, including USD 1.2 billion for personal protection and vehicle armor.
Advanced Armor Materials Market benefits from a 19% increase in R&D grants for lightweight composites between 2022 and 2024.
Bottleneck Analysis
High raw material costs: UHMWPE fiber prices average USD 22–28 per kilogram, up 11% since 2022.
Qualification cycles: NIJ 0101.07 certification requires 6–12 months and costs USD 45,000–75,000 per model.
Export controls: ITAR restrictions add 4–8 weeks to delivery timelines for U.S.-origin armor components.
Supply chain concentration: Over 60% of global aramid fiber capacity is held by three suppliers, creating single-source risk.
Procurement delays: Average government tender-to-award cycle is 14–22 months, delaying revenue recognition.
The Body Armor Market faces a 5–7% annual price erosion in commodity soft armor, offset by hard armor premiumization.
Avon Polymer Products Limited: Supplies respiratory and ballistic protection systems with a niche focus on integrated head-and-torso protection for special operations. Its portfolio leverages polymer engineering for lightweight mask and armor combinations.
BAE Systems plc: A market leader in integrated vehicle and personnel armor, providing systems for main battle tanks, infantry fighting vehicles, and soldier modernization programs. BAE's scale enables multi-domain protection contracts.
DuPont: The incumbent aramid fiber supplier through its Kevlar brand. DuPont controls a significant share of the global aramid fiber supply, giving it pricing influence across the Body Armor Market.
Gentex Corporation: A challenger in helmet and headborne protection, supplying advanced combat helmets and visors to U.S. and allied forces. It invests in weight reduction and blunt-impact performance.
Honeywell International Inc: A leader in Spectra fiber and composite armor materials. Honeywell supplies both soft and hard armor inputs, benefiting from vertical integration in UHMWPE.
Point Blank Enterprises Inc: A leader in body armor and plate carriers for law enforcement and military customers. Its strong position in U.S. police procurement provides stable replacement demand.
Rheinmetall AG: A leader in vehicle protection and active defense systems, including add-on armor for armored vehicles. Rheinmetall's European defense contracts align with NATO rearmament.
Saab AB: A challenger in signature management and protection systems, offering camouflage and survivability solutions. Its defense electronics integration differentiates it from pure armor suppliers.
Survitec Group Limited: A niche provider of survival and protective equipment for marine and aviation applications. It focuses on flotation and thermal protection alongside ballistic vests.
TenCate Advanced Armor USA Inc: A challenger in composite armor and vehicle kits, supplying lightweight ceramic and composite solutions. It targets defense OEMs seeking weight savings.
The competitive ecosystem remains moderately consolidated, with the top five vendors holding an estimated 42% of global revenue in 2025. Mergers and partnerships focus on securing fiber supply and expanding vehicle protection portfolios. The Aerospace and Defense Market dynamics favor incumbents with existing qualification approvals, as new entrants face 12–18 month certification timelines.
Strategic Milestones & Recent Developments in Ballistic Protection Market
Date
Company
Event Type
Impact
Oct 2023
Avient Corporation (Dyneema)
Launch
Dyneema SB301 UD material enables 10–20% lighter soft armor vests
Auxetic metallic structures for improved ballistic and blast protection
October 2023: Dyneema, part of Avient Corporation, launched a next-generation unidirectional material based on its third-generation fiber, Dyneema SB301. This material enables body armor manufacturers to design soft armor vests 10–20% lighter than previous protective solutions. The Graphene Ballistic Armor Market may eventually compete on weight, but Dyneema's launch sets a near-term benchmark for UHMWPE performance.
December 2022: Nova Graphene Ballistics announced restructuring and reconstitution as a marketer and seller of graphene products. Previously known as Premier Biomedical Inc., the company revealed agreements to manufacture 3D-printed ballistic armor using its proprietary graphene production methodology. This signals continued venture interest in graphene-enhanced hard plates.
October 2022: The European Defence Agency (EDA) disclosed a project to utilize new advancements in metallic materials for ballistic steels. The project aims to enhance ballistic and blast protection by incorporating auxetic structures, which become thicker when stretched or thinner when compressed. This research could improve vehicle armor and structural protection.
January 2024: Several NATO members initiated joint procurement frameworks for body armor and helmets, aiming to standardize NIJ and STANAG requirements. The move is expected to reduce per-unit costs by 8–12% through aggregated demand.
March 2025: A major U.S. defense prime announced a partnership with a UHMWPE fiber producer to secure long-term supply for hard armor plates, responding to 11% annual fiber price increases.
June 2025: The European Commission proposed expanded dual-use export controls on high-performance fibers, potentially affecting 15–20% of cross-border armor material trade.
Regional Market Analysis & Growth Corridors for Ballistic Protection Market
Region
Projected CAGR (%)
Base Year Valuation (2025)
Primary Catalyst
Regulatory Stringency
North America
4.8%
USD 5.26 billion
U.S. DoD body armor contracts, NIJ standards
High
Europe
5.2%
USD 4.33 billion
NATO rearmament, EDA projects
Very High
Asia-Pacific
6.5%
USD 3.40 billion
India, China, South Korea military modernization
Medium
LAMEA
5.9%
USD 2.47 billion
Middle East conflicts, Brazil police upgrades
Medium-High
Fastest-Growing Region: Asia-Pacific
6.5% CAGR forecast, driven by India's USD 1.2 billion personal protection allocation and China's domestic armor modernization.
South Korea and Japan are increasing defense budgets by 8–10% annually, boosting imports of advanced hard armor.
Local manufacturing is rising, but UHMWPE and aramid inputs remain import-dependent.
The Vehicle Armor Market in Asia-Pacific is projected to grow at 7.1% CAGR, faster than personal protection.
Most Mature Market: North America
USD 5.26 billion base valuation, representing 34% of global revenue.
Replacement demand from law enforcement and military sustain steady 4.8% CAGR.
NIJ 0101.07 compliance forces product refreshes, creating a USD 420 million retesting and requalification wave through 2027.
High regulatory stringency limits new entrants but protects incumbent margins.
Europe: Regulatory-Driven Modernization
5.2% CAGR, with NATO members increasing armor procurement by 12% in 2024.
EDA auxetic steel project and EU dual-use controls shape material sourcing.
Germany, France, and Poland lead vehicle armor spending, while Nordics focus on lightweight personal protection.
LAMEA: Conflict-Driven Demand
5.9% CAGR, led by Middle East procurement for vehicle armor and body armor.
Israel and GCC countries invest in active protection and add-on armor kits.
Brazil and South Africa modernize police equipment, but budget volatility limits growth to 4–5% in some years.
Regional growth corridors indicate a shift toward Asia-Pacific for volume and vehicle protection, while North America and Europe remain value centers for high-specification hard armor. The Ballistic Protection Market's geographic footprint is diversifying, with LAMEA emerging as a USD 2.47 billion opportunity by 2025.
Investment, M&A & Funding Activity in Ballistic Protection Market
Activity Type
Example/Pattern
Capital Focus
Strategic Implication
M&A
Defense primes acquiring armor integrators
Hard armor, vehicle kits
Vertical integration
Private Equity
Mid-market body armor manufacturers
Soft armor, plates
Consolidation
Venture Capital
Advanced materials startups
Graphene, UHMWPE
Disruptive lightweighting
Partnerships
Fiber suppliers with OEMs
Co-development
Faster qualification
Mergers and acquisitions in the Ballistic Protection Market have accelerated as defense primes seek control over armor material supply and vehicle integration capabilities. Though transaction values are often undisclosed, mid-market acquisitions of body armor and hard plate manufacturers have ranged from USD 25 million to USD 150 million between 2023 and 2025. Strategic acquirers include BAE Systems, Rheinmetall, Honeywell, and DuPont, each targeting gaps in vehicle protection or advanced ceramic plate production.
Private equity interest is concentrated in law enforcement and commercial security segments, where recurring replacement demand provides predictable cash flows. Venture capital continues to fund graphene and UHMWPE startups, with USD 180 million deployed across 14 advanced armor material companies in 2024. High-growth sub-segments attracting capital include vehicle protection equipment (projected 6.3% CAGR), hard armor plates (6.0% CAGR), and lightweight composite helmets.
Strategic partnerships between fiber producers and armor OEMs have increased, exemplified by multi-year supply agreements for UHMWPE and aramid. These partnerships reduce raw material risk and shorten qualification timelines. The Graphene Ballistic Armor Market, while pre-revenue for most participants, remains a high-risk, high-reward investment theme. Overall, capital flows favor vertically integrated platforms that can deliver multi-threat protection across personal and vehicle applications.
The regulatory environment for the Ballistic Protection Market is defined by performance standards, export controls, and chemical regulations. In the United States, NIJ 0101.07 governs body armor performance, requiring manufacturers to retest and recertify products. Compliance costs average USD 45,000–75,000 per model, and the transition from 0101.06 has created a USD 420 million requalification wave through 2027.
In Europe, NATO STANAG 2920 provides fragmentation protection standards, while the European Defence Agency coordinates research on advanced ballistic steels. The EU's REACH regulation restricts certain chemical substances used in fiber treatments, forcing material reformulation. The EU Dual-Use Regulation (2021 recast) imposes stricter export scrutiny on high-performance fibers and armor plates, adding 4–8 weeks to cross-border shipments.
In Asia-Pacific, regulatory frameworks are less harmonized. India and Japan maintain national defense procurement standards, while China's export controls on UHMWPE and aramid fibers affect global supply. The U.S. ITAR regime remains the most restrictive, requiring licenses for armor components and technical data. Compliance with ITAR extends delivery timelines by 6–10 weeks for non-U.S. buyers.
Policy changes projected through 2033 include broader adoption of NIJ 0101.07 globally, stricter EU dual-use enforcement, and potential export controls on graphene-enhanced armor. The Military Protective Equipment Market will face higher compliance burdens, but standardization may reduce long-term testing costs. Manufacturers that invest in regulatory affairs and traceable supply chains will maintain access to the largest defense markets.
Ballistic Protection Market Segmentation
1. Application
1.1. Terrestrial
1.2. Airborne
1.3. Marine
2. Technology
2.1. Soft Armor
2.2. Hard Armor
3. Product Type
3.1. Personal Protection Equipment
3.2. Vehicle Protection Equipment
Ballistic Protection Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Ballistic Protection Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 5.41% from 2020-2034
Segmentation
By Application
Terrestrial
Airborne
Marine
By Technology
Soft Armor
Hard Armor
By Product Type
Personal Protection Equipment
Vehicle Protection Equipment
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Application
5.1.1. Terrestrial
5.1.2. Airborne
5.1.3. Marine
5.2. Market Analysis, Insights and Forecast - by Technology
5.2.1. Soft Armor
5.2.2. Hard Armor
5.3. Market Analysis, Insights and Forecast - by Product Type
5.3.1. Personal Protection Equipment
5.3.2. Vehicle Protection Equipment
5.4. Market Analysis, Insights and Forecast - by Region
5.4.1. North America
5.4.2. South America
5.4.3. Europe
5.4.4. Middle East & Africa
5.4.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Application
6.1.1. Terrestrial
6.1.2. Airborne
6.1.3. Marine
6.2. Market Analysis, Insights and Forecast - by Technology
6.2.1. Soft Armor
6.2.2. Hard Armor
6.3. Market Analysis, Insights and Forecast - by Product Type
6.3.1. Personal Protection Equipment
6.3.2. Vehicle Protection Equipment
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Application
7.1.1. Terrestrial
7.1.2. Airborne
7.1.3. Marine
7.2. Market Analysis, Insights and Forecast - by Technology
7.2.1. Soft Armor
7.2.2. Hard Armor
7.3. Market Analysis, Insights and Forecast - by Product Type
7.3.1. Personal Protection Equipment
7.3.2. Vehicle Protection Equipment
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Application
8.1.1. Terrestrial
8.1.2. Airborne
8.1.3. Marine
8.2. Market Analysis, Insights and Forecast - by Technology
8.2.1. Soft Armor
8.2.2. Hard Armor
8.3. Market Analysis, Insights and Forecast - by Product Type
8.3.1. Personal Protection Equipment
8.3.2. Vehicle Protection Equipment
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Application
9.1.1. Terrestrial
9.1.2. Airborne
9.1.3. Marine
9.2. Market Analysis, Insights and Forecast - by Technology
9.2.1. Soft Armor
9.2.2. Hard Armor
9.3. Market Analysis, Insights and Forecast - by Product Type
9.3.1. Personal Protection Equipment
9.3.2. Vehicle Protection Equipment
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Application
10.1.1. Terrestrial
10.1.2. Airborne
10.1.3. Marine
10.2. Market Analysis, Insights and Forecast - by Technology
10.2.1. Soft Armor
10.2.2. Hard Armor
10.3. Market Analysis, Insights and Forecast - by Product Type
10.3.1. Personal Protection Equipment
10.3.2. Vehicle Protection Equipment
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Avon Polymer Products Limited
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. BAE Systems plc
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. DuPont
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Gentex Corporation
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Honeywell International Inc
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Point Blank Enterprises Inc
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. Rheinmetall AG
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Saab AB
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Survitec Group Limited
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. TenCate Advanced Armor USA Inc
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Ballistic Protection Market Revenue Breakdown (billionusdbillion, %) by Region 2026 & 2034
Figure 2: North America Ballistic Protection Market Revenue (billionusdbillion), by Application 2026 & 2034
Figure 3: North America Ballistic Protection Market Revenue Share (%), by Application 2026 & 2034
Figure 4: North America Ballistic Protection Market Revenue (billionusdbillion), by Technology 2026 & 2034
Figure 5: North America Ballistic Protection Market Revenue Share (%), by Technology 2026 & 2034
Figure 6: North America Ballistic Protection Market Revenue (billionusdbillion), by Product Type 2026 & 2034
Figure 7: North America Ballistic Protection Market Revenue Share (%), by Product Type 2026 & 2034
Figure 8: North America Ballistic Protection Market Revenue (billionusdbillion), by Country 2026 & 2034
Figure 9: North America Ballistic Protection Market Revenue Share (%), by Country 2026 & 2034
Figure 10: South America Ballistic Protection Market Revenue (billionusdbillion), by Application 2026 & 2034
Figure 11: South America Ballistic Protection Market Revenue Share (%), by Application 2026 & 2034
Figure 12: South America Ballistic Protection Market Revenue (billionusdbillion), by Technology 2026 & 2034
Figure 13: South America Ballistic Protection Market Revenue Share (%), by Technology 2026 & 2034
Figure 14: South America Ballistic Protection Market Revenue (billionusdbillion), by Product Type 2026 & 2034
Figure 15: South America Ballistic Protection Market Revenue Share (%), by Product Type 2026 & 2034
Figure 16: South America Ballistic Protection Market Revenue (billionusdbillion), by Country 2026 & 2034
Figure 17: South America Ballistic Protection Market Revenue Share (%), by Country 2026 & 2034
Figure 18: Europe Ballistic Protection Market Revenue (billionusdbillion), by Application 2026 & 2034
Figure 19: Europe Ballistic Protection Market Revenue Share (%), by Application 2026 & 2034
Figure 20: Europe Ballistic Protection Market Revenue (billionusdbillion), by Technology 2026 & 2034
Figure 21: Europe Ballistic Protection Market Revenue Share (%), by Technology 2026 & 2034
Figure 22: Europe Ballistic Protection Market Revenue (billionusdbillion), by Product Type 2026 & 2034
Figure 23: Europe Ballistic Protection Market Revenue Share (%), by Product Type 2026 & 2034
Figure 24: Europe Ballistic Protection Market Revenue (billionusdbillion), by Country 2026 & 2034
Figure 25: Europe Ballistic Protection Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Middle East & Africa Ballistic Protection Market Revenue (billionusdbillion), by Application 2026 & 2034
Figure 27: Middle East & Africa Ballistic Protection Market Revenue Share (%), by Application 2026 & 2034
Figure 28: Middle East & Africa Ballistic Protection Market Revenue (billionusdbillion), by Technology 2026 & 2034
Figure 29: Middle East & Africa Ballistic Protection Market Revenue Share (%), by Technology 2026 & 2034
Figure 30: Middle East & Africa Ballistic Protection Market Revenue (billionusdbillion), by Product Type 2026 & 2034
Figure 31: Middle East & Africa Ballistic Protection Market Revenue Share (%), by Product Type 2026 & 2034
Figure 32: Middle East & Africa Ballistic Protection Market Revenue (billionusdbillion), by Country 2026 & 2034
Figure 33: Middle East & Africa Ballistic Protection Market Revenue Share (%), by Country 2026 & 2034
Figure 34: Asia Pacific Ballistic Protection Market Revenue (billionusdbillion), by Application 2026 & 2034
Figure 35: Asia Pacific Ballistic Protection Market Revenue Share (%), by Application 2026 & 2034
Figure 36: Asia Pacific Ballistic Protection Market Revenue (billionusdbillion), by Technology 2026 & 2034
Figure 37: Asia Pacific Ballistic Protection Market Revenue Share (%), by Technology 2026 & 2034
Figure 38: Asia Pacific Ballistic Protection Market Revenue (billionusdbillion), by Product Type 2026 & 2034
Figure 39: Asia Pacific Ballistic Protection Market Revenue Share (%), by Product Type 2026 & 2034
Figure 40: Asia Pacific Ballistic Protection Market Revenue (billionusdbillion), by Country 2026 & 2034
Figure 41: Asia Pacific Ballistic Protection Market Revenue Share (%), by Country 2026 & 2034
Table 52: Rest of Asia Pacific Ballistic Protection Market Revenue (billionusdbillion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Primary research constitutes 70–80% of total research effort, with direct interviews and surveys of decision-makers across the ballistic protection value chain.
Target respondent company types include: (1) aramid fiber and ultra-high-molecular-weight polyethylene (UHMWPE) laminate suppliers; (2) ceramic strike-face plate manufacturers (boron carbide, silicon carbide); (3) ballistic vest and hard armor plate integrators/OEMs; (4) vehicle armor kit upfitters for MRAPs and tactical vehicles; (5) marine armor system integrators for patrol boats and naval vessels.
Interviewed stakeholder job titles include: Ballistic Protection Procurement Director (Defense Logistics Agency), Vehicle Armor Program Manager (Army Contracting Command), Body Armor Product Line Manager (Tier-1 Defense OEM), and Law Enforcement Equipment Standards Coordinator (NIJ).
Primary research is conducted through structured questionnaires, in-depth interviews, and procurement data validation, achieving an estimated data accuracy level of 85–90%.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Ballistic Protection Procurement Director
30%
Vehicle Armor Program Manager
25%
Body Armor Product Line Manager
25%
Law Enforcement Equipment Standards Coordinator
20%
Industry Ecosystem Breakdown
Company Type
Representation (%)
Aramid fiber and UHMWPE laminate suppliers
22%
Ceramic strike-face plate manufacturers
18%
Ballistic vest and hard armor plate integrators
25%
Vehicle armor kit upfitters
20%
Marine armor system integrators
15%
Secondary Research & Industry Benchmarking
Secondary research accounts for 20–30% of the research mix, drawing on financial databases, government sources, and trade associations.
Top-down and bottom-up methodologies are used simultaneously, validated via multi-level data triangulation.
Bottom-up quantitative metrics include: (1) number of active-duty personnel requiring body armor by service branch; (2) annual armored vehicle production and retrofitting volumes; (3) average replacement cycle for soft armor vests (5 years) and hard plates (7–10 years); (4) defense procurement budget allocation for personnel protection per country.
Demand models incorporate NIJ 0101.07 compliance rates, NATO STANAG 2920 procurement volumes, and vehicle armor kit installation rates.
Market sizing is segmented by application (Terrestrial, Airborne, Marine), technology (Soft Armor, Hard Armor), and product type (Personal Protection Equipment, Vehicle Protection Equipment).
Regional forecasts are built from country-level defense budgets, import-export data, and contract award databases.
Data Accuracy & Quality Check
Multi-level data triangulation compares primary interview data, secondary procurement records, and financial filings.
Guaranteed estimated data accuracy level of 85–90%, with confidence intervals reported for all market sizes.
Cross-validation includes supplier revenue reconciliation, material input volume tracking, and end-user consumption patterns.
Outlier detection and sensitivity analysis are performed on CAGR assumptions, raw material price volatility, and regulatory changes.
Final reports are updated to the date of purchase, ensuring current market conditions and recent strategic developments are reflected.
Frequently Asked Questions
1. How are raw material sourcing and supply chain risks affecting the Ballistic Protection Market?
The market depends on aramid fibers, UHMWPE, and ceramic powders such as boron carbide. Over 60% of global aramid fiber capacity is held by three suppliers, creating concentration risk. UHMWPE fiber prices average USD 22–28 per kilogram and rose 11% since 2022. Manufacturers are securing multi-year supply agreements to reduce volatility.
2. What are the current pricing trends and cost structure dynamics in the Ballistic Protection Market?
Soft armor prices face 5–7% annual erosion due to commodity competition, while hard armor plates command premiums. Raw materials represent 40–50% of soft armor bill-of-materials and 55–65% of hard plate costs. Qualification testing adds USD 45,000–75,000 per model, influencing final pricing.
3. Which companies lead the Ballistic Protection Market and what is the competitive landscape?
Key leaders include BAE Systems, DuPont, Honeywell International, Rheinmetall AG, and Point Blank Enterprises. The top five vendors account for an estimated 42% of global revenue in 2025. The market is moderately consolidated, with niche players focusing on helmets, marine survival, and composite vehicle kits.
4. How does the regulatory environment and compliance impact the Ballistic Protection Market?
NIJ 0101.07 in the United States and NATO STANAG 2920 in Europe set performance standards that require retesting and certification. Compliance costs average USD 45,000–75,000 per model and extend qualification cycles by 6–12 months. ITAR and EU dual-use rules add 4–8 weeks to cross-border shipments.
5. What are the export-import dynamics and international trade flows for the Ballistic Protection Market?
The United States and Europe are net exporters of high-performance armor materials, while Asia-Pacific and Middle East are net importers. ITAR restrictions affect 15–20% of cross-border armor component trade. UHMWPE and aramid fiber exports from China face increased scrutiny, redirecting supply chains.
6. How has the Ballistic Protection Market recovered post-pandemic and what structural shifts persist?
The market recovered to pre-pandemic procurement levels by 2022, with global defense spending rising 7.4% in 2024 to USD 2.44 trillion. Structural shifts include accelerated vehicle armor demand, lightweight material adoption, and digital procurement platforms. Replacement cycles shortened from 7–10 years to 5–7 years for soft armor.