Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Atomic Clock Market Trends and 2033 Forecast Outlook
Atomic Clock Market
Atomic Clock Market Trends and 2033 Forecast Outlook
Atomic Clock Market by End User (Defense), by Patrol Vessels? (Space), by Application (Surveillance, Navigation, Electronic Warfare?, Telemetry, Communication), by Type (Rubidium (Rb) Atomic Clock, Cesium (Cs) Atomic Clock, Hydrogen (H) Maser Atomic Clock), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Oct 5, 2026|Base Year : 2025|Pages : 234
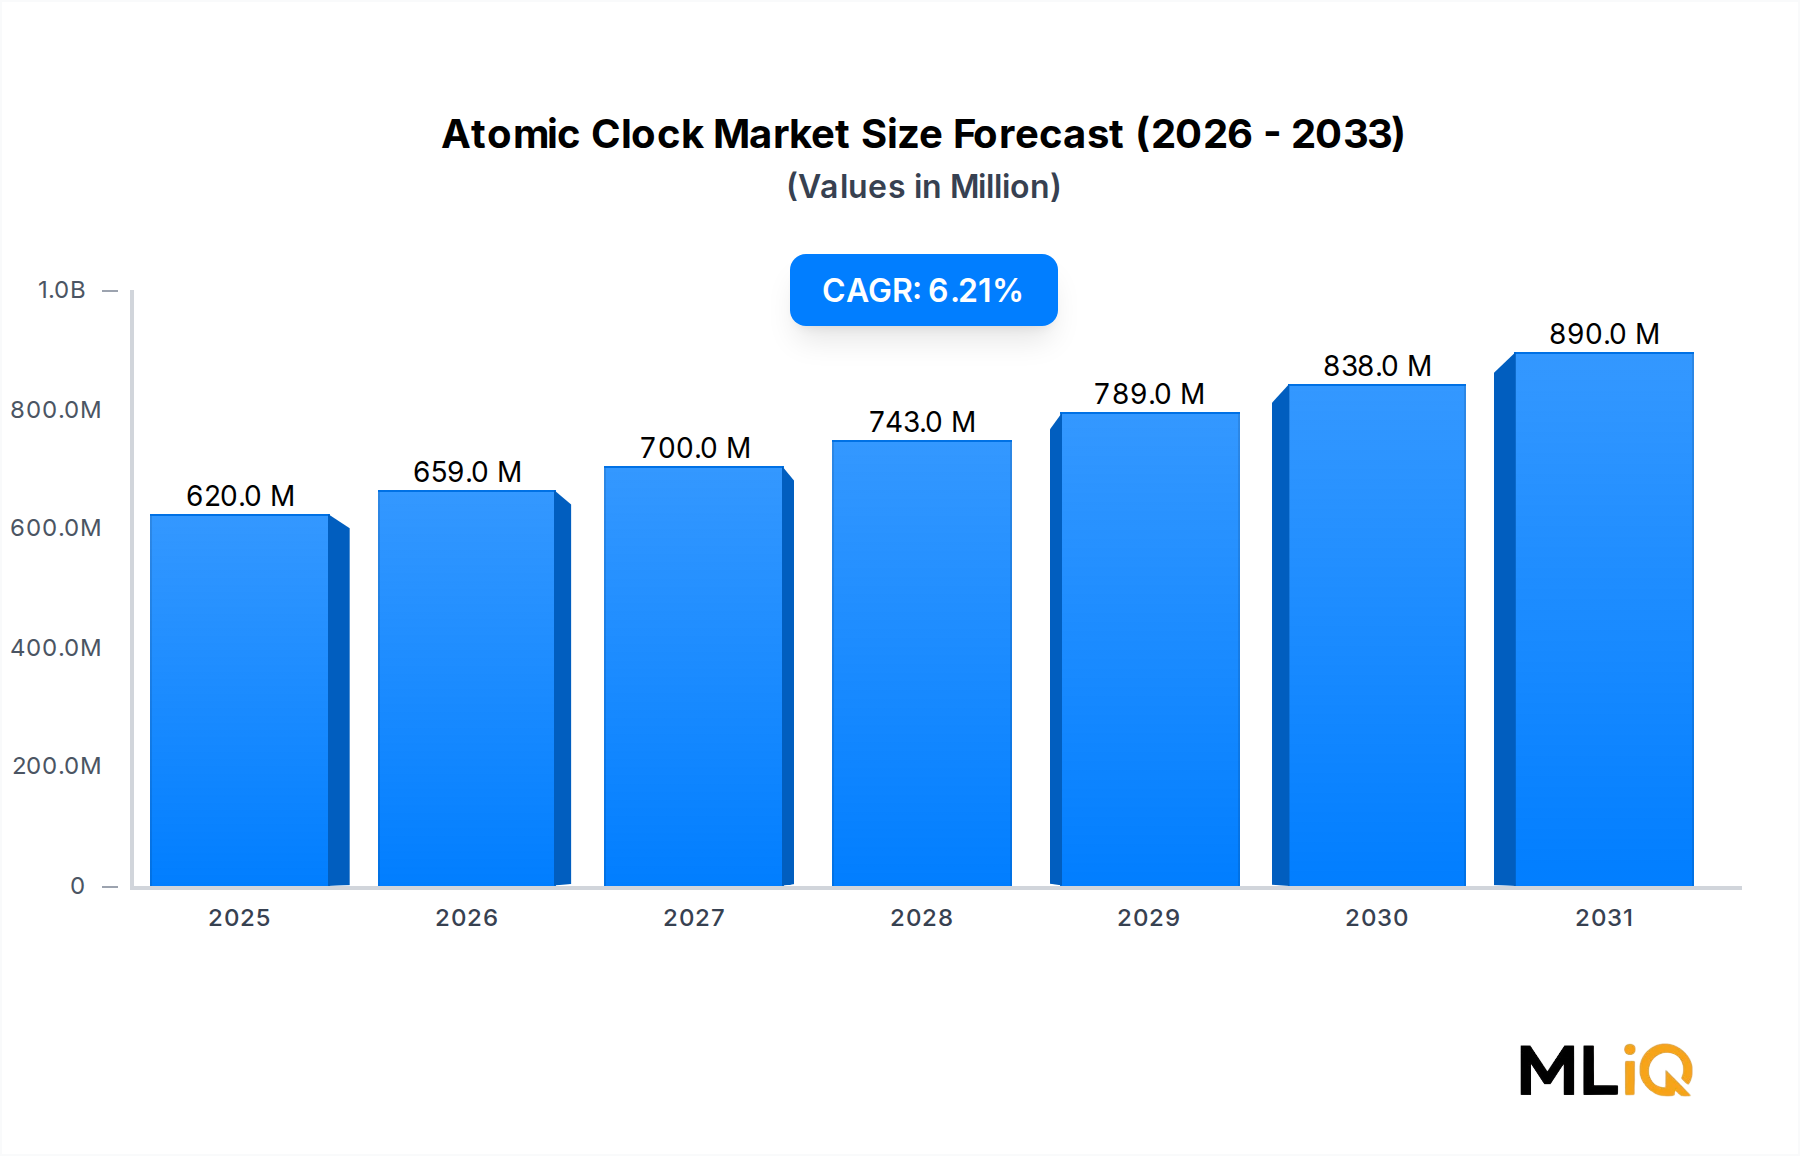
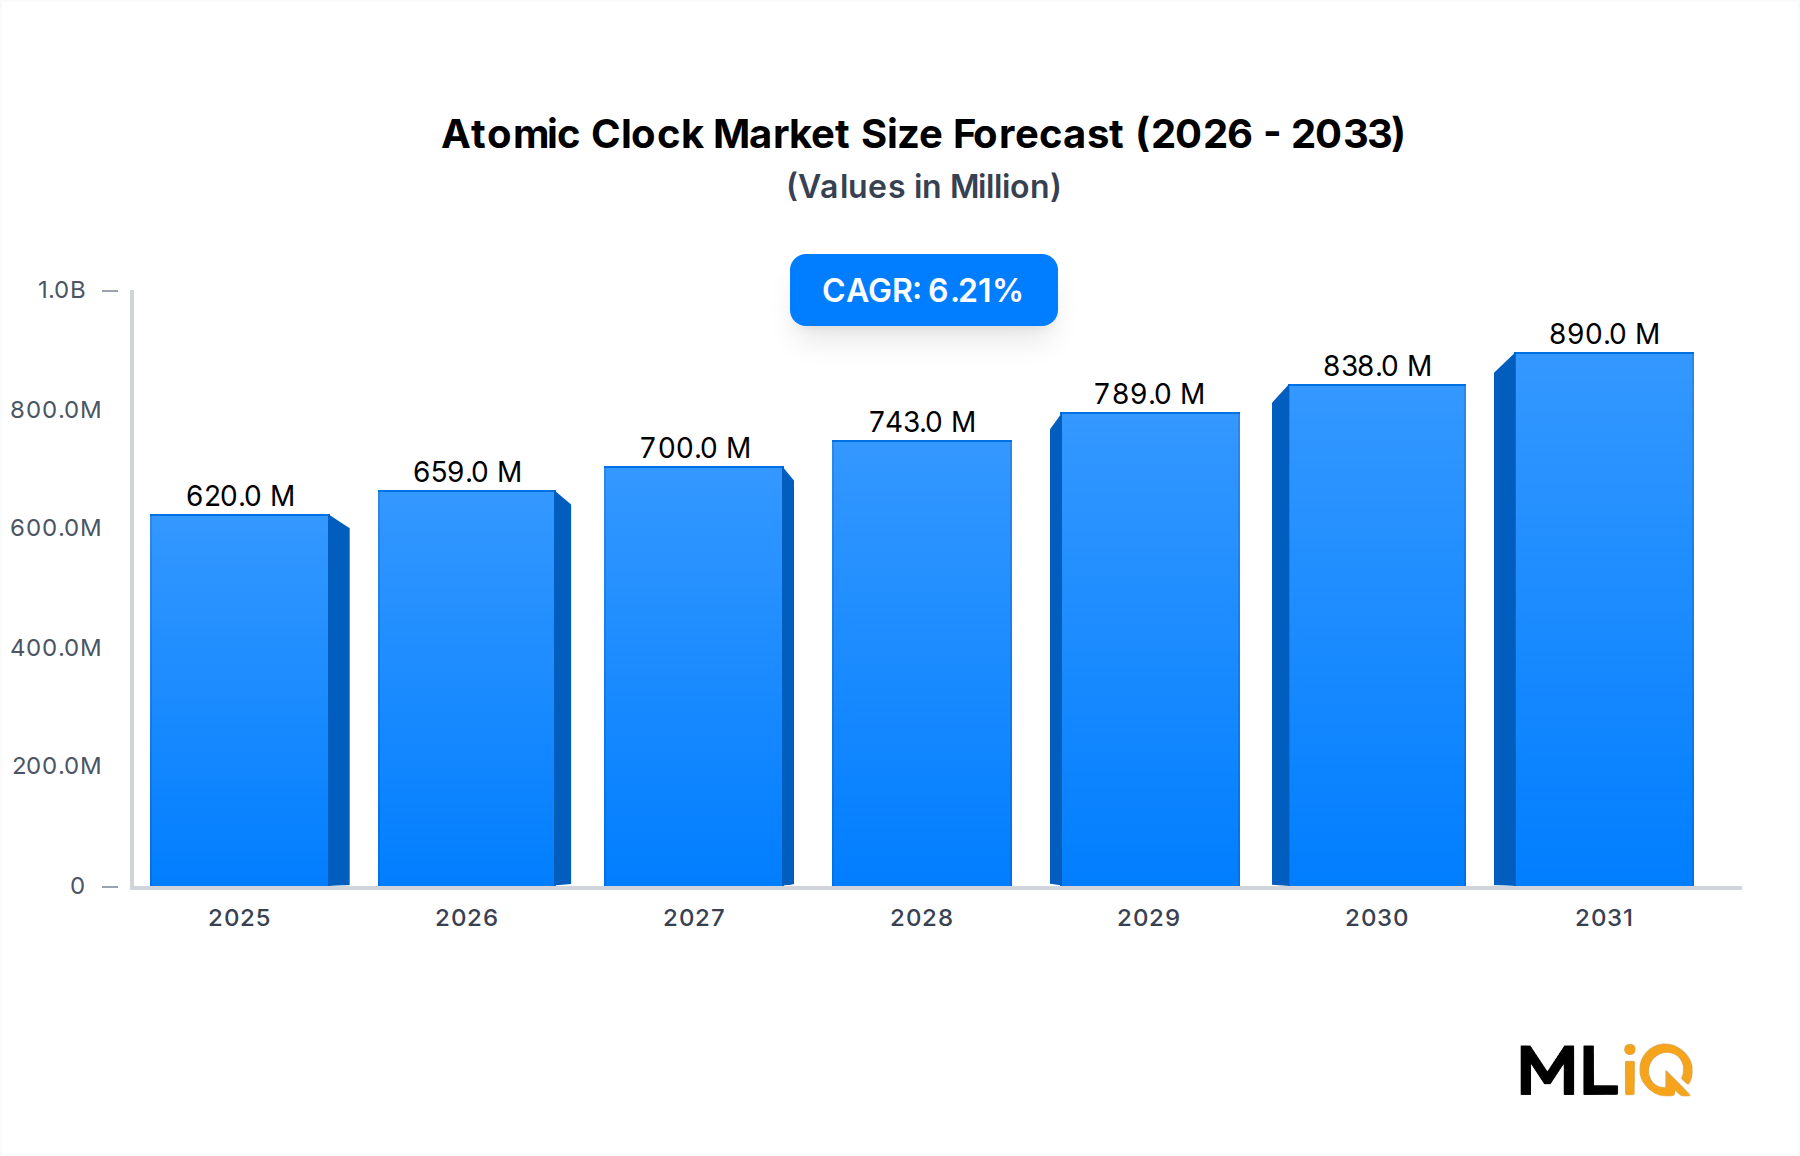
The Atomic Clock Market was valued at USD 11.19 billion in 2025 and is forecast to reach USD 26.58 billion by 2033, expanding at an 11.42% CAGR across the 2026-2034 window. Growth is anchored in defense PNT modernization, satellite constellation replenishment and 5G/6G synchronization rules that require sub-nanosecond holdover accuracy when GNSS signals are degraded or denied.
Atomic Clock Market Size (In Billion)
25.0B
20.0B
15.0B
10.0B
5.0B
0
11.19 B
2025
12.47 B
2026
13.89 B
2027
15.48 B
2028
17.25 B
2029
19.21 B
2030
21.41 B
2031
Defense remains the largest demand center, accounting for an estimated 46% of 2025 revenue. The Defense Timing and Synchronization Market is expanding because electronic warfare, secure communications and anti-jam navigation systems need autonomous timekeeping references that cannot be spoofed. Procurement activity in the United States, France, Israel and South Korea generated more than USD 5.1 billion of 2025 spend when naval, airborne and ground programs are combined.
On the product side, the Rubidium Atomic Clock Market represents the highest unit-volume tier, favored for compact footprint and low power draw. The Cesium Atomic Clock Market holds the smallest volume but the highest average selling price, sustaining primary frequency standards at national metrology institutes. The Hydrogen Maser Atomic Clock Market serves deep-space navigation and very-long-baseline interferometry, where Allan deviation performance at 10,000-second intervals is the decisive specification.
Three structural forces shape 2026-2033:
Chip-scale atomic clock (CSAC) commercialization is removing size, weight and power barriers, supporting batch production above 50,000 units annually by 2028.
Optical lattice and Rydberg prototypes are moving toward ruggedized field variants, with first defense qualification targeted before 2030.
Space Atomic Clock Market demand is rising with LEO constellation replenishment, where each satellite payload carries 1-2 onboard frequency references.
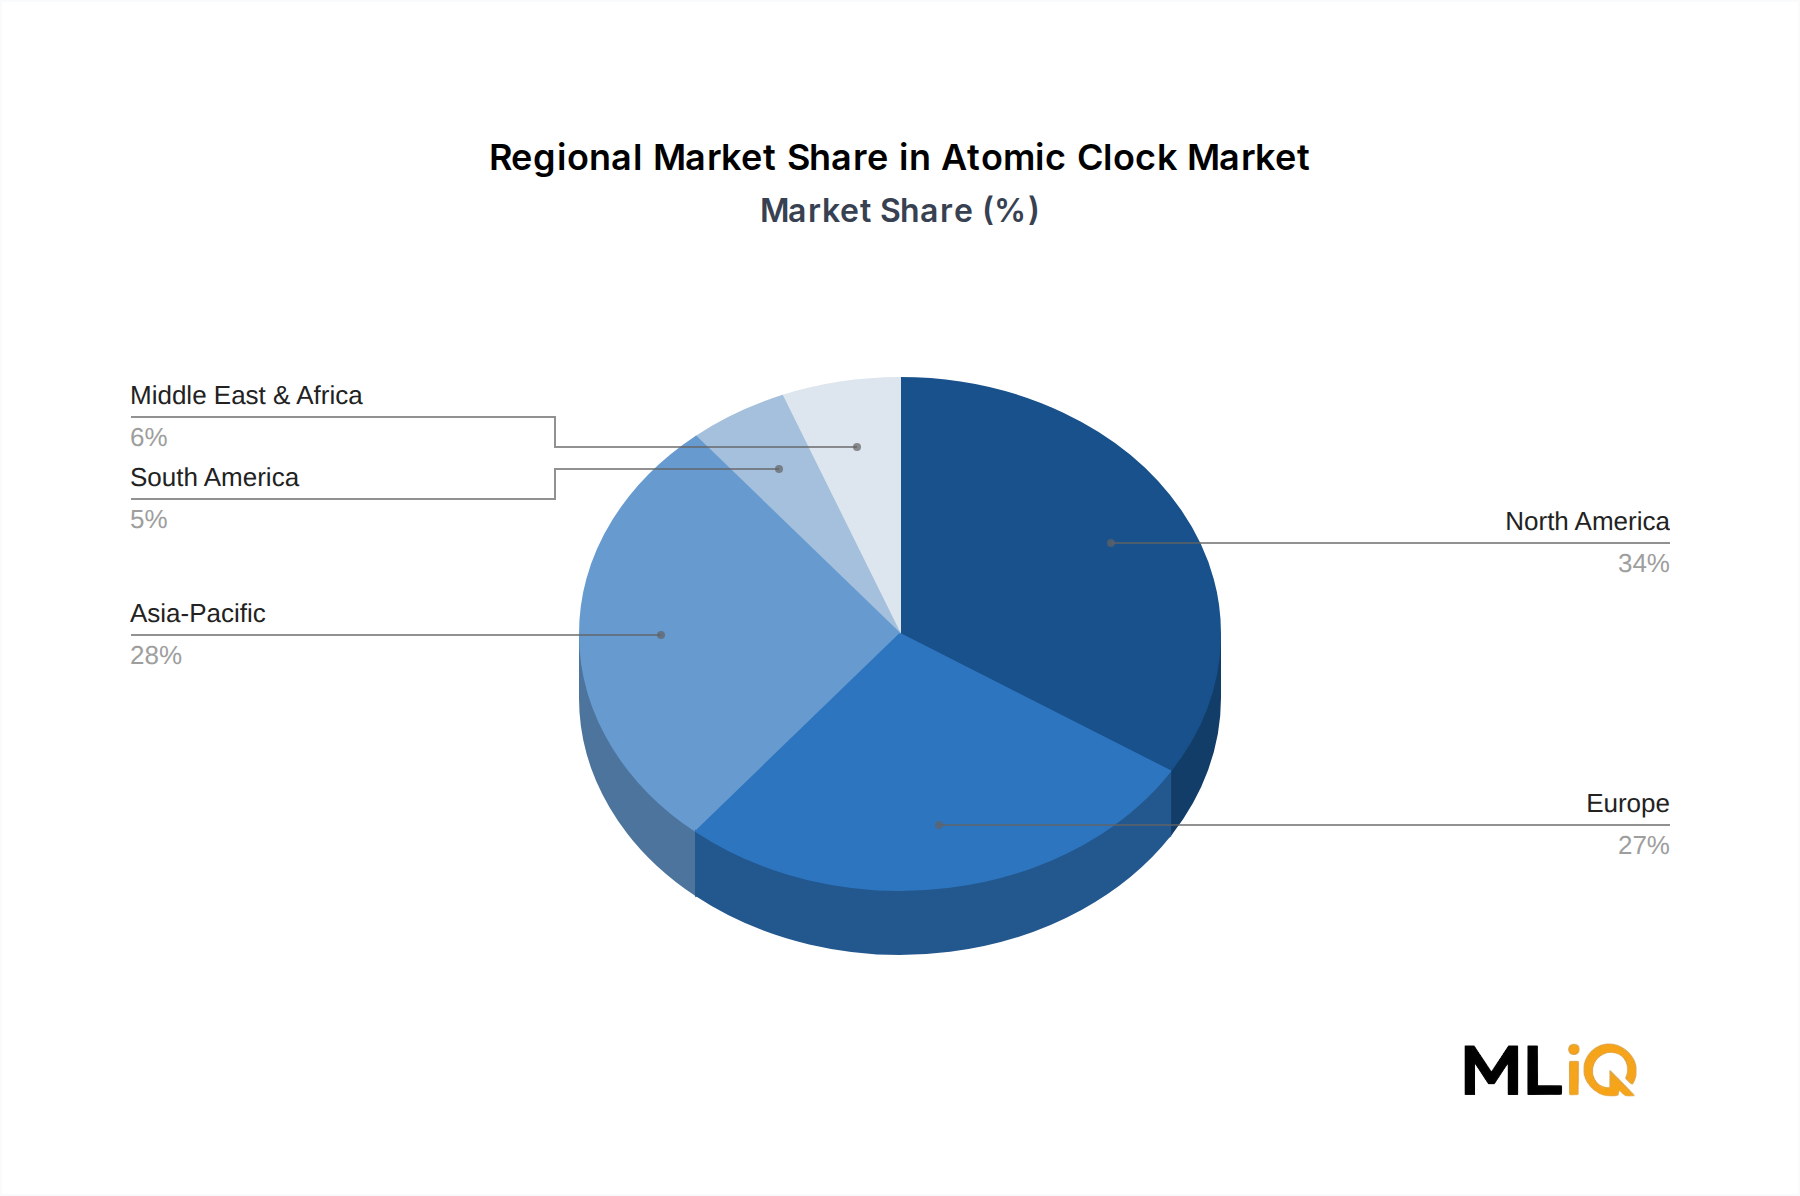
Regional concentration remains high. North America holds 34% of global value, Europe 24%, and Asia-Pacific 28%, the last expanding fastest at a projected 12.9% CAGR. Supply is constrained by a narrow base of rubidium and cesium component suppliers, which sustains gross margins above 40% for vertically integrated vendors and creates single-source risk for subsystem integrators.
Segment Deep-Dive: Defense Segment Dominance in Atomic Clock Market
Segment Analysis Matrix
Segment
Projected CAGR (2026-2033)
Market Share (2025)
Key Demand Driver
Defense (End User)
10.8%
46%
Jam-resistant PNT for airborne, naval and electronic warfare platforms
Space (End User)
14.6%
21%
LEO constellation replenishment and deep-space navigation payloads
Rubidium Atomic Clock (Type)
12.1%
38%
Low-SWaP timing in telecom, test equipment and tactical radios
Cesium Atomic Clock (Type)
7.4%
17%
Primary frequency standards and metrology-grade calibration
Defense: The Revenue Anchor
Defense end users contributed an estimated USD 5.15 billion in 2025 and remain the segment with the most predictable order book, since contracts are multi-year and tied to platform production schedules rather than replacement cycles.
Naval programs consume ruggedized rubidium and cesium units for secure communications, radar timing and anti-jam navigation.
Airborne platforms require MIL-STD-810-qualified references that survive vibration, thermal cycling and altitude extremes.
Ground electronic warfare suites need holdover performance that survives 24 to 72 hours of GNSS denial.
Defense margins stay in the 42-48% band because qualification costs are amortized across long programs, but the 18-to-36 month qualification cycle restricts new entrants and locks in incumbent suppliers.
Space and Commercial Timing: The Growth Multiplier
The space end-user tier is the fastest-growing block at 14.6% CAGR. Each replenishment satellite carries one or more onboard references, and ground segment upgrades add further units per constellation.
The commercial Precision Time Synchronization Market is a second growth vector, driven by telecom operators that must meet ITU-T G.8272 primary reference time clock requirements. Base station deployments in China, India and the United States add steady rubidium unit demand, though this tier carries lower average selling prices and sharper price competition than defense.
Margin Pressures
Rubidium isotope purification is capital-intensive and concentrated among a small supplier group, keeping input costs volatile.
Defense qualification and burn-in testing absorb 12-18% of unit cost before delivery.
Telecom and test-equipment customers negotiate on price, compressing margins to the 28-34% range.
Hydrogen maser systems, priced above USD 250,000 per unit, carry the highest absolute margin but the longest sales cycles.
Net position: defense and space together generate roughly two-thirds of segment profit, and vendor investment is concentrating there.
Primary Market Drivers & Growth Restraints in Atomic Clock Market
LEO constellation build-out with onboard frequency references
High
Medium term
Driver
5G/6G synchronization mandates (ITU-T G.8272)
Medium
Short term
Driver
CSAC miniaturization lowering SWaP barriers
Medium
Medium term
Restraint
Concentrated rubidium and cesium feedstock supply
High
Long term
Restraint
18-36 month defense qualification cycles
Medium
Long term
Restraint
ITAR and dual-use export licensing friction
High
Short term
Restraint
Unit cost above USD 250,000 for hydrogen maser systems
Medium
Long term
Demand catalysts are structural rather than cyclical. Defense ministries in the United States, France, Israel, South Korea and India have funded resilient PNT programs that treat atomic clocks as mission-critical infrastructure, which protects budgets even during fiscal tightening. The GNSS Timing Receiver Market benefits indirectly, since receivers without autonomous holdover references fail jamming and spoofing scenarios and are being redesigned around embedded rubidium or CSAC modules.
Constellation economics reinforce the trend. LEO operators replacing satellites on five-to-seven-year cycles create repeatable payload demand rather than one-off procurement, and ground segment upgrades multiply unit counts per constellation.
Key restraints are supply-side and regulatory:
Global rubidium and cesium production is limited to a handful of refineries, so a single outage can delay multiple product lines.
Export licensing under the Wassenaar Arrangement and US ITAR adds 60 to 180 days to cross-border delivery.
Long qualification timelines mean new entrants need 3-5 years of funded development before generating defense revenue.
Price-sensitive telecom buyers cap how much cost inflation vendors can pass through.
Net effect: volume growth is secure, but supply concentration and licensing friction will keep lead times extended and pricing firm through 2030.
Safran: supplies rubidium and maser-based timing subsystems into European naval and airborne programs, with integration depth that spans physics package to platform-level PNT.
Microchip Technology Incorporated: anchors the CSAC tier and drives commercial volume through a broad distribution footprint reaching industrial and telecom design teams.
Oscilloquartz (Adtran Networks SE): competes on network synchronization software and hardware, with a portfolio consolidated into Adtran following the ADVA combination.
Leonardo S.p.A.: leverages platform-level electronics integration to bundle timing with electronic warfare and communications subsystems for European ministries.
AccuBeat Ltd: specializes in compact rubidium and quartz references for airborne and defense applications where SWaP is the binding constraint.
Excelitas Technologies Corp: supplies photonics and laser components that feed physics-package assembly at OEM level.
VREMYA-CH JSC: delivers hydrogen maser and cesium references to ground station and metrology customers.
Thermo Fisher Scientific Inc: serves research and calibration laboratories with instrumentation content adjacent to primary reference standards.
Strategic Milestones & Recent Developments in Atomic Clock Market
Latest Strategic Moves
Date
Company
Event Type
Impact
Q3 2023
Microchip Technology Incorporated
Product Launch
Broadened chip-scale atomic clock availability for commercial and industrial timing designs
Q4 2022
Adtran Networks SE (Oscilloquartz)
Corporate Integration
Consolidated the Oscilloquartz synchronization portfolio under a single operating structure
Q1 2024
Safran
Program Win
Extended naval and airborne timing subsystem deliveries under European defense contracts
Q2 2024
Leonardo S.p.A.
Partnership
Co-development of timing and EW subsystems with European platform integrators
Q1 2025
Excelitas Technologies Corp
Portfolio Expansion
Scaled photonics and laser component supply for atomic clock physics packages
Q2 2025
VREMYA-CH JSC
Product Launch
Delivered hydrogen maser reference units to ground station customers
Q3 2025
AccuBeat Ltd
Product Launch
Qualified compact rubidium timing units for airborne operation
Chronological detail on the developments that shift competitive position:
The Oscilloquartz integration into Adtran Networks SE created a single vendor covering both hardware references and network synchronization software, raising the competitive bar for standalone clock suppliers.
Microchip's expansion of chip-scale availability moved CSAC technology from specialty sourcing to catalog procurement, shortening design cycles for industrial and defense OEMs.
Safran and Leonardo program activity confirms that European defense procurement is shifting timing subsystems from bill-of-materials line items to contracted mission-critical elements.
Upstream component expansion by Excelitas Technologies Corp matters because laser and photonics supply has been a lead-time bottleneck for physics package assembly.
VREMYA-CH JSC's ground station deliveries highlight sustained demand from metrology and space infrastructure outside Western supply chains.
Table entries reflect publicly disclosed and trade-reported milestones as of the report date.
Regional Market Analysis & Growth Corridors for Atomic Clock Market
Regional Growth Comparison
Region
Projected CAGR (%)
Base Year Valuation (USD bn)
Primary Catalyst
Regulatory Stringency
North America
10.6
3.80
Defense PNT modernization and GPS ground segment upgrades
High (ITAR, EAR, NDAA sourcing rules)
Europe
10.1
2.69
Galileo second generation and naval electronic warfare programs
High (EU dual-use Regulation 2021/821)
Asia-Pacific
12.9
3.13
Constellation build-out and dense 5G synchronization demand
Medium-High (national export control regimes)
Middle East & Africa
11.7
1.01
Defense procurement and new satellite ground segment
Medium
South America
9.4
0.56
Telecom synchronization and research infrastructure
Low-Medium
Fastest-Growing: Asia-Pacific
Asia-Pacific expands at 12.9% CAGR, the highest of any region, and will approach North American value before 2030. China, Japan and South Korea drive demand through constellation programs and national timing infrastructure, while India adds defense PNT procurement and domestic assembly capacity. The Aerospace and Defense Electronics Market in the region is broadening as local integrators move from importing finished references to assembling subsystems around imported physics packages.
Most Mature: North America
North America holds 34% of global value at USD 3.80 billion in 2025, with growth of 10.6% CAGR led by defense budgets rather than new market creation. US procurement rules restricting certain foreign-sourced components shape vendor selection and favor domestic suppliers, which keeps pricing firm.
Europe and LAMEA
Europe reaches USD 2.69 billion in 2025, supported by Galileo second-generation work and naval EW programs; EU dual-use rules gate cross-border shipments.
Middle East & Africa grows at 11.7%, driven by GCC and Israeli defense modernization and satellite ground infrastructure.
South America is the smallest and slowest region at 9.4% CAGR, concentrated in telecom synchronization and academic research demand in Brazil and Argentina.
Supply Chain & Raw Material Dynamics: Atomic Clock Market
Upstream supply is narrow and geographically concentrated, which is the single largest structural risk in the market.
Material
Primary Source Regions
Supply Risk
Price Trend (2022-2025)
Rubidium and rubidium salts
Namibia, Canada, Zimbabwe
High
Rising, +15% to +20%
Cesium and pollucite ore
Canada (Tanco), Namibia
Very High
Rising, +20% to +30%
High-purity hydrogen and deuterium
United States, Europe
Low-Medium
Stable
Sapphire resonator material
United States, China, Russia
Medium
Stable to +5%
Laser diodes and VCSELs
United States, Germany, Japan
Medium-High
Rising, +10% to +15%
The Rubidium Metal Market is a byproduct of lithium and cesium processing, so output responds to mining economics in unrelated end markets rather than to atomic clock demand. When lithium producers cut throughput, rubidium availability tightens within two to three quarters.
Key supply chain considerations:
Cesium supply depends on very few pollucite deposits, and historical outages have caused multi-quarter delivery gaps for cesium-beam standards.
Physics package assembly depends on specialty laser diodes with limited qualified supplier counts, creating single-source exposure for several OEMs.
Burn-in and calibration capacity, not component supply, is the practical bottleneck for premium cesium and maser units.
Vertical integration into isotope purification and physics package assembly is the most common mitigation strategy among leaders.
Price direction through 2028 is upward for rubidium and cesium inputs, which will support continued price increases for finished references and reinforce the margin advantage of integrated suppliers.
Export, Cross-Border Trade & Tariff Impact on Atomic Clock Market
Atomic clocks and their subassemblies are treated as dual-use technology rather than ordinary electronics, so trade flows are governed by licensing regimes as much as by tariff schedules.
Major Trade Corridors and Controls
Corridor
Direction
Governing Regime
Notes
United States to Europe and Asia-Pacific
Export
ITAR Category XI, EAR, Wassenaar
License-dependent, 60-180 day processing
Switzerland and Germany to global markets
Export
Swiss and EU dual-use Regulation 2021/821
Strong precision timing export base
Israel to Europe, Asia, North America
Export
Israeli Defense Export Controls
Defense-grade references
India, South Korea, GCC from US, EU, Japan
Import
National import licensing
Net importers of finished references
Trade flow characteristics:
The United States, Switzerland, Germany, France and Israel are net exporters of precision time and frequency hardware.
India, South Korea, Japan and the GCC states are structurally net importers, dependent on licensed supply for defense and space programs.
Classification is commonly handled under HS heading 9105 for clocks and under 8543.70 for electronic assemblies, though most defense-grade trade clears through licensing rather than tariff lines.
Tariff and Non-Tariff Impacts
Wassenaar Arrangement controls on atomic frequency standards add 60 to 180 days to cross-border shipments and create inventory buffers that raise working capital needs by an estimated 10-15%.
The August 2023 Chinese export controls on gallium and germanium compounds raised lead times for oscillator and laser diode subassemblies by 8 to 14 weeks.
Tariff exposure is modest because duty rates on clocks are low in most markets; the binding constraint is licensing and end-use verification.
Substitution behavior is emerging, with Asian buyers expanding domestic assembly to reduce dependence on licensed imports.
Net effect: trade policy, not tariffs, determines the speed and cost of moving atomic clock hardware across borders, and licensing friction will keep regional supply chains partially duplicative through 2030.
Atomic Clock Market Segmentation
1. End User
1.1. Defense
2. Patrol Vessels?
2.1. Space
3. Application
3.1. Surveillance
3.2. Navigation
3.3. Electronic Warfare?
3.4. Telemetry
3.5. Communication
4. Type
4.1. Rubidium (Rb) Atomic Clock
4.2. Cesium (Cs) Atomic Clock
4.3. Hydrogen (H) Maser Atomic Clock
Atomic Clock Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Atomic Clock Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 11.42% from 2020-2034
Segmentation
By End User
Defense
By Patrol Vessels?
Space
By Application
Surveillance
Navigation
Electronic Warfare?
Telemetry
Communication
By Type
Rubidium (Rb) Atomic Clock
Cesium (Cs) Atomic Clock
Hydrogen (H) Maser Atomic Clock
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by End User
5.1.1. Defense
5.2. Market Analysis, Insights and Forecast - by Patrol Vessels?
5.2.1. Space
5.3. Market Analysis, Insights and Forecast - by Application
5.3.1. Surveillance
5.3.2. Navigation
5.3.3. Electronic Warfare?
5.3.4. Telemetry
5.3.5. Communication
5.4. Market Analysis, Insights and Forecast - by Type
5.4.1. Rubidium (Rb) Atomic Clock
5.4.2. Cesium (Cs) Atomic Clock
5.4.3. Hydrogen (H) Maser Atomic Clock
5.5. Market Analysis, Insights and Forecast - by Region
5.5.1. North America
5.5.2. South America
5.5.3. Europe
5.5.4. Middle East & Africa
5.5.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by End User
6.1.1. Defense
6.2. Market Analysis, Insights and Forecast - by Patrol Vessels?
6.2.1. Space
6.3. Market Analysis, Insights and Forecast - by Application
6.3.1. Surveillance
6.3.2. Navigation
6.3.3. Electronic Warfare?
6.3.4. Telemetry
6.3.5. Communication
6.4. Market Analysis, Insights and Forecast - by Type
6.4.1. Rubidium (Rb) Atomic Clock
6.4.2. Cesium (Cs) Atomic Clock
6.4.3. Hydrogen (H) Maser Atomic Clock
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by End User
7.1.1. Defense
7.2. Market Analysis, Insights and Forecast - by Patrol Vessels?
7.2.1. Space
7.3. Market Analysis, Insights and Forecast - by Application
7.3.1. Surveillance
7.3.2. Navigation
7.3.3. Electronic Warfare?
7.3.4. Telemetry
7.3.5. Communication
7.4. Market Analysis, Insights and Forecast - by Type
7.4.1. Rubidium (Rb) Atomic Clock
7.4.2. Cesium (Cs) Atomic Clock
7.4.3. Hydrogen (H) Maser Atomic Clock
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by End User
8.1.1. Defense
8.2. Market Analysis, Insights and Forecast - by Patrol Vessels?
8.2.1. Space
8.3. Market Analysis, Insights and Forecast - by Application
8.3.1. Surveillance
8.3.2. Navigation
8.3.3. Electronic Warfare?
8.3.4. Telemetry
8.3.5. Communication
8.4. Market Analysis, Insights and Forecast - by Type
8.4.1. Rubidium (Rb) Atomic Clock
8.4.2. Cesium (Cs) Atomic Clock
8.4.3. Hydrogen (H) Maser Atomic Clock
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by End User
9.1.1. Defense
9.2. Market Analysis, Insights and Forecast - by Patrol Vessels?
9.2.1. Space
9.3. Market Analysis, Insights and Forecast - by Application
9.3.1. Surveillance
9.3.2. Navigation
9.3.3. Electronic Warfare?
9.3.4. Telemetry
9.3.5. Communication
9.4. Market Analysis, Insights and Forecast - by Type
9.4.1. Rubidium (Rb) Atomic Clock
9.4.2. Cesium (Cs) Atomic Clock
9.4.3. Hydrogen (H) Maser Atomic Clock
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by End User
10.1.1. Defense
10.2. Market Analysis, Insights and Forecast - by Patrol Vessels?
10.2.1. Space
10.3. Market Analysis, Insights and Forecast - by Application
10.3.1. Surveillance
10.3.2. Navigation
10.3.3. Electronic Warfare?
10.3.4. Telemetry
10.3.5. Communication
10.4. Market Analysis, Insights and Forecast - by Type
Table 58: Rest of Asia Pacific Atomic Clock Market Revenue (billion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Primary research accounts for 70-80% of total project effort, organized around in-depth interviews (IDIs), structured surveys and expert panels with participants drawn from the exact Atomic Clock Market value chain.
Company types covered in primary sampling (see chartdatacompanies): chip-scale and rubidium core oscillator (physics package) manufacturers; military PNT subsystem integrators and defense prime contractors; space-qualified timing module and satellite payload suppliers; rubidium, cesium and hydrogen isotope refiners and vacuum tube, laser diode and sapphire resonator suppliers; national metrology institute and calibration laboratory technical staff.
Stakeholder designations interviewed (see chartdatastakeholders): Chief Timing & Frequency Engineer; Defense PNT Program Director; RF/Avionics Systems Architect; Supply Chain & Sourcing Manager; PNT Standards & Compliance Lead.
Industry associations and regulatory bodies consulted: Bureau International des Poids et Mesures (BIPM), National Institute of Standards and Technology (NIST) Time and Frequency Division, European Space Agency (ESA) Navigation Directorate, and ITU-R Study Group 7 for network synchronization recommendations.
Interview program: 140-180 primary interactions per reporting cycle, split across OEM engineering, defense procurement, component supply and standards roles, with a minimum 45-minute duration for qualitative interviews.
Rubidium, Cesium & Hydrogen Isotope Refiners and Tube/Diode Suppliers
10%
Telecom Synchronization Platform Providers
8%
Secondary Research & Industry Benchmarking
Secondary research accounts for 20-30% of total effort and is used for baseline validation, historical trend construction and cross-checking primary findings.
Financial and corporate databases used: Bloomberg, Factiva, Hoovers and PitchBook for filings, funding events, ownership structures and strategic transactions.
Government, standards and association sources: NIST, BIPM, ITU, ESA, and US Naval Observatory for timing standards, navigation program status and dual-use licensing references.
Trade associations and standards organizations: Alliance for Telecommunications Industry Solutions (ATIS) synchronization standards activity, IEEE Ultrasonics, Ferroelectrics and Frequency Control Society publications, and Wassenaar Arrangement dual-use list documentation.
Trade data sources: national customs databases and HS classification records for clocks (HS 9105) and electronic assemblies (HS 8543.70), reconciled against licensing disclosures.
Demand Modeling & Market Estimation
We run top-down and bottom-up methodologies simultaneously and reconcile them through multi-level data triangulation before publishing a single consolidated valuation.
Bottom-up build relies on specific quantitative inputs: (1) number of active defense PNT procurement programs with contracted timing subsystem content, by country and platform class; (2) annual satellite launches and replenishment rates requiring onboard frequency references, multiplied by units per payload; (3) average selling price per atomic clock module segmented by grade (commercial, industrial, MIL-STD-810, space-qualified); (4) replacement and recalibration cycles for rubidium standards in telecom base stations and test equipment.
Top-down build starts from aerospace and defense electronics spending envelopes and applies validated timing subsystem attachment rates, then cross-checks against vendor revenue disclosures and licensing volumes.
Segment, product type and regional splits are built independently and then reconciled to the global total; discrepancies above 3% trigger a re-interview round with the relevant supplier or procurement contact.
Estimated data accuracy is guaranteed at 85-90%, with a stated confidence band of plus or minus 5 to 7 percentage points on segment-level figures.
Data Accuracy & Quality Check
Multi-level data triangulation is applied at three layers: primary interview consensus, secondary database reconciliation, and cross-regional consistency checks.
Every report is updated to the date of purchase; all forecasts reflect the latest available filings, program status and trade data as of that date.
Quality gates include sanity checks against installed base math, price-volume consistency tests, and comparison of growth rates against historical five-year trajectories.
Any data point sourced from fewer than three independent confirmations is flagged as low-confidence and excluded from headline market sizing.
Final validation is conducted by a senior analyst and a peer reviewer before release, with documentation of assumptions and any unresolved variance retained in the project file.
Frequently Asked Questions
1. How are technological innovations and R&D trends reshaping the atomic clock industry?
Development activity has shifted toward chip-scale atomic clocks (CSACs) that cut size, weight and power by roughly 60% versus legacy rubidium modules, enabling deployment in tactical radios and small drones. Optical lattice and Rydberg-atom prototypes now demonstrate fractional frequency instability below 1E-18 in laboratory settings, with ruggedized defense variants targeted for qualification before 2030. Microchip Technology Incorporated and MacQsimal (CSEM) are among the vendors pushing physics-package miniaturization, while laser diode and vertical-cavity surface-emitting laser suppliers scale production for these designs.
2. What is the current market size and CAGR projection through 2033?
The Atomic Clock Market is valued at USD 11.19 billion in 2025 and is projected to reach USD 26.58 billion by 2033, expanding at an 11.42% CAGR over the 2026-2034 forecast window. Defense end users represent the largest revenue block at approximately 46% of 2025 value, followed by space and commercial timing applications. Growth is front-loaded in Asia-Pacific, which is forecast to expand at 12.9% annually, above the global average.
3. How do export-import dynamics and international trade flows affect atomic clock supply?
Atomic clocks and their subassemblies sit on dual-use control lists, including the Wassenaar Arrangement munitions and dual-use lists and US ITAR Category XI, so cross-border shipments require licensing rather than simple tariff clearance. The United States, Switzerland, Germany and Israel are net exporters of precision time and frequency hardware, while India, South Korea and the GCC states are net importers dependent on licensed supply. Licensing friction can add 60 to 180 days to delivery schedules, and the August 2023 Chinese export controls on gallium and germanium compounds indirectly raised component lead times for oscillator and laser diode assemblies.
4. Why do sustainability and ESG factors matter for atomic clock manufacturing?
Atomic clock production consumes scarce rubidium and cesium feedstocks, plus argon, high-purity hydrogen and sapphire resonator material, so material efficiency is a direct cost and compliance issue. Manufacturers face RoHS and REACH obligations, safe-handling rules for alkali metals, and customer audits demanding documented recycling of rubidium-bearing scrap, which recovers an estimated 25 to 35% of input metal at qualified refiners. Energy intensity per unit remains modest, but clean-room operation and extended burn-in testing dominate the operational carbon footprint.
5. Who are the notable players and what recent M&A or product launches have occurred?
Safran, Microchip Technology Incorporated, Oscilloquartz (Adtran Networks SE), Leonardo S.p.A., AccuBeat Ltd and VREMYA-CH JSC anchor the supplier base across rubidium, cesium and hydrogen maser categories. Microchip broadened commercial availability of its SA65 chip-scale atomic clock for industrial timing designs, while the Oscilloquartz portfolio was consolidated into Adtran Networks SE following the ADVA combination. Thermo Fisher Scientific Inc and Excelitas Technologies Corp supply adjacent instrumentation and photonics content that feeds atomic clock assembly lines.
6. Which region is growing fastest and where are emerging geographic opportunities?
Asia-Pacific is the fastest-growing region at a projected 12.9% CAGR, supported by constellation build-out in China, Japan and South Korea and dense 5G synchronization requirements. India is emerging as a procurement and assembly location, with defense PNT programs and national timing infrastructure creating first-order demand. Middle East & Africa follows at 11.7%, driven by defense modernization in the GCC and Israel and by new satellite ground segment investment.