Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Airport Sleeping Pods Market: 6.48% CAGR to 2033?
Airport Sleeping Pods Market
Airport Sleeping Pods Market: 6.48% CAGR to 2033?
Airport Sleeping Pods Market by Occupancy (Single Occupancy, Shared Occupancy), by Airport (International, Domestic), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Oct 4, 2026|Base Year : 2025|Pages : 234
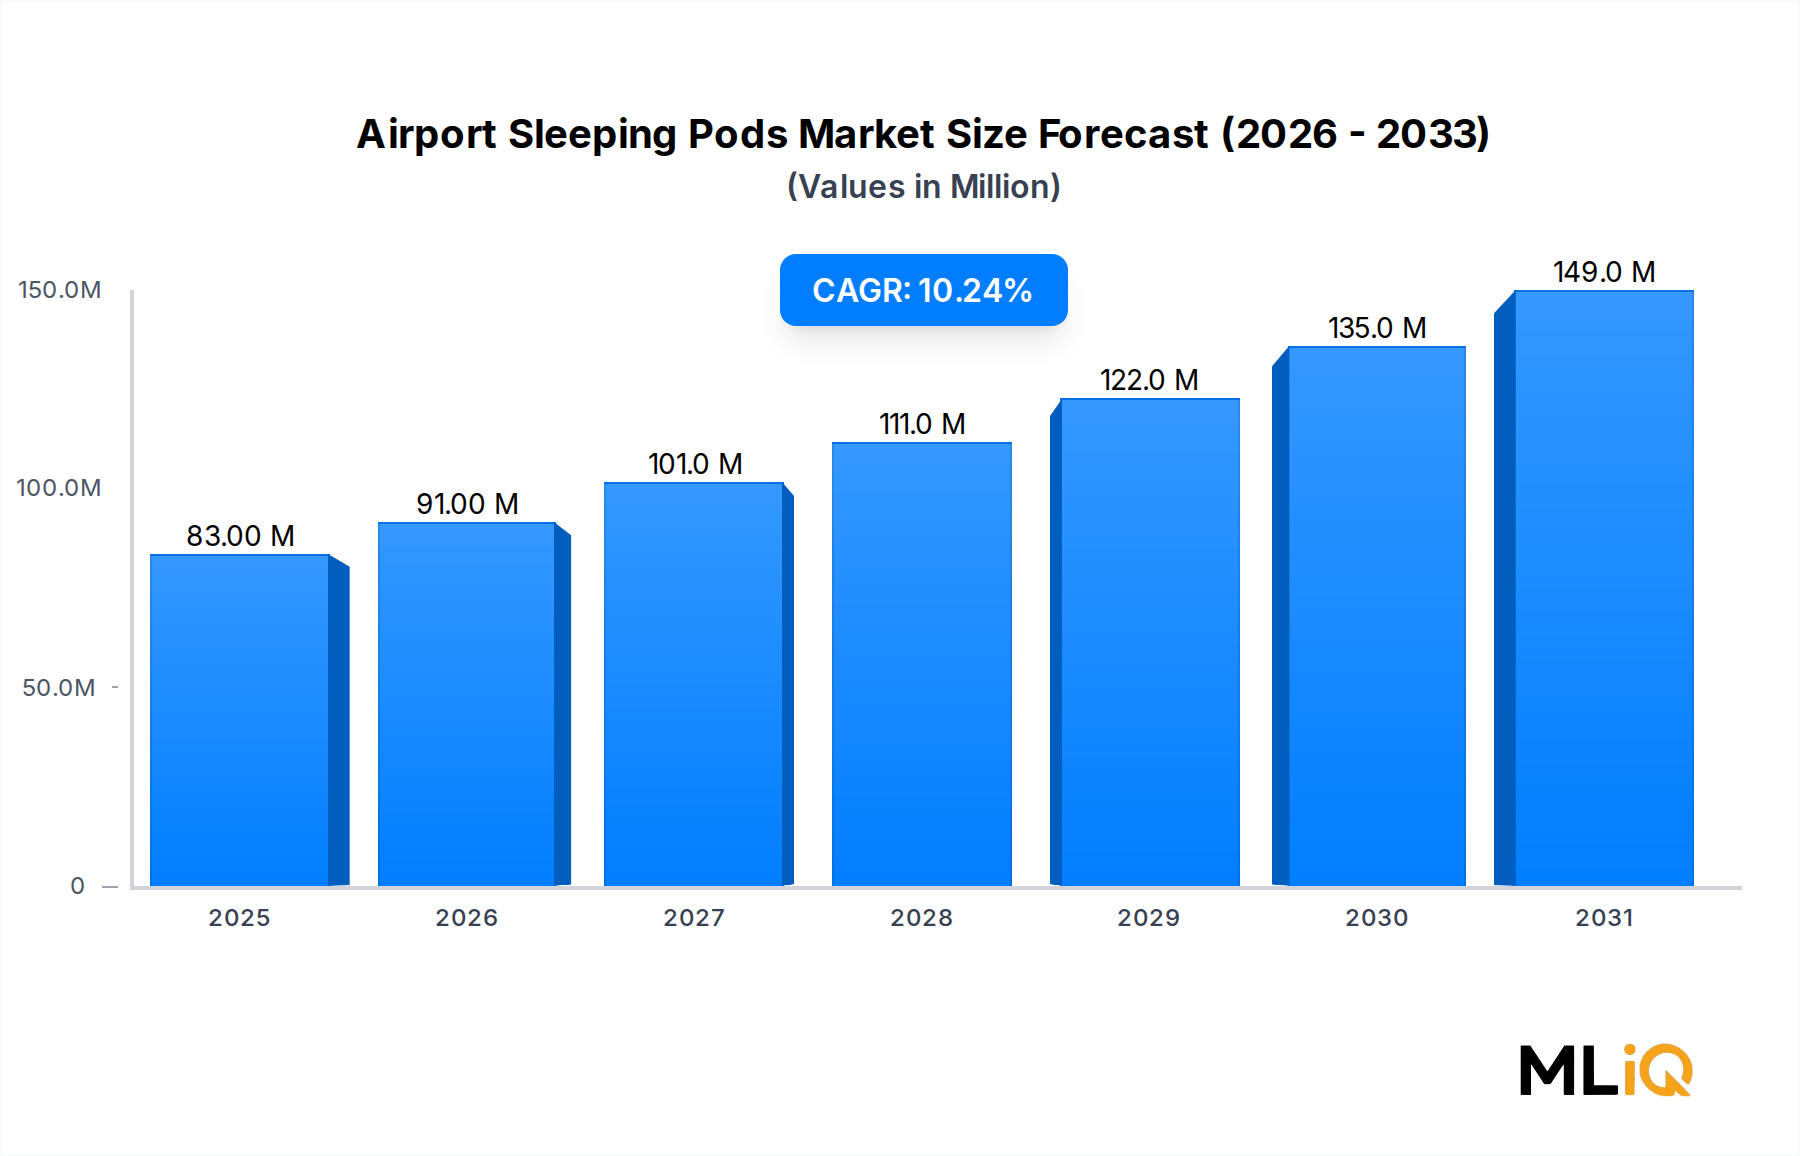
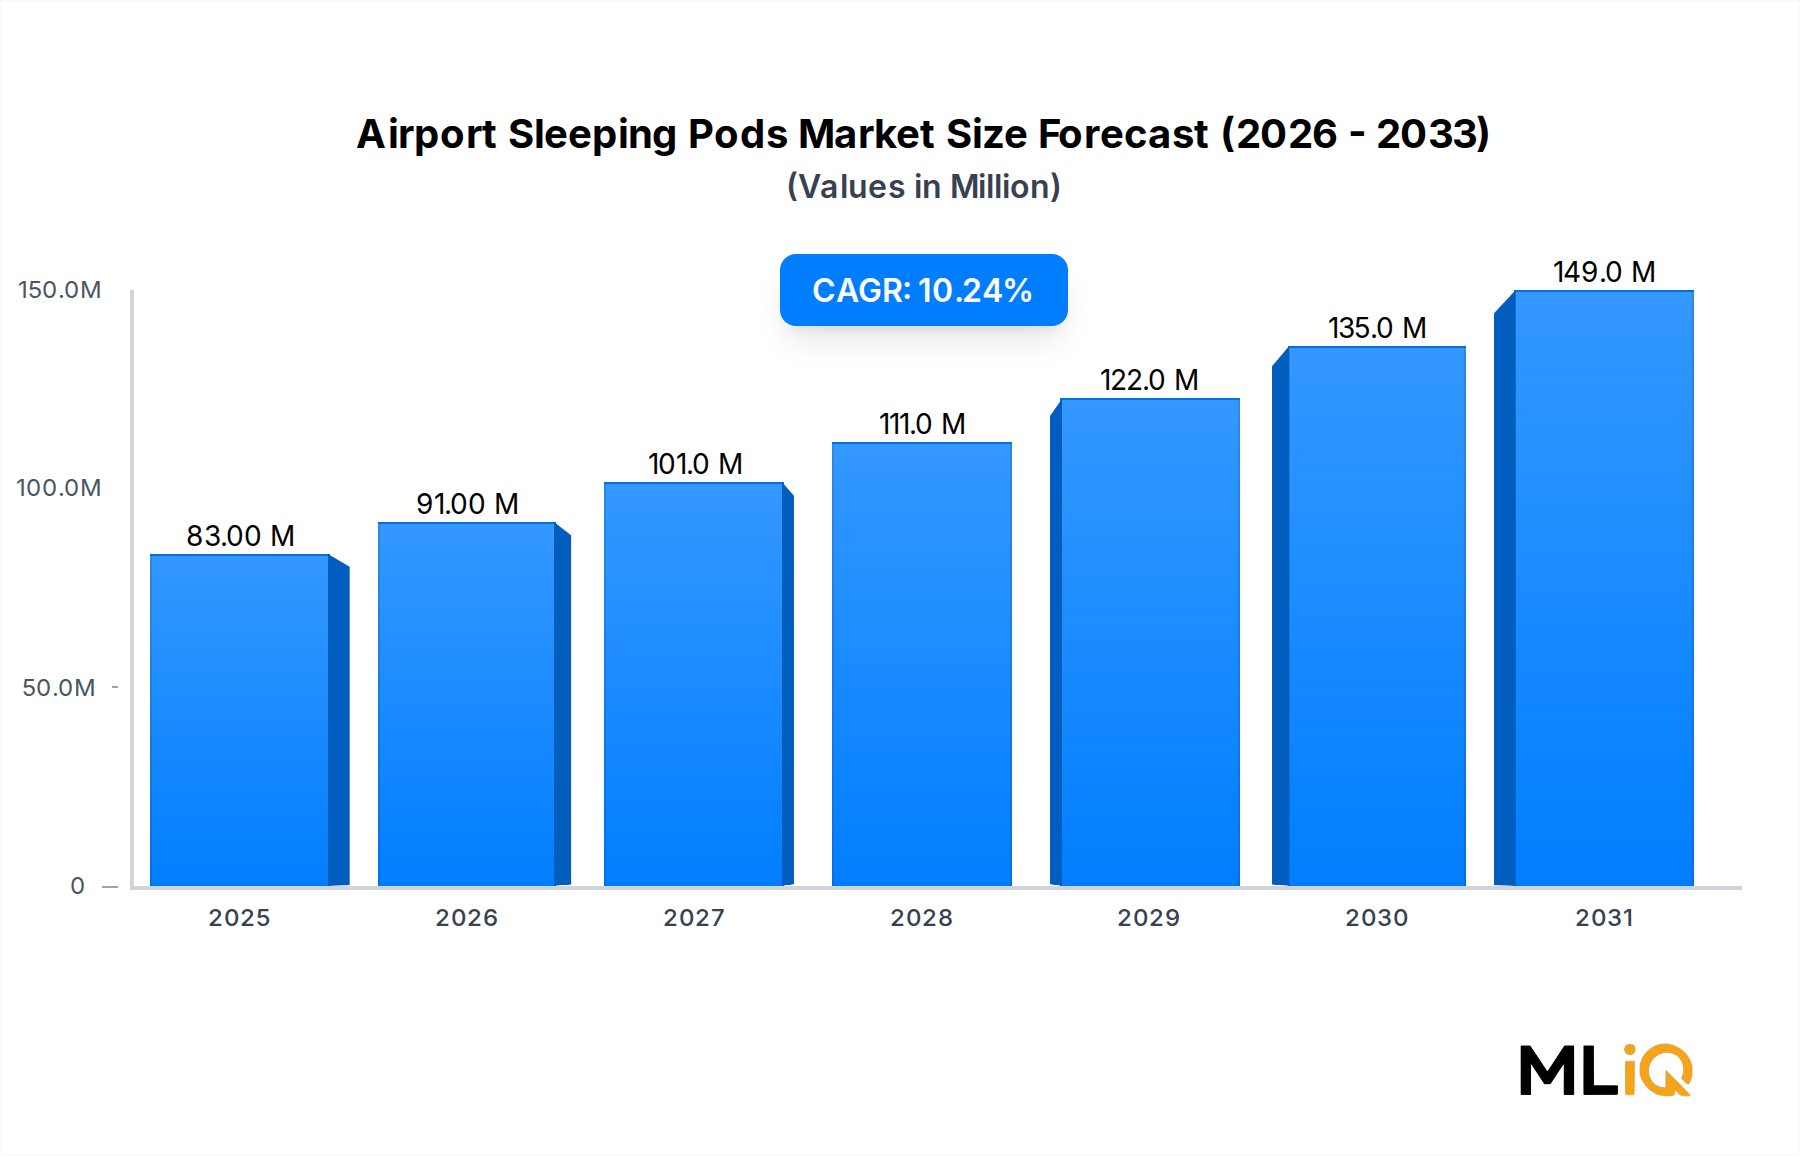
The Airport Sleeping Pods Market reached USD 87.12 million in 2025 and is projected to expand to USD 144.4 million by 2033, growing at a 6.48% CAGR. Demand is concentrated in international terminals where average layovers exceed four hours and passenger willingness to pay for privacy rises. Airport operators increasingly view pods as high-yield real estate: a single pod can generate USD 18-45 per hour at 65-78% utilization, outperforming many duty-free categories per square meter. The broader Airport Passenger Amenities Market is being reshaped by this shift, as concession budgets move from low-margin seating to monetized rest.
Airport Sleeping Pods Market Size (In Million)
150.0M
100.0M
50.0M
0
87.00 M
2025
93.00 M
2026
99.00 M
2027
105.0 M
2028
112.0 M
2029
119.0 M
2030
127.0 M
2031
Three macro forces drive the base case. First, long-haul recovery: global international passenger traffic reached 86% of 2019 levels in 2024, with transit hubs in Asia-Pacific and the Middle East adding capacity. Second, airport revenue diversification: non-aeronautical income now accounts for 38-42% of total airport revenues at leading hubs, and sleeping pods support premium amenity tiers. Third, passenger expectations: surveys indicate 57% of travelers on layovers over five hours would pay for a sleep pod if priced below USD 30 per hour. Within the International Airport Sleeping Pods Market, single-occupancy units dominate revenue because solo business travelers prioritize hygiene and security. The Single Occupancy Sleeping Pods Market is expected to hold over 68% of pod revenue through 2033, while Shared Occupancy Sleeping Pods Market units gain traction in domestic terminals with lower price points. Adjacent hardware demand from the Smart Sleeping Pods Market, including IoT locks and air-quality sensors, is expanding the bill of materials. Suppliers in the Aerospace Interiors Market are also pivoting, because pod shells, seating foam, and fire-rated composites share certification pathways with aircraft cabin components.
Near-term risks include airport capital expenditure cycles, fire-code approvals, and space constraints. A pod installation typically requires 25-40 square feet per unit, and terminal retrofits can cost USD 12,000-28,000 per pod before concession fees. Still, the revenue per square foot case remains strong. For operators, the strategic question is no longer whether to add sleep pods, but how to integrate booking, cleaning, and access control into existing airport apps. The forecast assumes no major global traffic shock and continued airport willingness to lease premium micro-spaces. The table above anchors valuation; subsequent sections detail segment, vendor, and regional drivers.
Segment Deep-Dive: International Airport Sleeping Pods Dominance in Airport Sleeping Pods Market
Segment
CAGR % (2025-2033)
Market Share % (2025)
Key Demand Driver
International Airport Sleeping Pods
7.1%
58%
Long layovers, premium transit passengers
Domestic Airport Sleeping Pods
5.2%
42%
Short-haul delays, budget traveler volume
Single Occupancy
6.9%
68%
Privacy, hygiene, solo business travel
Shared Occupancy
5.6%
32%
Lower price point, group and family use
The International Airport Sleeping Pods Market revenue is concentrated in hubs with 60+ million annual passengers and minimum connection times above 90 minutes. These airports can support 12-40 pod units per terminal, generating USD 0.9-2.4 million annual revenue per location at 70% utilization. The International Airport Sleeping Pods Market benefits from higher pricing: international transit passengers pay USD 25-45 per hour, compared with USD 12-22 in domestic terminals. This premium explains why international pods hold 58% of total market value despite representing fewer installation sites.
Domestic Terminal Dynamics
The Domestic Airport Sleeping Pods Market is more price-sensitive. Domestic layovers are shorter, often under three hours, and travelers increasingly use airport lounges or gate seating. Growth is therefore tied to delay-prone hubs and secondary cities where hotel supply near airports is limited. Shared Occupancy Sleeping Pods Market units fit this segment because they lower per-person cost to USD 8-15 per hour. However, shared units face higher cleaning and turnover costs, which can reduce gross margin by 400-600 basis points.
Occupancy and Margin Pressures
Single Occupancy Sleeping Pods Market maintains a 68% revenue share because solo travelers represent the highest willingness to pay. Pod OEMs compete on acoustic insulation, air circulation, and contactless access. Margin pressure comes from three areas: airport concession fees of 15-25% of gross revenue; housekeeping costs of USD 3.50-6.00 per turnover; and technology refresh cycles every 3-4 years. The Shared Occupancy Sleeping Pods Market faces additional scrutiny on privacy and safety, slowing approvals in some European airports.
International transit traffic recovery to 86% of 2019 levels by 2024
High
Short term
Driver
Non-aeronautical revenue targets: 38-42% of airport income
High
Medium term
Driver
Passenger willingness to pay USD 25-45/hour for privacy
High
Short term
Driver
Smart Sleeping Pods Market IoT sensors cut vacancy by 15-20%
Medium
Medium term
Restraint
Terminal space constraints: 25-40 sq ft per pod
High
Long term
Restraint
Fire and building code approvals vary by country
Medium
Long term
Restraint
Concession fees of 15-25% of gross revenue
High
Short term
Restraint
Housekeeping labor shortages in North America and Europe
Medium
Short term
The primary growth engine is the conversion of layover time into paid rest. Airports with 50+ million annual passengers and international transfer rates above 25% offer the strongest pod economics. For example, a terminal with 20 pods at 70% utilization and USD 30 average hourly rate generates roughly USD 3.7 million in annual pod revenue before concession fees. The Airport Wellness Pods Market is also emerging as a sister category, combining sleep, massage, and wellness services in a single footprint. This blurring of categories expands the addressable space for operators that already hold airport concession contracts.
Restraints are mostly structural. Terminal space is finite, and airport planners often prioritize retail, lounges, and security lanes. Fire codes in the United States and European Union require sprinkler coverage, smoke detection, and egress paths that can add USD 3,000-7,000 per pod in compliance costs. Labor shortages for housekeeping and cleaning staff have pushed per-turn costs up by 12-18% since 2021 in North America. Currency volatility also affects imported pod hardware, since many components are invoiced in USD or EUR. Finally, passenger adoption depends on visible wayfinding and digital booking integration; poorly located pods can suffer utilization below 45%, undermining the business case.
GoSleep: Focused on hard-shell sleeping pods with integrated luggage storage and touchscreen controls. The company targets international terminals with high transfer volumes and has installations across the Middle East and Asia.
Aviserv: Operates airport sleep and shower facilities, including pod-like rest units. Its model bundles access with lounge services and appeals to transit passengers in the Middle East.
Metronaps: Provides energy pods and rest furniture for corporate and airport wellness zones. Its products are often installed in premium lounges rather than gate-side terminals.
Napcabs: Known for soundproof cabins that support both sleep and work. The company has a strong European footprint, including Berlin Brandenburg Airport.
Snooze at My Space: Offers semi-private sleeping units designed for budget domestic terminals. The company competes on lower capital expenditure and fast installation.
9hours: Positions pods as premium capsule hotel-style accommodations. The brand targets long-layover international travelers willing to pay for a hotel-like experience.
iGA: Combines sleep pods with digital booking and access control. The company focuses on Asia-Pacific hubs where mobile-first passenger behavior is advanced.
Snoozecub: Supplies compact modular pods for domestic and regional airports. Its modular design reduces installation downtime and fits constrained terminal spaces.
Strategic Milestones & Recent Developments in Airport Sleeping Pods Market
Date
Company
Event Type
Impact
Aug 2022
Chennai International Airport
Launch
Four bed-sized Sleepzo capsules added for transit passengers
Feb 2022
Berlin Brandenburg Airport
Launch
Soundproof NapCabs installed for work and sleep during layovers
August 2022: Chennai International Airport launched Sleepzo sleeping pods, adding four bed-sized capsules for transit passengers. The deployment signaled growing interest in sleep pods among Indian airports, where international transit volumes have risen above 70% of pre-pandemic levels.
February 2022: Berlin Brandenburg Airport introduced soundproof NapCabs, giving passengers a place to relax or work during longer layovers. The installation reinforced Europe as a leading adopter of premium pod formats, particularly in airports with high business-traveler mixes.
2023-2025: Pod vendors expanded into new geographies, with GoSleep, Snoozecub, and iGA targeting hubs in the Middle East and Asia-Pacific. These moves increased competitive intensity and pushed airport concession teams to standardize cleaning, booking, and safety protocols.
Domestic delay recovery and limited airport hotels
Low
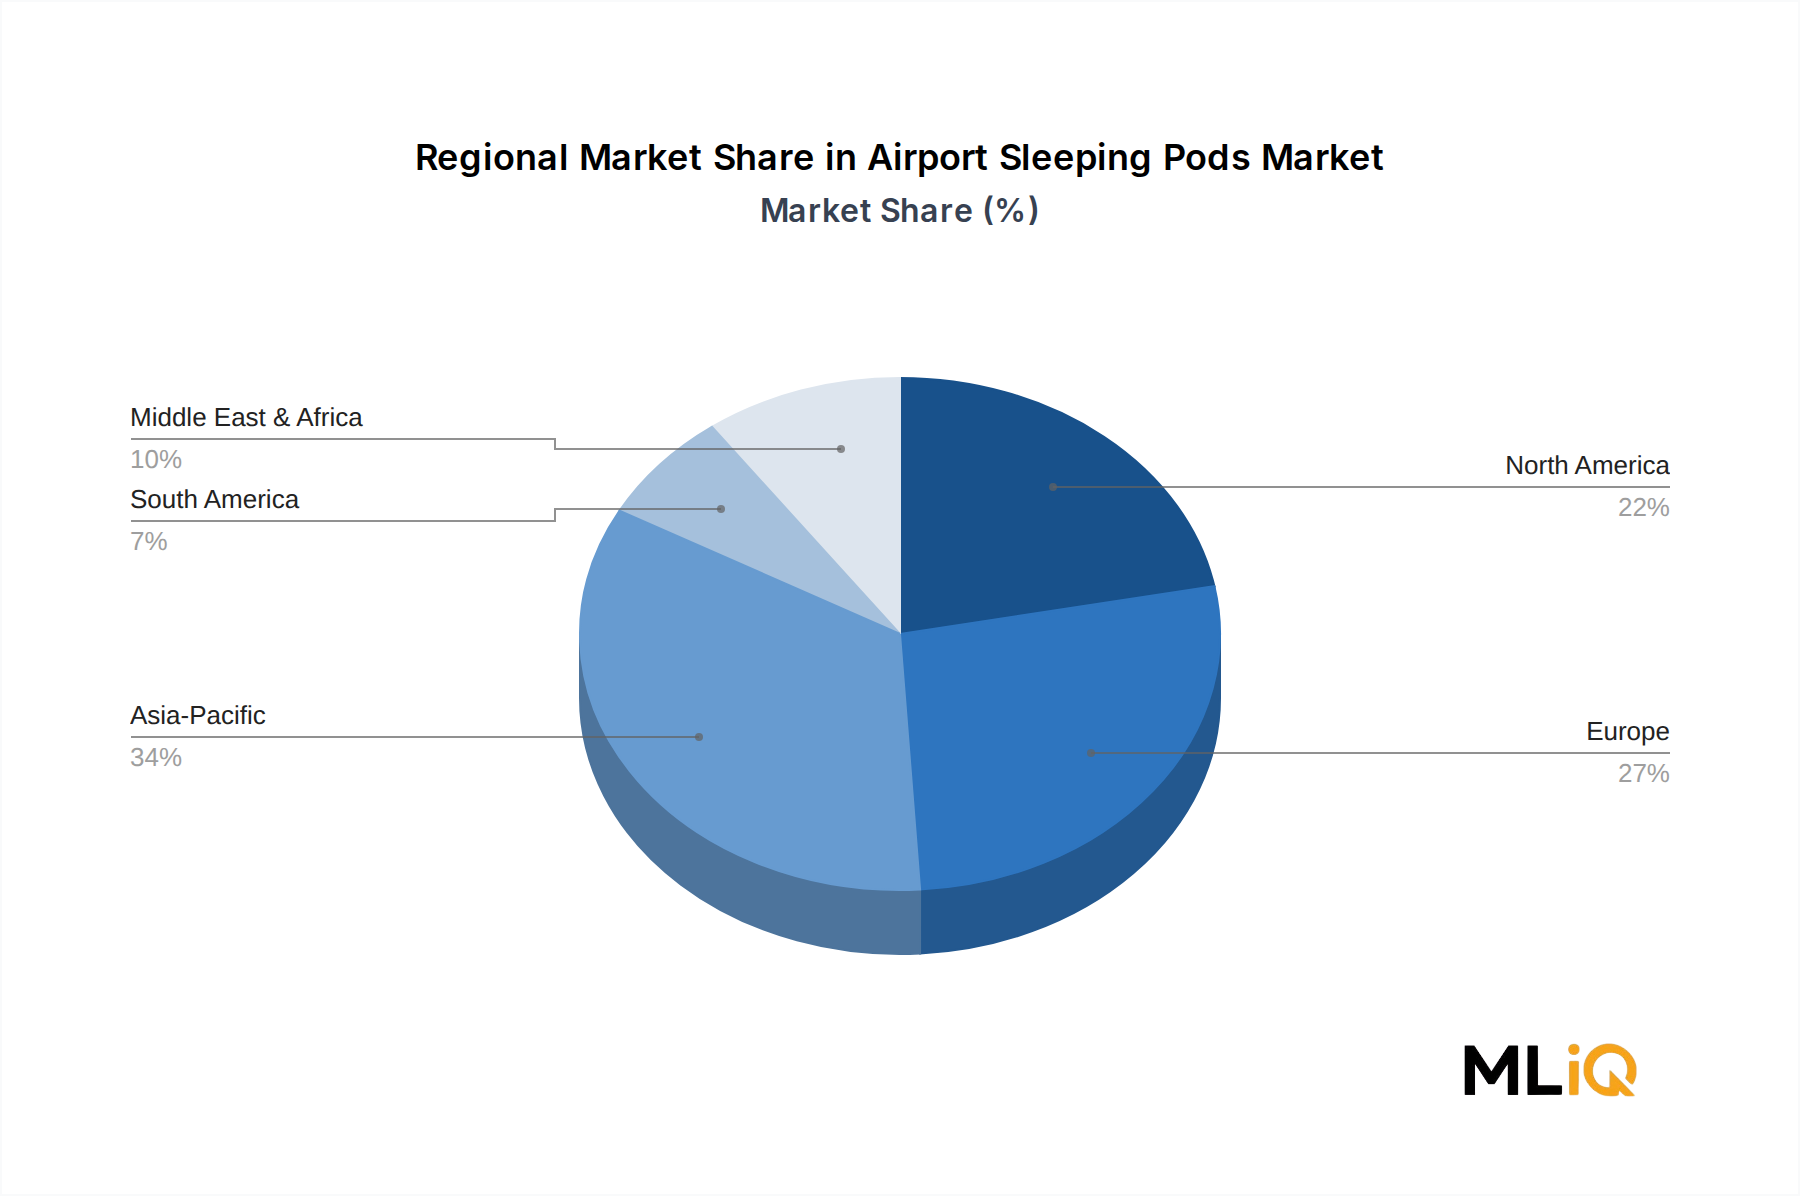
Asia-Pacific is the fastest-growing corridor, supported by China, India, and ASEAN hub expansion. The region accounted for 30.0% of global pod revenue in 2025, and new terminal projects in India and Indonesia are specifying sleep pod zones as part of passenger experience programs. In China, international transit throughput has recovered to 82% of 2019 levels, creating demand at airports such as Shanghai Pudong and Guangzhou Baiyun.
North America remains the most mature value market despite a lower CAGR. High labor costs and strict fire codes raise installation expenses, but airports in the United States and Canada enjoy strong willingness to pay. Europe is similarly mature, with Germany, the United Kingdom, and France leading pod deployments. EU passenger rights regulations indirectly support pod demand because airlines must provide rebooking and accommodations during disruptions, and pods offer a lower-cost alternative to airport hotels.
Middle East & Africa is a high-growth, premium corridor. Mega-hubs in the GCC use sleep pods to differentiate long-haul connections, and luxury positioning supports rates above USD 40 per hour. South America is the smallest market, constrained by lower international transit volumes and limited airport concession budgets. However, domestic delays in Brazil and Argentina create niche opportunities for basic pods. Across all regions, the critical success factor is aligning pod capacity with layover duration and terminal layout.
Global pod supply chains are cross-border by design. Hard-shell pods, electronic locks, and HVAC modules are often manufactured in China, Germany, and South Korea, then shipped to airport integrators in North America, the Middle East, and Europe. Trade classification typically follows furniture or prefabricated building codes, exposing shipments to tariffs that range from 5% to 25% depending on destination and material composition.
Trade Corridor
Primary Flow
Tariff Exposure
Non-Tariff Barrier
China to United States
Pod shells, electronics, seating foam
10-25%
UL certification, fire testing
Germany to Middle East
Premium soundproof cabins
5-10%
Local content rules
South Korea to Europe
Smart access modules, sensors
0-6%
CE marking, GDPR compliance
United States to Canada
Control systems, booking software
0-5%
Bilingual labeling
Tariffs and freight costs can add 8-14% to landed pod costs. The United States Section 301 tariffs on Chinese goods increased electronic component costs by 12-18% for some vendors, prompting a shift toward assembly in Mexico and Vietnam. Non-tariff barriers matter equally: fire safety certificates, electrical safety markings, and data privacy rules for booking software can delay market entry by 6-12 months. For airport operators, cross-border procurement risk is managed through dual sourcing and modular designs that allow local final assembly.
Supply Chain & Raw Material Dynamics: Airport Sleeping Pods Market
Upstream inputs for sleeping pods include polycarbonate and ABS shells, aluminum frames, acoustic melamine foam, memory foam cushions, LED lighting, air-quality sensors, and contactless access modules. The Acoustic Insulation Materials Market is a critical adjacent supply base because pod noise reduction targets of 25-35 dB require dense foam and composite barriers. Price volatility in petrochemical-derived foam and polycarbonate resin directly affects pod bill-of-materials costs.
Input
Share of BOM Cost
2023-2025 Price Trend
Supply Risk
Polycarbonate/ABS shell
24-30%
Up 6-9%
Medium
Acoustic foam
12-17%
Up 4-7%
High
Aluminum frame
10-14%
Stable to up 3%
Low
Electronics and sensors
18-22%
Down 2-5%
Medium
Memory foam and textiles
8-12%
Up 5-8%
Medium
Supply chain disruptions from 2021-2023 exposed dependence on single-source electronics and foam suppliers. Lead times for custom access control modules stretched beyond 20 weeks, forcing vendors to hold higher inventory. In response, leading pod OEMs have qualified secondary suppliers in Mexico, Poland, and Vietnam. However, fire-rated foam remains concentrated among a few global producers, creating a bottleneck that can delay pod deliveries by 8-12 weeks. Operators can mitigate risk by specifying modular pod designs, standardizing component interfaces, and signing annual volume commitments with suppliers.
Airport Sleeping Pods Market Segmentation
1. Occupancy
1.1. Single Occupancy
1.2. Shared Occupancy
2. Airport
2.1. International
2.2. Domestic
Airport Sleeping Pods Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Airport Sleeping Pods Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 6.48% from 2020-2034
Segmentation
By Occupancy
Single Occupancy
Shared Occupancy
By Airport
International
Domestic
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Occupancy
5.1.1. Single Occupancy
5.1.2. Shared Occupancy
5.2. Market Analysis, Insights and Forecast - by Airport
5.2.1. International
5.2.2. Domestic
5.3. Market Analysis, Insights and Forecast - by Region
5.3.1. North America
5.3.2. South America
5.3.3. Europe
5.3.4. Middle East & Africa
5.3.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Occupancy
6.1.1. Single Occupancy
6.1.2. Shared Occupancy
6.2. Market Analysis, Insights and Forecast - by Airport
6.2.1. International
6.2.2. Domestic
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Occupancy
7.1.1. Single Occupancy
7.1.2. Shared Occupancy
7.2. Market Analysis, Insights and Forecast - by Airport
7.2.1. International
7.2.2. Domestic
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Occupancy
8.1.1. Single Occupancy
8.1.2. Shared Occupancy
8.2. Market Analysis, Insights and Forecast - by Airport
8.2.1. International
8.2.2. Domestic
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Occupancy
9.1.1. Single Occupancy
9.1.2. Shared Occupancy
9.2. Market Analysis, Insights and Forecast - by Airport
9.2.1. International
9.2.2. Domestic
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Occupancy
10.1.1. Single Occupancy
10.1.2. Shared Occupancy
10.2. Market Analysis, Insights and Forecast - by Airport
10.2.1. International
10.2.2. Domestic
11. Competitive Analysis
11.1. Company Profiles
11.1.1. GoSleep
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Aviserv
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. Metronaps
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. Napcabs
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Snooze at My Space
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. 9hours
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. iGA
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Snoozecub
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Airport Sleeping Pods Market Revenue Breakdown (millionusdmillion, %) by Region 2026 & 2034
Figure 2: North America Airport Sleeping Pods Market Revenue (millionusdmillion), by Occupancy 2026 & 2034
Figure 3: North America Airport Sleeping Pods Market Revenue Share (%), by Occupancy 2026 & 2034
Figure 4: North America Airport Sleeping Pods Market Revenue (millionusdmillion), by Airport 2026 & 2034
Figure 5: North America Airport Sleeping Pods Market Revenue Share (%), by Airport 2026 & 2034
Figure 6: North America Airport Sleeping Pods Market Revenue (millionusdmillion), by Country 2026 & 2034
Figure 7: North America Airport Sleeping Pods Market Revenue Share (%), by Country 2026 & 2034
Figure 8: South America Airport Sleeping Pods Market Revenue (millionusdmillion), by Occupancy 2026 & 2034
Figure 9: South America Airport Sleeping Pods Market Revenue Share (%), by Occupancy 2026 & 2034
Figure 10: South America Airport Sleeping Pods Market Revenue (millionusdmillion), by Airport 2026 & 2034
Figure 11: South America Airport Sleeping Pods Market Revenue Share (%), by Airport 2026 & 2034
Figure 12: South America Airport Sleeping Pods Market Revenue (millionusdmillion), by Country 2026 & 2034
Figure 13: South America Airport Sleeping Pods Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Airport Sleeping Pods Market Revenue (millionusdmillion), by Occupancy 2026 & 2034
Figure 15: Europe Airport Sleeping Pods Market Revenue Share (%), by Occupancy 2026 & 2034
Figure 16: Europe Airport Sleeping Pods Market Revenue (millionusdmillion), by Airport 2026 & 2034
Figure 17: Europe Airport Sleeping Pods Market Revenue Share (%), by Airport 2026 & 2034
Figure 18: Europe Airport Sleeping Pods Market Revenue (millionusdmillion), by Country 2026 & 2034
Figure 19: Europe Airport Sleeping Pods Market Revenue Share (%), by Country 2026 & 2034
Figure 20: Middle East & Africa Airport Sleeping Pods Market Revenue (millionusdmillion), by Occupancy 2026 & 2034
Figure 21: Middle East & Africa Airport Sleeping Pods Market Revenue Share (%), by Occupancy 2026 & 2034
Figure 22: Middle East & Africa Airport Sleeping Pods Market Revenue (millionusdmillion), by Airport 2026 & 2034
Figure 23: Middle East & Africa Airport Sleeping Pods Market Revenue Share (%), by Airport 2026 & 2034
Figure 24: Middle East & Africa Airport Sleeping Pods Market Revenue (millionusdmillion), by Country 2026 & 2034
Figure 25: Middle East & Africa Airport Sleeping Pods Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Asia Pacific Airport Sleeping Pods Market Revenue (millionusdmillion), by Occupancy 2026 & 2034
Figure 27: Asia Pacific Airport Sleeping Pods Market Revenue Share (%), by Occupancy 2026 & 2034
Figure 28: Asia Pacific Airport Sleeping Pods Market Revenue (millionusdmillion), by Airport 2026 & 2034
Figure 29: Asia Pacific Airport Sleeping Pods Market Revenue Share (%), by Airport 2026 & 2034
Figure 30: Asia Pacific Airport Sleeping Pods Market Revenue (millionusdmillion), by Country 2026 & 2034
Figure 31: Asia Pacific Airport Sleeping Pods Market Revenue Share (%), by Country 2026 & 2034
Table 46: Rest of Asia Pacific Airport Sleeping Pods Market Revenue (millionusdmillion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
70-80% primary research / 20-30% secondary research split for all market sizing and forecasting.
Company types surveyed: modular sleeping pod OEMs for airport terminals; polycarbonate shell fabricators for hard-shell sleeping pods; acoustic foam and insulation suppliers for noise-canceling pods; contactless access control integrators for pod booking systems; and airport concession operators managing sleep pod contracts.
Government and regulatory sources: FAA, EASA, and national building and fire code authorities.
Trade association and .org sources: ACI World, IATA, and airport concession reports.
No market research websites are used; all secondary data is triangulated against primary interviews. Every report is updated to the date of purchase.
Demand Modeling & Market Estimation
Top-down and bottom-up methodologies are used simultaneously and validated through multi-level data triangulation.
Bottom-up quantitative metrics: number of international transit passengers per airport annually; average layover duration exceeding 4 hours; sleep pod hourly utilization rate; average revenue per available pod per night; and airport concession space lease cost per square meter.
Segment-level models split by occupancy (single, shared) and airport type (international, domestic), then aggregated to global and regional valuations.
Estimated data accuracy level is guaranteed at 85-90%, with confidence intervals reported for each regional forecast.
Data Accuracy & Quality Check
Multi-level triangulation compares primary interview data with financial filings, airport concession disclosures, and trade databases.
Outlier detection removes pod utilization rates below 30% or above 95% unless validated by on-site evidence.
Cross-validation against ACI passenger traffic data and IATA long-haul recovery statistics ensures regional consistency.
Every report is updated to the date of purchase, with version control on all input assumptions and model outputs.
Frequently Asked Questions
1. How do export-import dynamics shape the Airport Sleeping Pods Market?
Cross-border flows are dominated by components rather than finished pods. Roughly 62% of pod hardware, including polycarbonate shells, electronic locks, and HVAC modules, is manufactured in Asia-Pacific and exported to North America and Europe. Tariffs of 5-25% and 8-14% landed cost premiums influence sourcing decisions, pushing vendors toward local assembly in Mexico, Poland, and Vietnam.
2. What raw materials and sourcing risks affect Airport Sleeping Pods Market supply chains?
Polycarbonate and ABS shells account for 24-30% of bill-of-materials cost, while acoustic melamine foam contributes 12-17%. Fire-rated foam is concentrated among a few global producers, creating lead times of 8-12 weeks during demand spikes. Vendors mitigate risk by dual-sourcing electronics and foam from suppliers in Mexico, Poland, and Vietnam.
3. What are the major challenges and restraints in the Airport Sleeping Pods Market?
Terminal space constraints require 25-40 square feet per pod, and concession fees consume 15-25% of gross revenue. Fire and building code approvals can add USD 3,000-7,000 per pod in compliance costs and delay deployment by 6-12 months. Housekeeping labor shortages in North America and Europe have raised per-turn cleaning costs by 12-18% since 2021.
4. Which disruptive technologies could reshape the Airport Sleeping Pods Market?
IoT-enabled Smart Sleeping Pods Market systems use occupancy sensors and dynamic pricing to cut vacancy by 15-20%. Contactless access, air-quality monitoring, and AI booking assistants are becoming standard, reducing staff needs. Emerging substitutes include airport micro-hotels and premium lounges that bundle sleep with showers and meals.
5. How are pricing trends and cost structures evolving in the Airport Sleeping Pods Market?
Hourly pod rates range from USD 12-22 in domestic terminals to USD 25-45 in international hubs, with premium GCC locations exceeding USD 40. Operators need 65-70% utilization to break even after concession fees, cleaning, and technology refresh costs. Concession fees of 15-25% and housekeeping costs of USD 3.50-6.00 per turnover are the largest variable expenses.
6. What are the barriers to entry and competitive moats in the Airport Sleeping Pods Market?
Securing a 5-10 year airport concession agreement is the primary moat, and only 8 vendors hold multi-airport contracts. Fire safety certifications, UL and CE markings, and data privacy compliance for booking software create 6-12 month entry delays. Incumbents also benefit from installation know-how, cleaning protocols, and relationships with airport revenue teams.