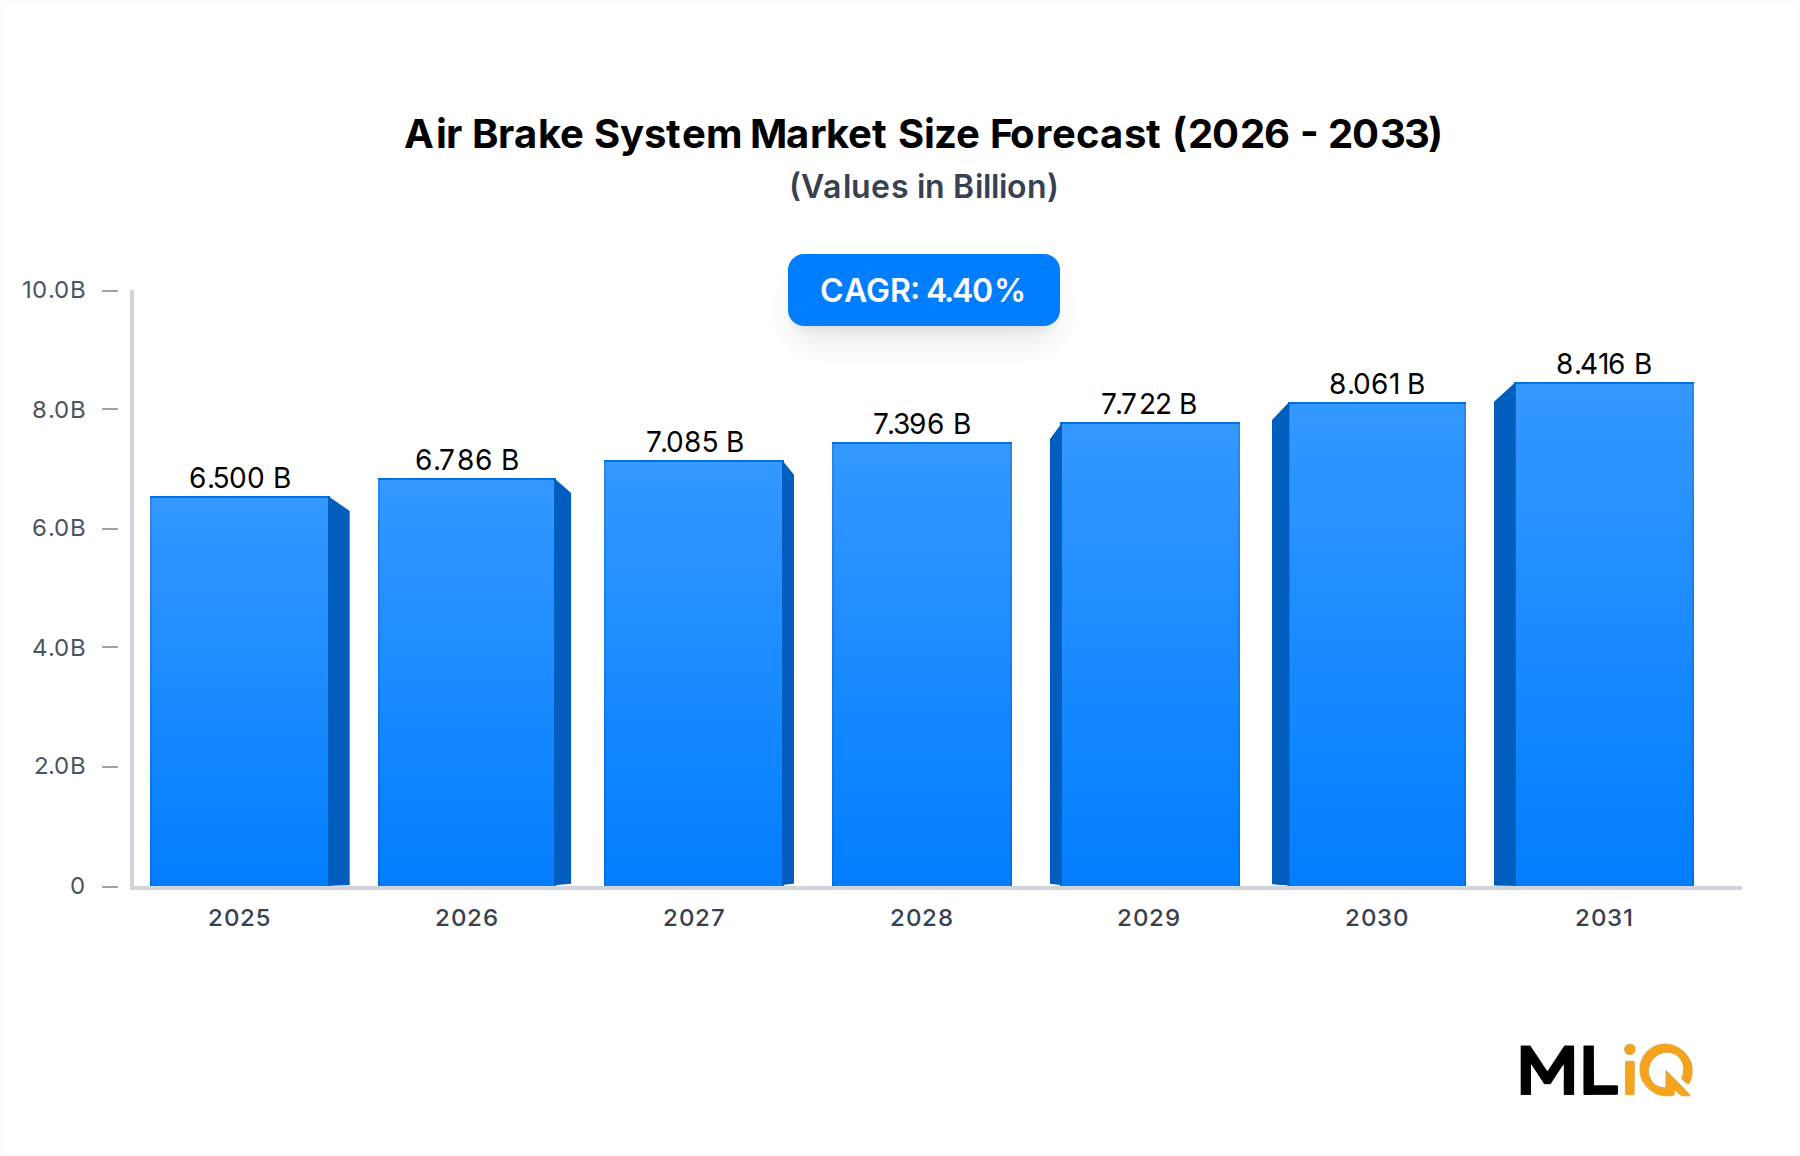
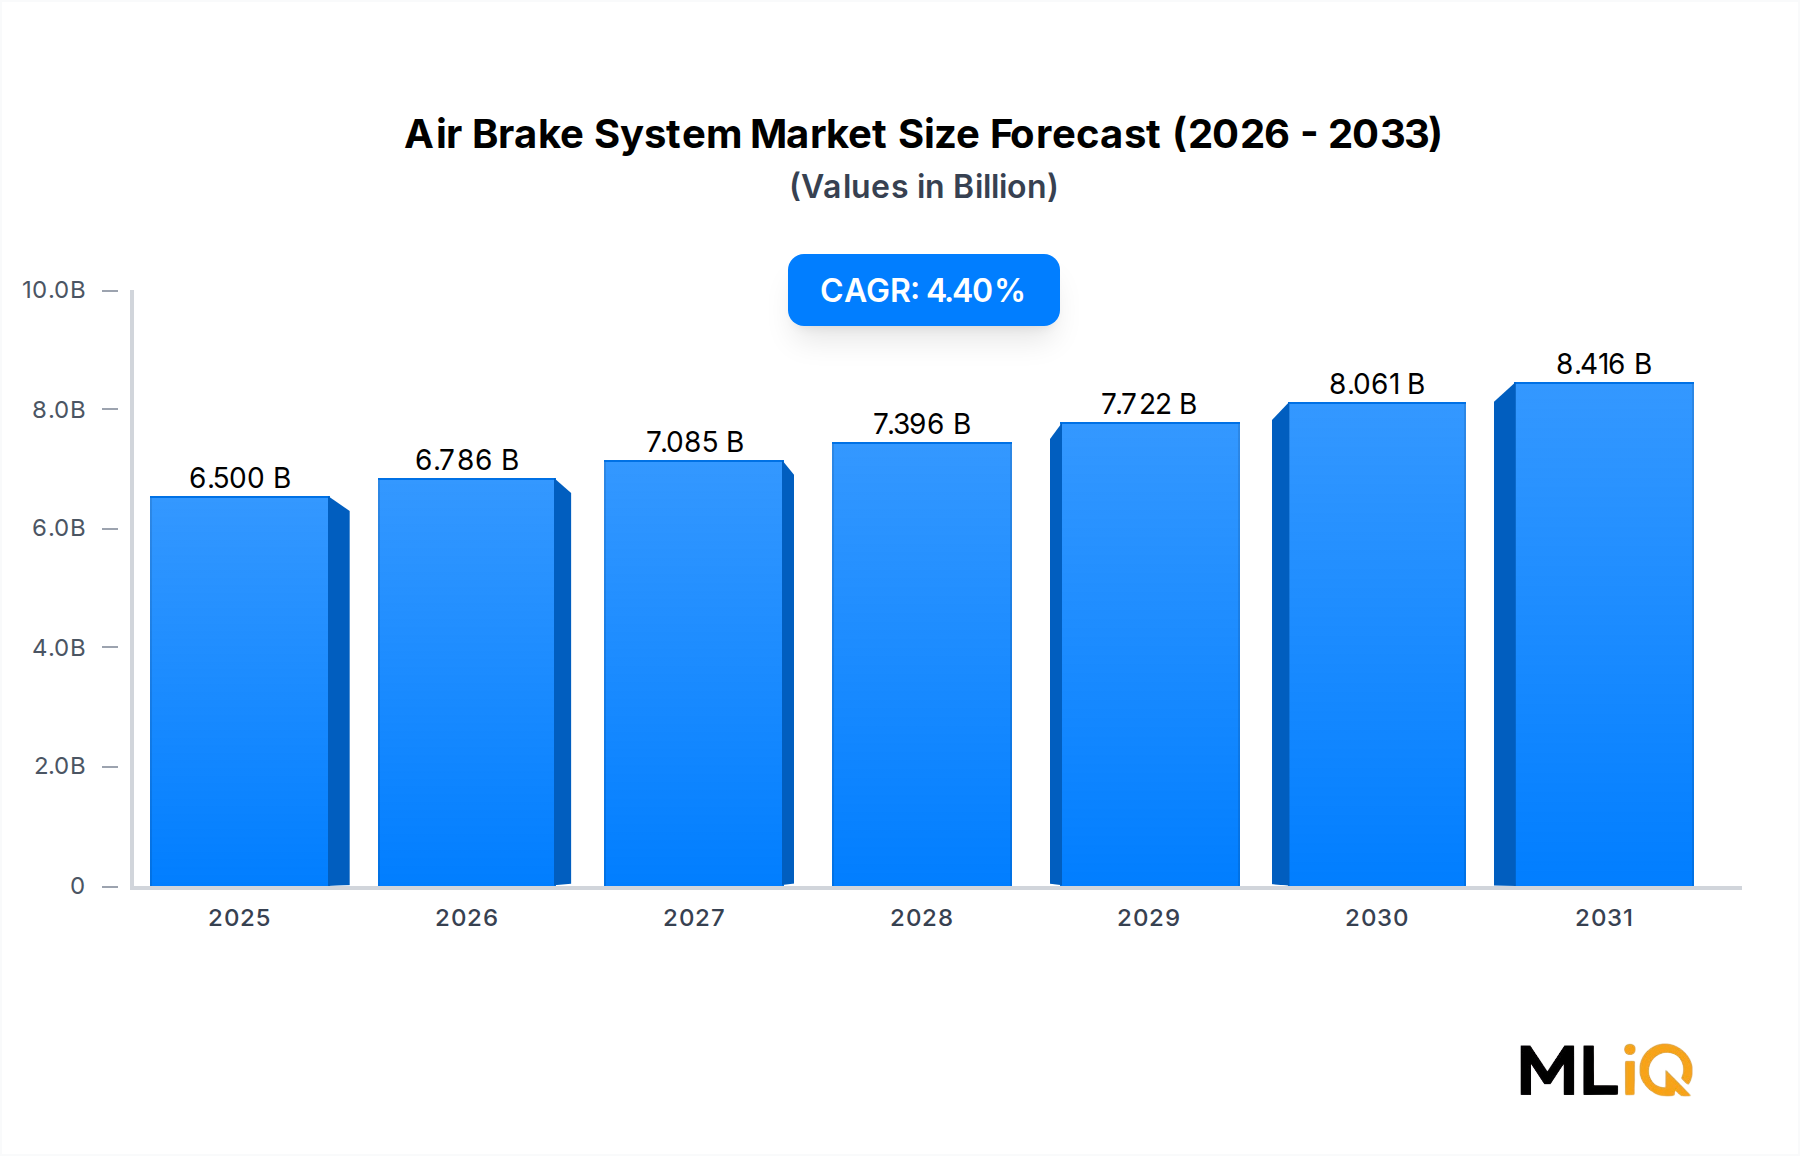
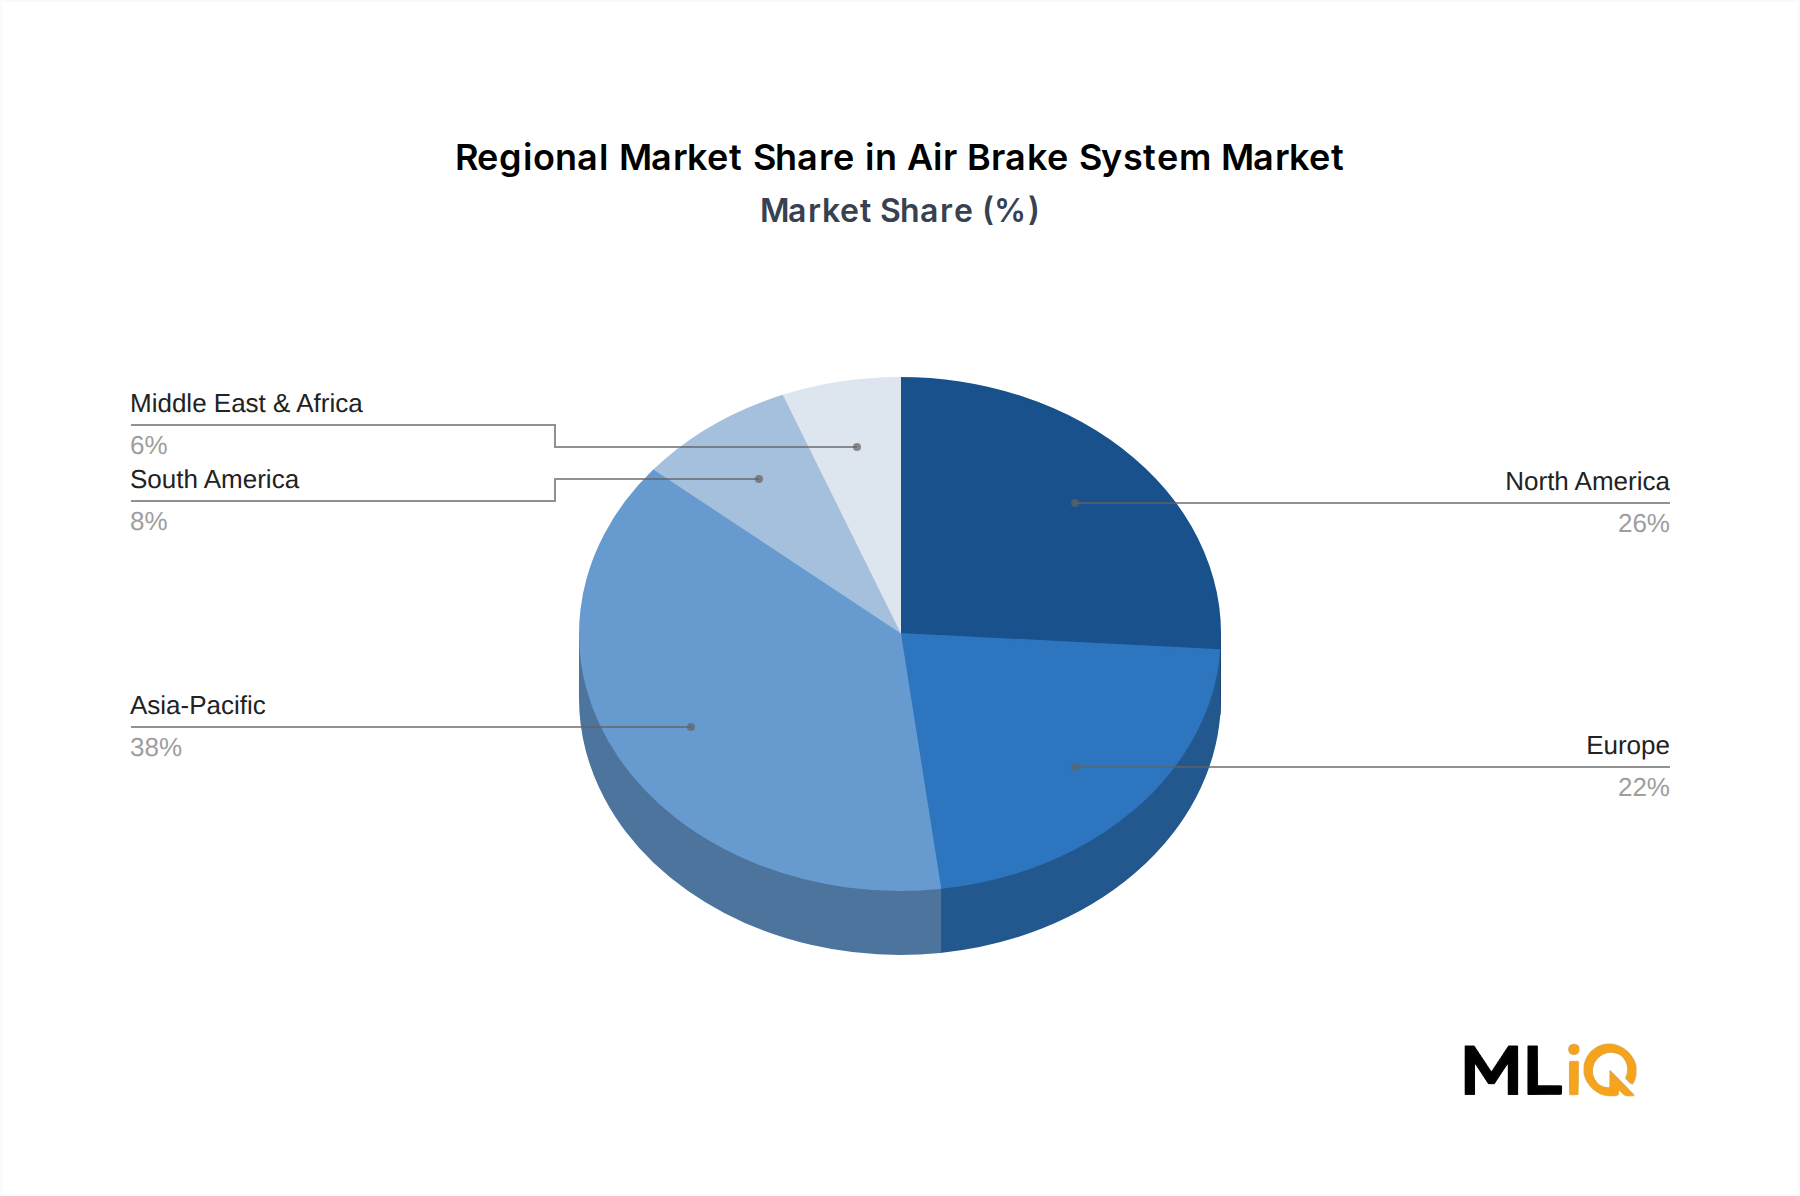
Several quantifiable forces are determining the growth trajectory of the Air Brake System Market across the 2025–2033 forecast window.
The primary driver is escalating commercial vehicle production. Global heavy-duty truck production volumes have rebounded post-pandemic, with China alone producing over 900,000 heavy trucks annually according to recent OICA data. Each new Class 8 truck or heavy bus requires a full pneumatic braking system encompassing compressors, governors, tanks, air dryers, foot valves, brake chambers, and slack adjusters—generating an average system revenue of approximately $1,200–$2,500 per vehicle depending on axle configuration and specification level.
Regulatory mandates constitute a structurally non-negotiable driver. The U.S. National Highway Traffic Safety Administration (NHTSA) has progressively tightened stopping distance requirements for loaded commercial vehicles, with the most recent rulemaking reducing the maximum permissible stopping distance for a loaded three-axle tractor by approximately 30% relative to prior standards. Compliance with these mandates is non-optional and directly drives air brake system upgrade cycles.
Electronic integration is an emerging demand catalyst. The proliferation of ADAS features in commercial vehicles—including automated emergency braking (AEB), adaptive cruise control, and lane-keeping assist—requires pneumatic brake systems capable of accepting electronic control inputs. This functional requirement is accelerating the transition from purely mechanical to electropneumatic architectures, increasing average system selling prices by an estimated 15–25%.
On the constraint side, raw material cost volatility presents a persistent margin risk. Air brake components rely heavily on gray cast iron, aluminum alloys, and engineering polymers, all of which experienced significant price inflation during 2021–2023. Although commodity prices have partially normalized, geopolitical supply chain disruptions continue to introduce cost uncertainty for tier-1 manufacturers.
A secondary constraint is the skilled labor shortage for brake system maintenance in developing regions, which suppresses aftermarket revenue realization and can create safety compliance gaps that, paradoxically, attract regulatory scrutiny and fleet operator caution.