Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Aerospace Fasteners Market CAGR 4.7% to $11.8B by 2034
Aerospace Fasteners Market
Aerospace Fasteners Market CAGR 4.7% to $11.8B by 2034
Aerospace Fasteners Market by Application (Commercial Aircraft, Military Aircraft, General Aviation), by Material (Aluminum, Steel, Superalloys, Titanium), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Sep 25, 2026|Base Year : 2025|Pages : 234
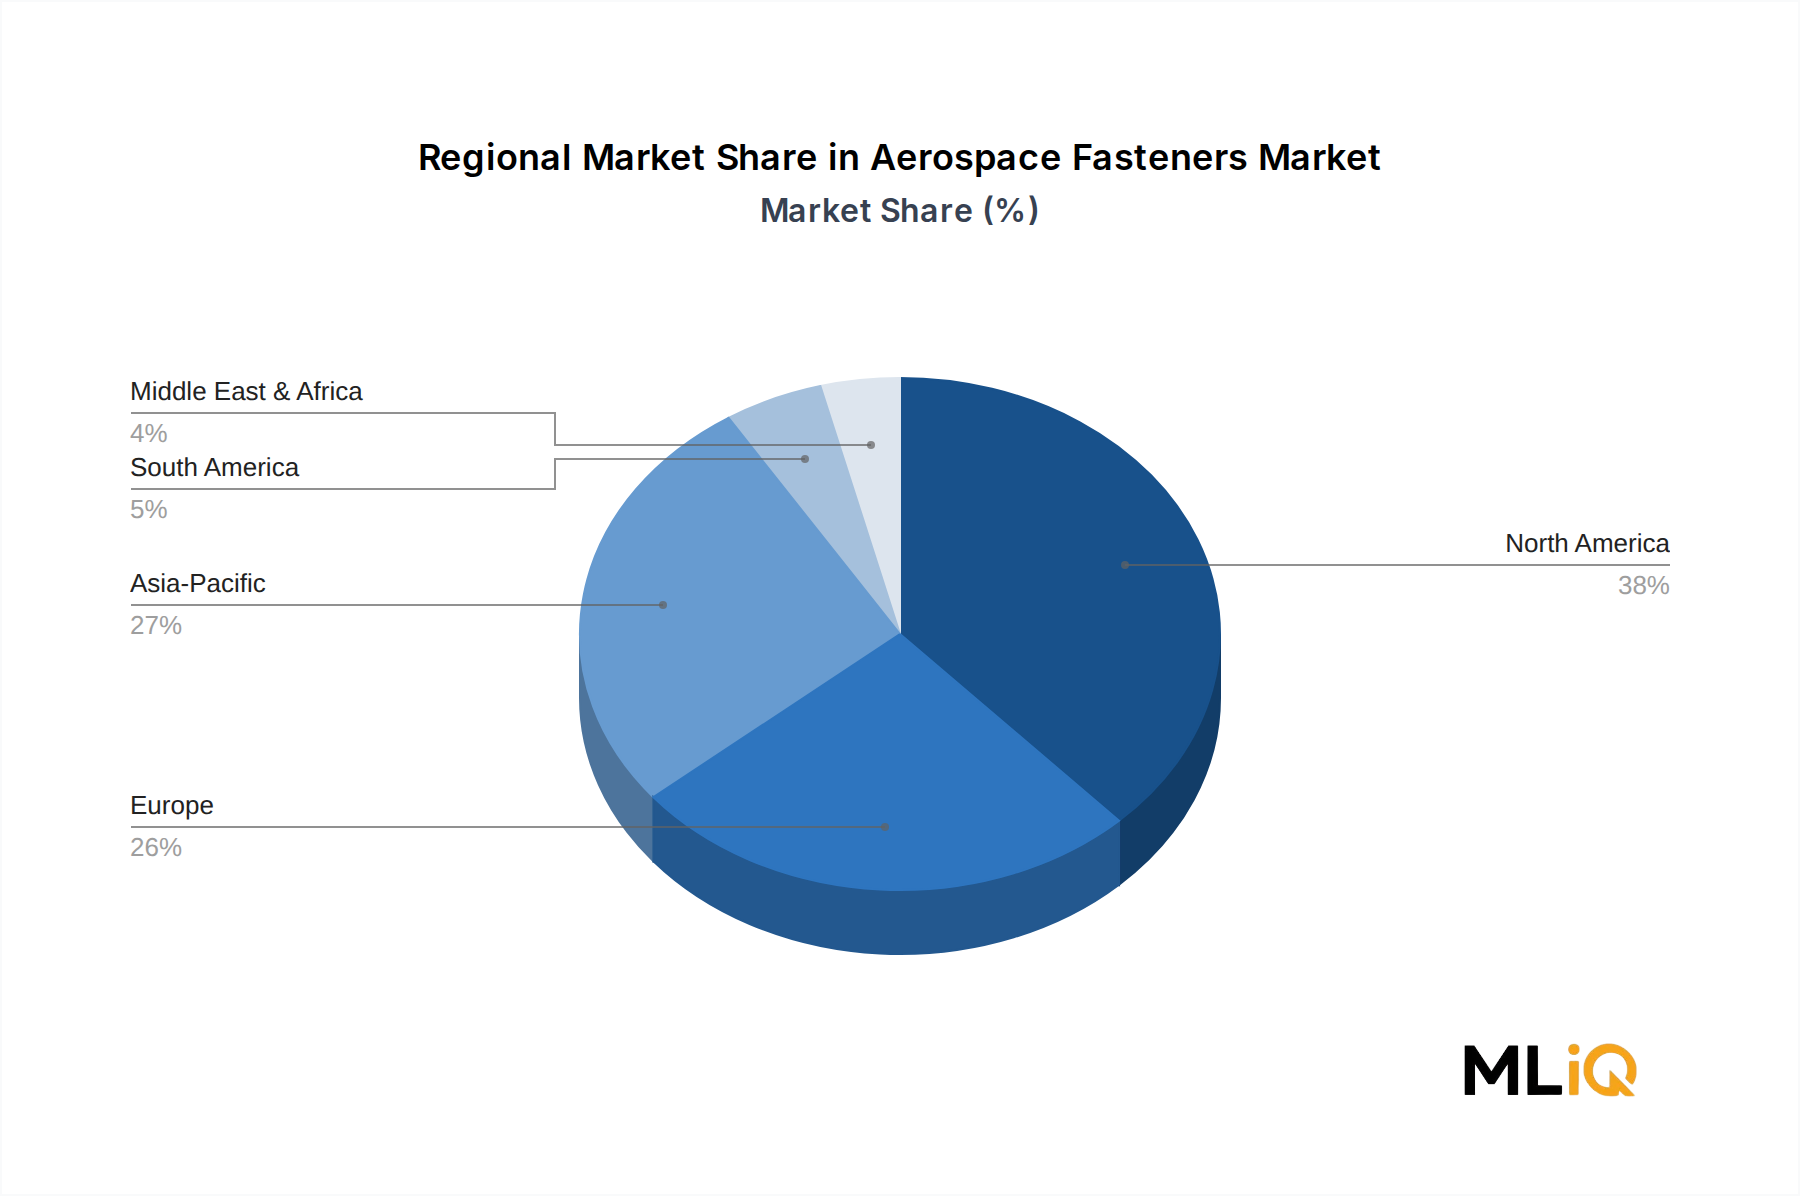
The global Aerospace Fasteners Market is valued at $7.8 billion in 2025 and is projected to reach $11.8 billion by 2034, expanding at a 4.7% CAGR. Commercial aircraft platforms account for the largest revenue pool, with narrowbody and widebody build rates directly governing fastener consumption. The Commercial Aircraft Fasteners Market alone represents approximately 58% of total application demand. North America holds 34% revenue share, supported by Boeing, Airbus US operations, and a dense tier-1 supplier base. Asia-Pacific is the fastest-growing region at a projected 5.8% CAGR, driven by COMAC, Airbus Tianjin, and MRO expansion. Material mix is shifting toward Titanium Aerospace Fasteners Market and superalloy variants as airframers target weight reduction and corrosion resistance. Aluminum Aerospace Fasteners Market remains volume-heavy for interior and secondary structures. The market remains qualification-gated, with AS9100, NADCAP, and OEM approvals creating durable incumbency. Distributors and MRO channels benefit from aftermarket demand, where Aerospace MRO Fasteners Market growth tracks flight-hour recovery and fleet aging. Margin pressure persists from raw material volatility, but long-term contracts and backlog visibility support pricing discipline. Strategic M&A and private equity interest remain active in specialized coating and titanium fastener assets.
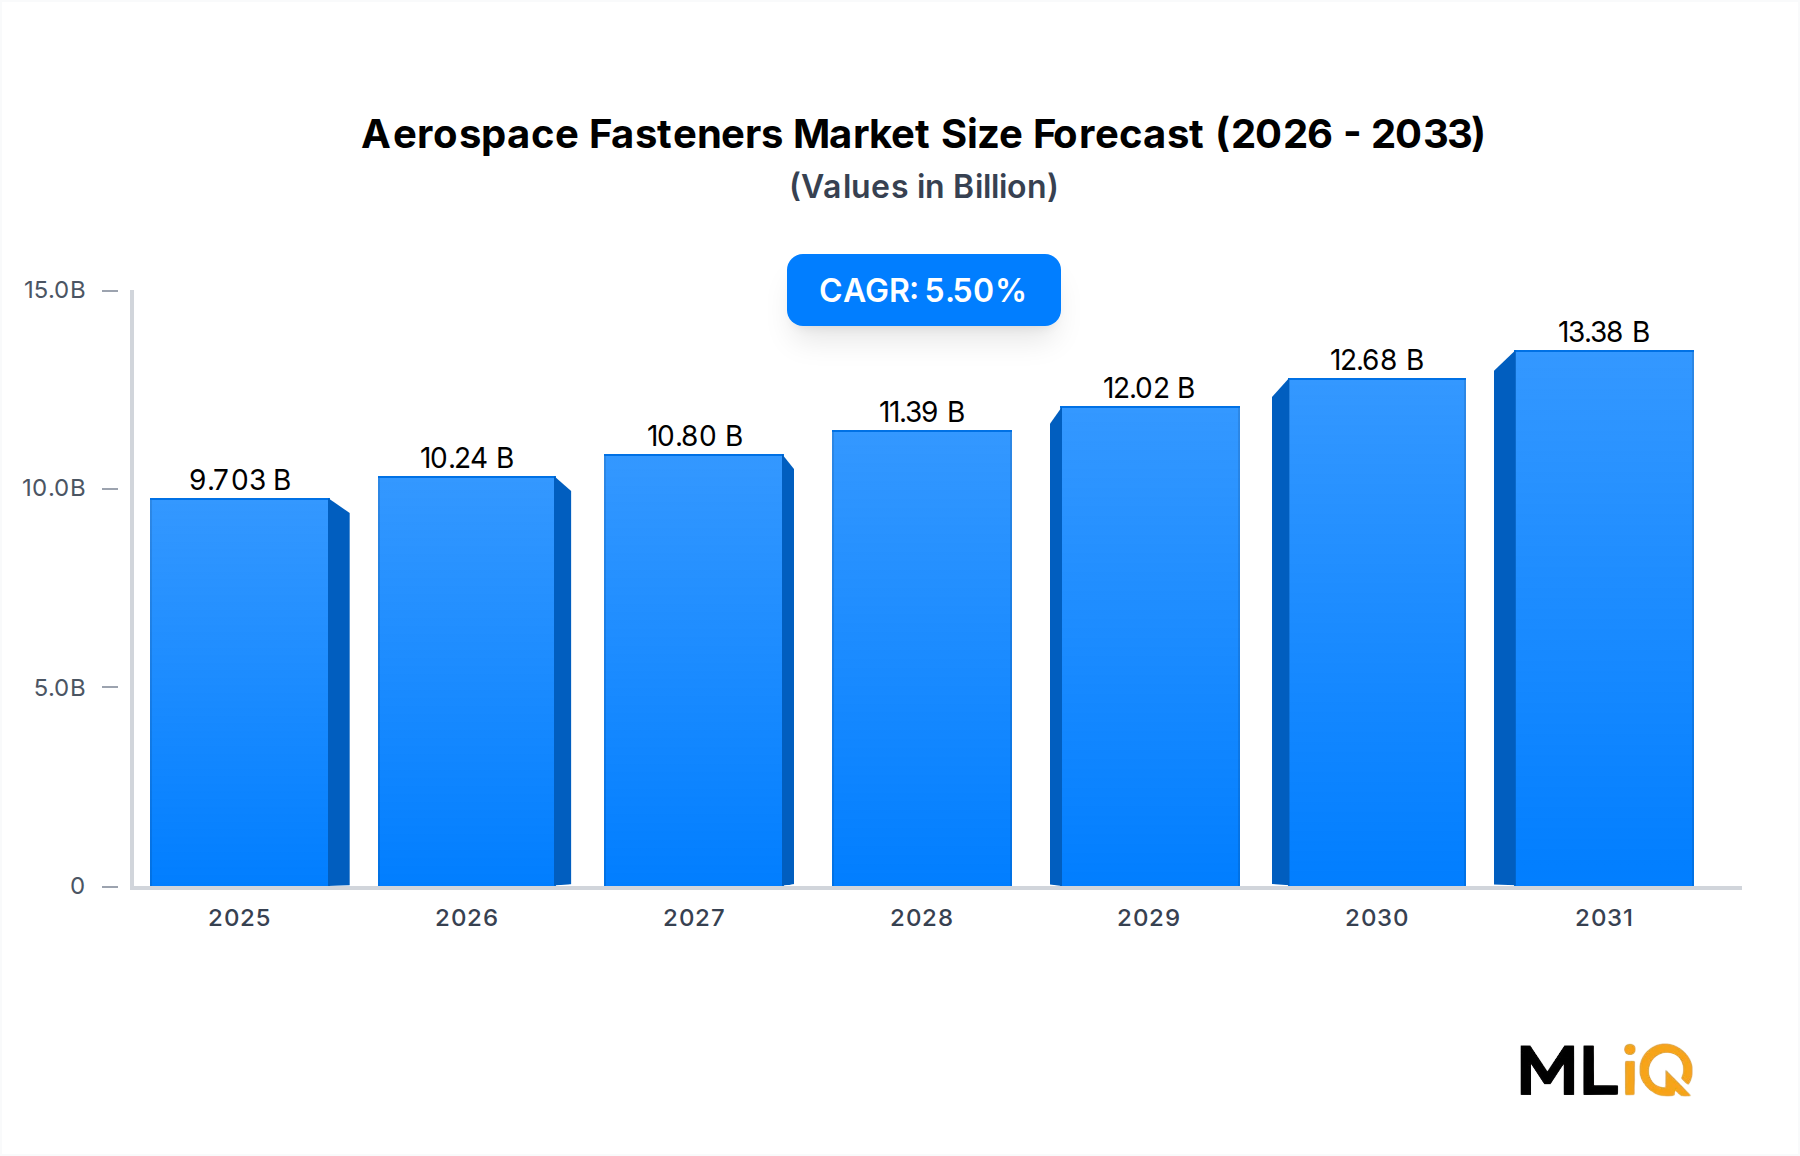
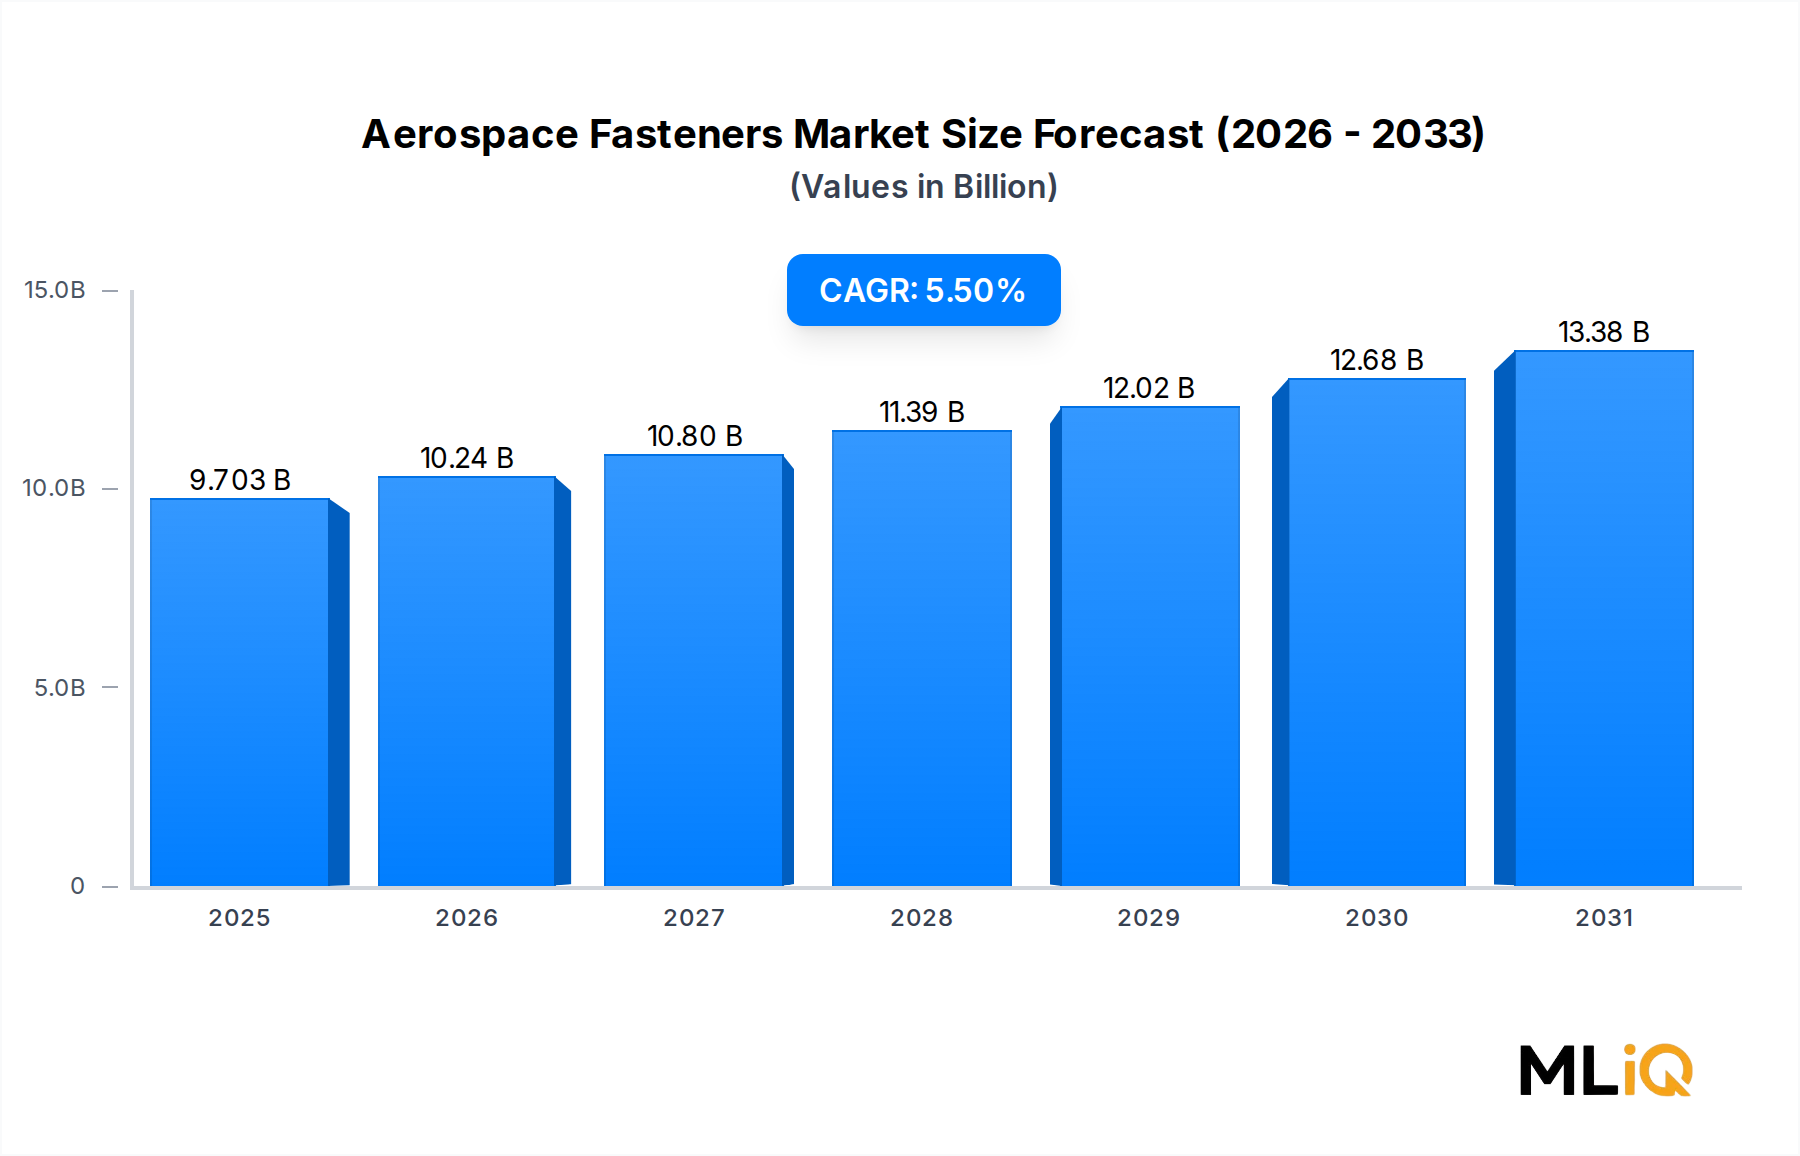
Aerospace Fasteners Market Size (In Billion)
15.0B
10.0B
5.0B
0
7.800 B
2025
8.167 B
2026
8.550 B
2027
8.952 B
2028
9.373 B
2029
9.814 B
2030
10.28 B
2031
Segment Deep-Dive: Commercial Aircraft Dominance in Aerospace Fasteners Market
Segment Analysis Matrix
Segment
Growth Rate (CAGR %)
Market Share (%)
Key Demand Driver
Commercial Aircraft
5.2%
58%
Narrowbody and widebody build rates
Military Aircraft
4.1%
25%
Defense modernization and fleet sustainment
General Aviation
3.4%
17%
Business jet and trainer aircraft production
Titanium Fasteners
6.3%
22%
Weight reduction and corrosion resistance
Aluminum Fasteners
3.9%
41%
Interior structures and secondary airframe
Superalloy Fasteners
5.8%
19%
Engine and high-temperature applications
Commercial Aircraft Fasteners Market
Commercial Aircraft Fasteners Market is the largest and fastest-growing application category, supported by Boeing 737 MAX, Airbus A320neo, and widebody recovery.
Fastener content per commercial airframe ranges from 1.5 to 3 million units, depending on model and material mix.
OEM build-rate increases of 10-15% through 2027 translate directly into fastener volume growth.
Margin pressure comes from multi-year fixed-price contracts and qualification costs, not demand weakness.
Material Sub-Segment Dynamics
Titanium Aerospace Fasteners Market is expanding at 6.3% CAGR, outpacing steel and aluminum due to composite airframe compatibility.
Aluminum Aerospace Fasteners Market retains the largest unit volume, especially in cabin interiors and non-structural brackets.
Aerospace Superalloy Fasteners Market serves engine and exhaust zones, where nickel-based alloys resist temperatures above 1,200°F.
Military Aircraft Fasteners Market demand is steady but program-specific, with F-35, Eurofighter, and Rafale sustainment supporting baseline volumes.
Margin Pressures
Raw material inflation for titanium bar and superalloy ingot has raised input costs by 12-18% since 2021.
Qualification cycles of 24-48 months limit supplier switching and protect incumbent margins.
Distributors face thinner margins than OEM-qualified manufacturers, typically 8-14% gross margin versus 22-30% for proprietary parts.
Coating and heat-treatment services add value but require NADCAP accreditation, a barrier that concentrates margin among fewer vendors.
Primary Market Drivers & Growth Restraints in Aerospace Fasteners Market
Titanium and superalloy adoption for composite airframes and engines
High
Long term
Driver
Defense modernization budgets in US, Europe, and Indo-Pacific
Medium
Medium term
Driver
MRO recovery and fleet aging, with average aircraft age 22 years in North America
Medium
Short term
Restraint
Titanium sponge and nickel alloy supply concentration
High
Short term
Restraint
NADCAP and AS9100 qualification bottlenecks
Medium
Long term
Restraint
OEM pricing pressure and fixed-price long-term agreements
Medium
Long term
Restraint
Skilled labor shortages in machining and coating
Medium
Short term
The primary catalysts are structural. Commercial aircraft backlogs at Boeing and Airbus exceed 14,000 aircraft, equivalent to more than 8 years of production at current rates. Each aircraft requires between 1.5 and 3 million fasteners, creating a durable replacement and OEM demand pool. The Aircraft Engine Fasteners Market is also expanding as engine OEMs increase spare parts output and MRO shops replace high-temperature fasteners during shop visits. Aerospace Superalloy Fasteners Market demand is tied to engine thrust and temperature requirements. Restraints are mostly supply-side. Titanium sponge sourcing remains concentrated in China, Russia, and Kazakhstan, exposing the Titanium Aerospace Fasteners Market to geopolitical disruption. Nickel-based superalloy availability improved after 2023, but qualification of new mills takes 18-36 months. OEMs continue to push annual price reductions of 2-4% on mature programs, squeezing tier-2 suppliers. Labor shortages in precision machining and NADCAP coating add cost and delay capacity expansion. Overall, demand visibility is strong, but margin expansion depends on material hedging, automation, and aftermarket mix.
LISI AEROSPACE (SAS): A top-three global aerospace fastener supplier with deep qualification across Airbus, Boeing, and engine programs. Its portfolio spans structural, engine, and specialty fasteners.
Arconic Corporation: Leverages aluminum and titanium mill capabilities to supply airframe fasteners and engineered products. Acquired by Apollo Global Management in a $5.2 billion transaction completed in 2023.
Precision Castparts Corp.: A Berkshire Hathaway subsidiary and a dominant superalloy fastener and casting supplier for engine and defense platforms. Its scale supports long-term OEM agreements.
TriMas Corporation: Operates aerospace fastener and precision component businesses serving commercial and defense customers. It competes on lead time and engineering support.
3V Fasteners (Stanley Black & Decker Inc.): Focuses on distribution and engineered fastener solutions for MRO and OEM aftermarket demand. Its parent provides supply chain scale.
Boeing Distribution Services Inc.: Provides OEM-backed distribution and kitting for Boeing programs and MRO customers. It benefits from captive demand and technical support.
B&B Specialties Inc.: Niche supplier of specialty fasteners and hardware for defense and space applications. Small volume, high-mix production supports premium pricing.
National Aerospace Fasteners Corporation: Manufactures precision aerospace fasteners for commercial and defense programs. It competes through qualification depth and machining capability.
TFI Aerospace Corporation: Offers fastener manufacturing and coating services. NADCAP approvals support its position in high-temperature and corrosion-resistant niches.
FSL Aerospace Ltd: Distributes and kits fasteners for MRO and OEM customers. Its value lies in inventory availability and traceability.
Bufab International AB: A C-parts and fastener distributor with growing aerospace exposure. It competes on logistics and vendor-managed inventory.
The Aerospace and Defense Fasteners Market remains moderately concentrated at the OEM-qualified tier, with LISI, Arconic, and Precision Castparts controlling a disproportionate share of proprietary part numbers. Niche suppliers survive through specialty alloys, coatings, or rapid-response MRO kitting.
Strategic Milestones & Recent Developments in Aerospace Fasteners Market
Latest Strategic Moves
Date
Company
Event Type
Impact
2023
Apollo Global Management / Arconic Corporation
M&A
$5.2 billion take-private; consolidated aluminum and titanium fastener assets
2024
Precision Castparts Corp.
Capacity expansion
Increased superalloy fastener output for engine OEMs
2024
LISI AEROSPACE (SAS)
Long-term agreement
Secured multi-year fastener supply for commercial programs
2025
Boeing Distribution Services Inc.
Distribution agreement
Expanded MRO kitting and aftermarket availability
2025
TriMas Corporation
Portfolio optimization
Divested non-core assets to focus on aerospace fasteners
2023: Apollo Global Management completed the acquisition of Arconic Corporation for $5.2 billion, folding a major aluminum and titanium supplier into a private capital portfolio. The deal concentrated ownership of airframe-grade fastener inputs.
2024: Precision Castparts Corp. expanded superalloy fastener capacity to support rising engine build rates and spare parts demand. The move targeted the Aerospace Superalloy Fasteners Market, where lead times had extended beyond 40 weeks.
2024: LISI AEROSPACE (SAS) signed multi-year agreements with commercial OEMs, locking in volume for structural and engine fasteners. The contracts improve backlog visibility through 2028.
2025: Boeing Distribution Services Inc. broadened its MRO distribution agreements to reduce fastener lead times for aftermarket customers. The initiative supports the Aerospace MRO Fasteners Market as flight hours recover.
2025: TriMas Corporation optimized its portfolio, divesting non-core units to concentrate on aerospace fastener manufacturing. The strategy aims to improve margins and qualification focus.
Regional Market Analysis & Growth Corridors for Aerospace Fasteners Market
Regional Growth Comparison
Region
Projected CAGR (%)
Base Year Valuation
Primary Catalyst
Regulatory Stringency
North America
4.2%
$2.65 billion
Boeing and defense programs
High (FAA)
Europe
4.0%
$2.03 billion
Airbus and Safran supply chain
High (EASA)
Asia-Pacific
5.8%
$2.11 billion
COMAC, Airbus Tianjin, MRO expansion
Medium-High
LAMEA
5.1%
$1.01 billion
Defense modernization and fleet growth
Medium
North America remains the most mature and largest regional market, with $2.65 billion in 2025 revenue and a 4.2% CAGR. The region benefits from Boeing commercial programs, defense primes, and a dense MRO network. FAA oversight and AS9100/NADCAP requirements create high barriers but also protect qualified suppliers. Europe follows at $2.03 billion, supported by Airbus, Safran, and Rolls-Royce supply chains. EASA Part-21 and EASA Part-145 requirements mirror FAA stringency, sustaining premium pricing for certified vendors. Asia-Pacific is the fastest-growing corridor at 5.8% CAGR, reaching $2.11 billion in 2025. COMAC C919 ramp-up, Airbus Tianjin final assembly, and expanding MRO capacity in China, India, and Japan drive demand. The Aerospace MRO Fasteners Market is particularly dynamic in Asia-Pacific as fleets age and local repair stations gain NADCAP approvals. LAMEA represents $1.01 billion and grows at 5.1%, led by Turkey, Israel, and GCC defense programs. Regulatory stringency is lower in parts of LAMEA, but OEM qualification requirements still govern access. The most mature markets compete on aftermarket share and cost efficiency, while emerging corridors compete on capacity, localization, and government offsets.
Investment, M&A & Funding Activity in Aerospace Fasteners Market
M&A and private equity activity have concentrated around three themes: vertical integration into titanium and superalloy inputs, consolidation of NADCAP-certified coating assets, and aftermarket distribution roll-ups. The $5.2 billion take-private of Arconic Corporation by Apollo Global Management in 2023 remains the largest transaction, signaling private capital interest in aerospace-grade aluminum and titanium supply. Strategic acquirers such as Precision Castparts Corp. and LISI AEROSPACE (SAS) have pursued bolt-on capacity in superalloy and engine fastener niches. The Aerospace Fastener Coatings Market attracts capital because coating capacity is qualification-gated and generates recurring MRO demand. Venture capital interest is limited in commodity fasteners but present in digital inventory platforms, additive manufacturing for low-volume brackets, and inspection automation. The Aircraft Engine Fasteners Market draws strategic investment due to engine OEM aftermarket economics and 15-20% spare parts margins. Distribution assets, including Bufab International AB and Boeing Distribution Services Inc., remain attractive for their inventory breadth and customer stickiness. Overall, capital is flowing toward qualification moats, material security, and aftermarket channels rather than greenfield commodity capacity.
Average selling prices (ASP) for aerospace fasteners vary by material and qualification. Standard aluminum rivets and bolts sell for $0.10-$2.00 per unit, while titanium and superalloy engine fasteners range from $8 to $120 per unit. Raw materials represent 45-60% of production cost for titanium and superalloy parts, compared with 30-40% for aluminum and steel. Labor accounts for 15-25%, energy 5-8%, and logistics and quality compliance 10-15%. Margin structures differ across the value chain: OEM-qualified manufacturers earn 22-30% gross margins on proprietary parts, while distributors earn 8-14%. Pricing power is strongest for sole-source, NADCAP-certified engine fasteners and weakest for standard hardware with multiple qualified suppliers. Inflationary pressure from titanium sponge and nickel has been partially offset by long-term contracts and annual productivity clauses of 2-4%. The Aluminum Aerospace Fasteners Market faces more price competition because multiple suppliers can produce standard parts. The Titanium Aerospace Fasteners Market commands premiums due to material cost, machining difficulty, and composite airframe compatibility. The Aerospace and Defense Fasteners Market overall is transitioning toward value-based pricing, where traceability, lead time, and qualification documentation justify premiums. Margin expansion depends on automation, scrap reduction, and aftermarket mix, not volume alone.
Aerospace Fasteners Market Segmentation
1. Application
1.1. Commercial Aircraft
1.2. Military Aircraft
1.3. General Aviation
2. Material
2.1. Aluminum
2.2. Steel
2.3. Superalloys
2.4. Titanium
Aerospace Fasteners Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Aerospace Fasteners Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 4.7% from 2020-2034
Segmentation
By Application
Commercial Aircraft
Military Aircraft
General Aviation
By Material
Aluminum
Steel
Superalloys
Titanium
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Application
5.1.1. Commercial Aircraft
5.1.2. Military Aircraft
5.1.3. General Aviation
5.2. Market Analysis, Insights and Forecast - by Material
5.2.1. Aluminum
5.2.2. Steel
5.2.3. Superalloys
5.2.4. Titanium
5.3. Market Analysis, Insights and Forecast - by Region
5.3.1. North America
5.3.2. South America
5.3.3. Europe
5.3.4. Middle East & Africa
5.3.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Application
6.1.1. Commercial Aircraft
6.1.2. Military Aircraft
6.1.3. General Aviation
6.2. Market Analysis, Insights and Forecast - by Material
6.2.1. Aluminum
6.2.2. Steel
6.2.3. Superalloys
6.2.4. Titanium
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Application
7.1.1. Commercial Aircraft
7.1.2. Military Aircraft
7.1.3. General Aviation
7.2. Market Analysis, Insights and Forecast - by Material
7.2.1. Aluminum
7.2.2. Steel
7.2.3. Superalloys
7.2.4. Titanium
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Application
8.1.1. Commercial Aircraft
8.1.2. Military Aircraft
8.1.3. General Aviation
8.2. Market Analysis, Insights and Forecast - by Material
8.2.1. Aluminum
8.2.2. Steel
8.2.3. Superalloys
8.2.4. Titanium
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Application
9.1.1. Commercial Aircraft
9.1.2. Military Aircraft
9.1.3. General Aviation
9.2. Market Analysis, Insights and Forecast - by Material
9.2.1. Aluminum
9.2.2. Steel
9.2.3. Superalloys
9.2.4. Titanium
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Application
10.1.1. Commercial Aircraft
10.1.2. Military Aircraft
10.1.3. General Aviation
10.2. Market Analysis, Insights and Forecast - by Material
10.2.1. Aluminum
10.2.2. Steel
10.2.3. Superalloys
10.2.4. Titanium
11. Competitive Analysis
11.1. Company Profiles
11.1.1. 3V Fasteners (Stanley Black & Decker Inc )
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Arconic Corporation
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. B&B Specialties Inc
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. LISI AEROSPACE (SAS)
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Boeing Distribution Services Inc (The Boeing Company)
Table 46: Rest of Asia Pacific Aerospace Fasteners Market Revenue (billion) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
Primary research accounts for 70–80% of total effort, with secondary research contributing 20–30%. This split prioritizes direct validation of qualification cycles, material sourcing, and price expectations.
We interview aerospace fastener OEMs, tier-1 airframe structure suppliers, titanium and superalloy mills qualified to AMS 4928 and AMS 5662, NADCAP-accredited heat treatment and coating service providers, and AS9120-certified aerospace fastener distributors. These five company types span the full value chain from raw material to aftermarket.
Stakeholder interviews target Aerospace Fastener Commodity Managers, Supplier Quality Engineers (AS9100/NADCAP), Airframe Structural Engineering Leads, and MRO Procurement Directors. Their input validates demand signals, lead times, and qualification barriers.
Interview quotas ensure coverage by application, material, and region. We guarantee an estimated data accuracy level of 85–90% across reported market sizes and forecasts.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Aerospace Fastener Commodity Manager
28%
Supplier Quality Engineer
22%
Airframe Structural Engineering Lead
18%
MRO Procurement Director
16%
Manufacturing and Operations Director
10%
Regulatory Compliance Specialist
6%
Industry Ecosystem Breakdown
Company Type
Representation (%)
Aerospace fastener OEMs
30%
Tier-1 airframe structure suppliers
20%
Titanium and superalloy mills
18%
NADCAP coating and heat treatment providers
14%
AS9120 distributors and MRO providers
18%
Secondary Research & Industry Benchmarking
Secondary research draws on Bloomberg, Factiva, Hoovers, and PitchBook for financial filings, M&A activity, and private capital flows. We do not cite market research websites.
Additional sources include .gov databases from the FAA and EASA, .org publications from SAE International and AIA, and trade association data from the Aerospace Industries Association and the National Aerospace Fasteners Association.
We benchmark commercial aircraft build rates, defense procurement budgets, titanium mill product shipments, and MRO flight-hour recovery against company disclosures and regulatory dockets.
Every report is updated to the date of purchase, incorporating the latest earnings calls, order backlogs, and trade notices.
Demand Modeling & Market Estimation
We apply top-down and bottom-up methodologies simultaneously. Top-down sizing uses global aerospace and defense spending, commercial aircraft deliveries, and material intensity per airframe.
Bottom-up modeling uses specific quantitative metrics: annual commercial aircraft deliveries, fastener content per airframe (units/aircraft), titanium mill product shipments to aerospace (metric tons), and MRO spend per flight hour.
We build separate demand curves for Commercial Aircraft, Military Aircraft, and General Aviation, and for Aluminum, Steel, Superalloys, and Titanium.
Regional models incorporate US, Canada, Mexico, Brazil, Argentina, UK, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Turkey, Israel, GCC, North Africa, South Africa, China, India, Japan, South Korea, ASEAN, Oceania, and Rest of Asia Pacific.
Multi-level data triangulation reconciles primary interview ranges, company-level revenue, trade statistics, and bottom-up unit consumption. Divergences above 5% trigger follow-up interviews.
Data Accuracy & Quality Check
We maintain a guaranteed estimated data accuracy level of 85–90% for market size, segmentation, and growth rates. All estimates are cross-validated through multi-level data triangulation.
Quality checks include sanity testing against aircraft delivery schedules, material consumption ratios, and supplier capacity disclosures.
Forecasts are stress-tested for titanium supply disruption, OEM build-rate changes of ±10%, and regulatory shifts in FAA/EASA certification.
Final datasets are reviewed by senior analysts with aerospace manufacturing and supply chain experience. Every report is updated to the date of purchase.
No market research websites are used as sources. All references are to financial databases, .gov portals, .org associations, and trade bodies.
Frequently Asked Questions
1. Which end-user industries drive demand for aerospace fasteners?
Commercial aircraft, military aircraft, general aviation, and MRO providers are the primary end-user industries. Commercial aircraft accounts for about 58% of 2025 application demand, while military aircraft contributes 25% and general aviation 17%. MRO demand is tied to flight hours, with North American fleet age averaging 22 years.
2. What technological innovations are shaping aerospace fastener R&D?
R&D focuses on titanium alloys, nickel-based superalloys, and additive manufacturing for complex brackets. Titanium fasteners can reduce weight by up to 40% versus steel equivalents, supporting composite airframe programs. Smart fasteners with embedded strain sensing remain niche but attract development funding.
3. How are raw material sourcing and supply chain risks managed in the aerospace fasteners market?
Titanium sponge, nickel, and superalloy ingot sourcing is concentrated in China, Russia, and Kazakhstan, creating geopolitical exposure. Manufacturers qualify multiple mills, hold strategic inventory, and use long-term contracts to stabilize supply. Qualification of a new mill typically takes 18-36 months.
4. What export-import dynamics affect the aerospace fasteners market?
Cross-border trade represents over 35% of aerospace fastener value, with the US, Germany, France, and Japan as major exporters. ITAR and dual-use controls restrict some high-performance fasteners, while tariffs and local-content rules shape sourcing. Boeing and Airbus supplier networks drive intra-firm trade across North America and Europe.
5. Why are barriers to entry high for new aerospace fastener suppliers?
OEM qualification cycles run 24-48 months and require AS9100, NADCAP, and program-specific approvals. Capital intensity for machining, heat treatment, and testing adds further barriers. Incumbents such as LISI AEROSPACE and Precision Castparts benefit from proprietary part numbers and traceability records.
6. Who is investing in aerospace fastener innovation and M&A?
Private equity and strategic acquirers are active, exemplified by Apollo Global Management's $5.2 billion take-private of Arconic Corporation in 2023. Precision Castparts and LISI AEROSPACE pursue bolt-on capacity in superalloy and engine fasteners. Venture capital interest is concentrated in digital inventory, inspection automation, and additive manufacturing.