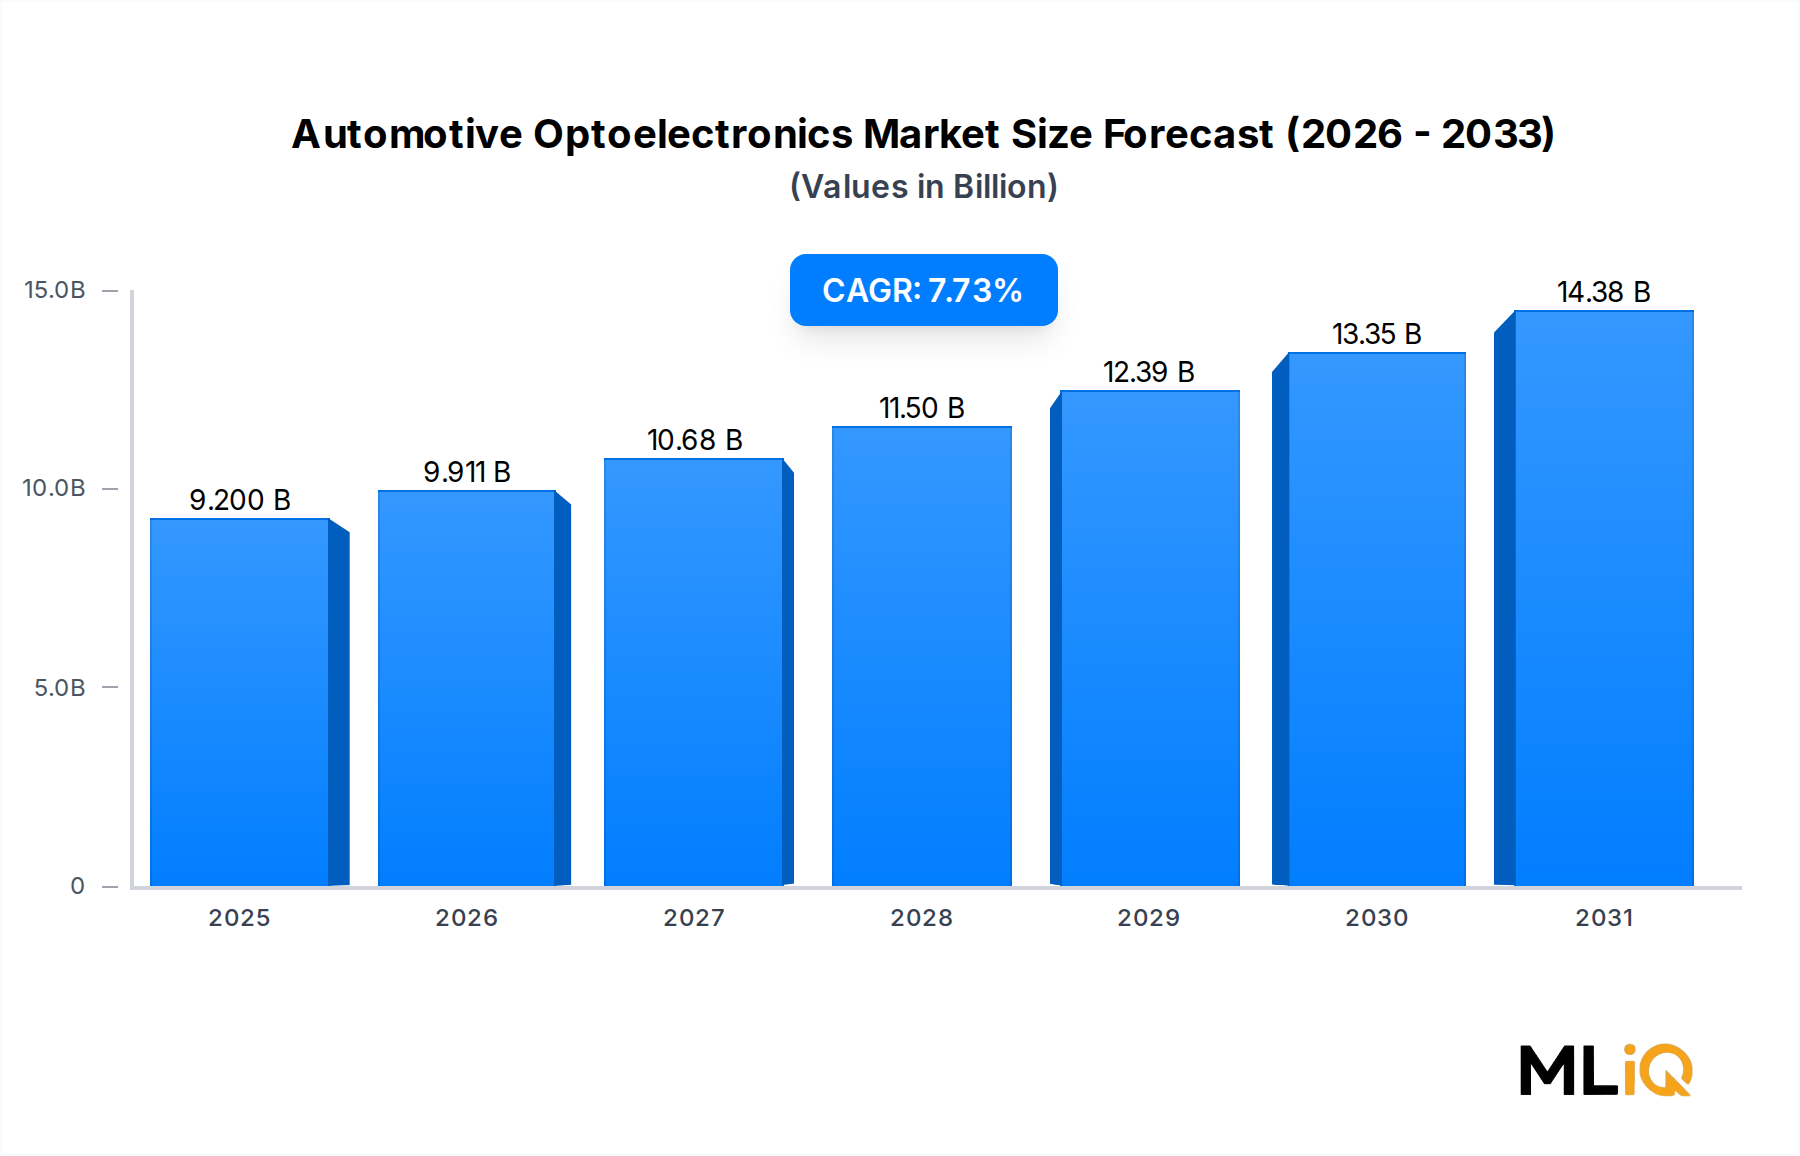
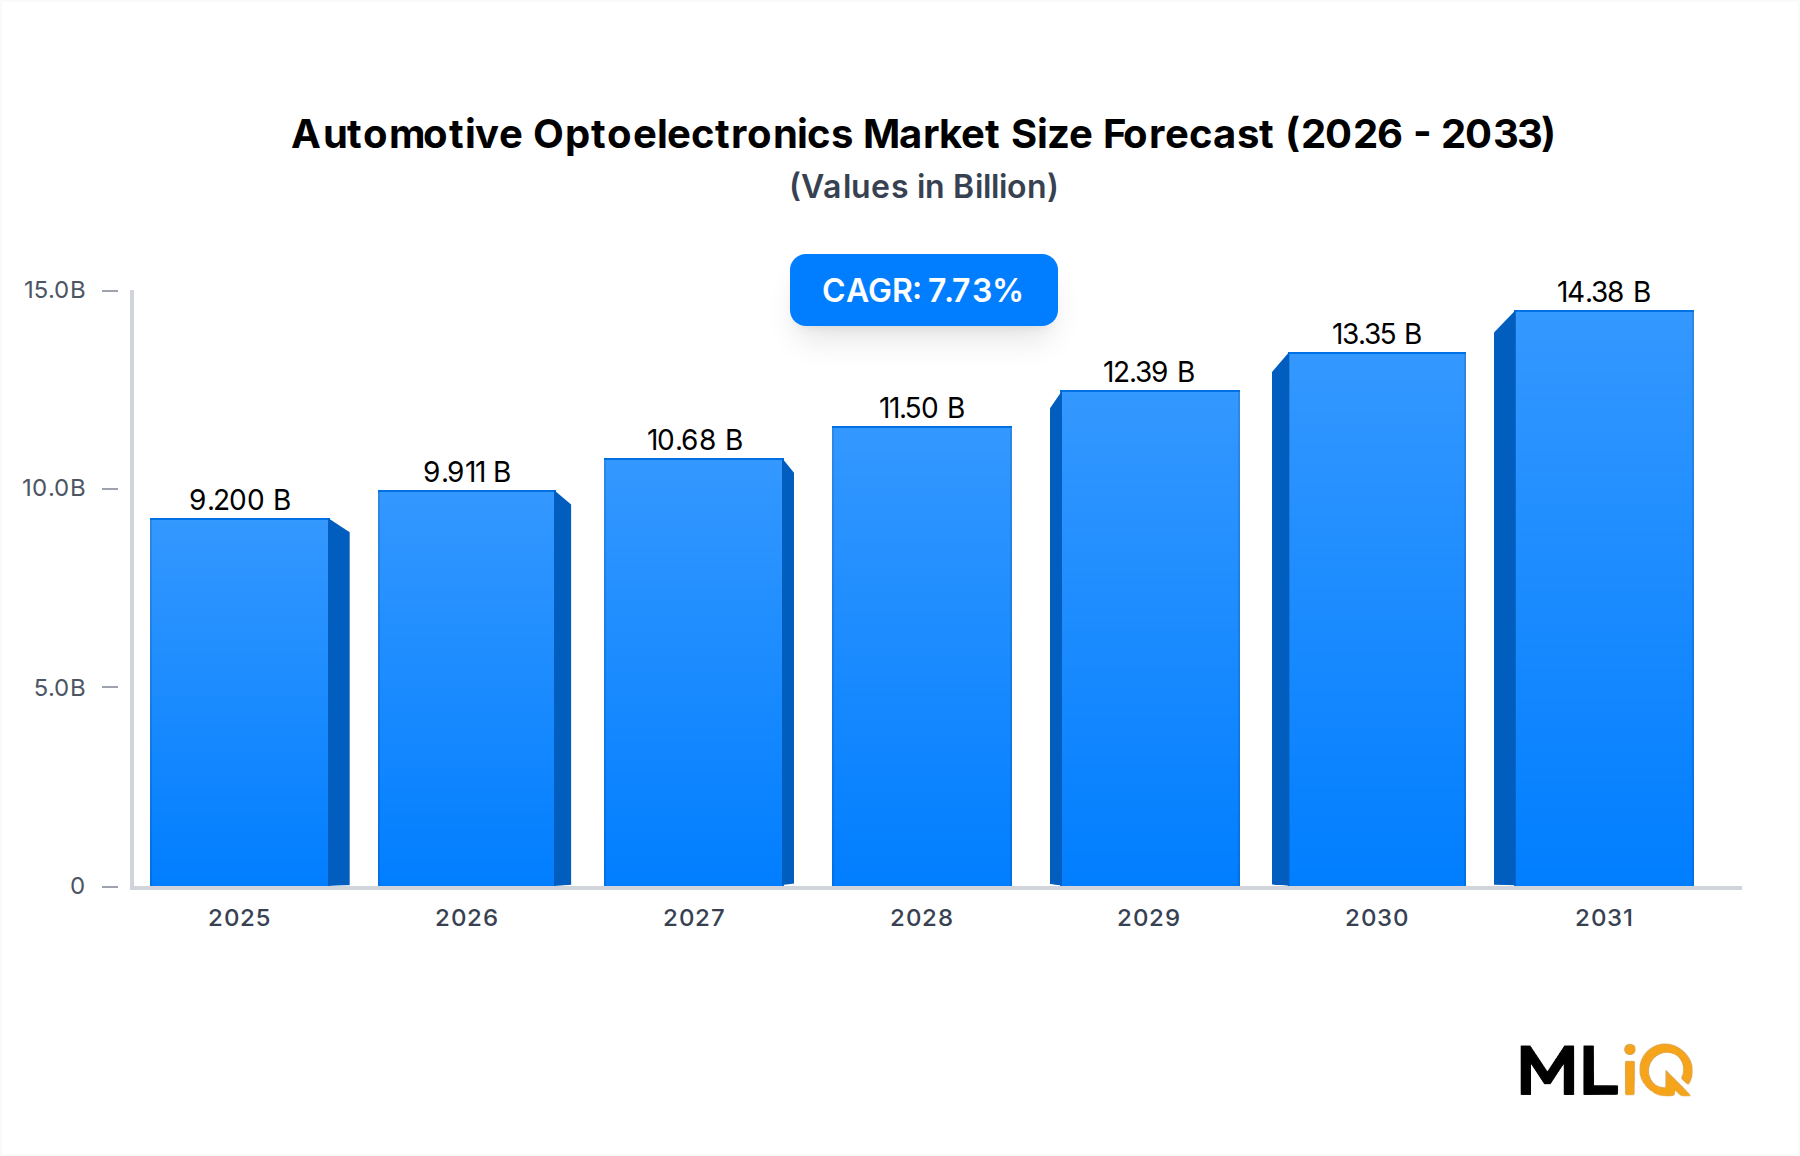
The global Automotive Optoelectronics Market is valued at $9.2 billion in 2025 and is projected to expand at a compound annual growth rate of 7.73% through 2033, driven by accelerating vehicle electrification, increasingly stringent safety mandates, and the widespread integration of advanced sensing technologies across modern vehicle architectures. Optoelectronics — encompassing components that source, detect, and control light — have become indispensable to the modern automotive ecosystem, serving functions from adaptive lighting and driver monitoring to LiDAR-based collision avoidance and cabin environment control.
The transition toward software-defined vehicles has fundamentally altered the demand curve for light-emitting, light-detecting, and light-modulating components. Original equipment manufacturers (OEMs) worldwide are embedding a higher density of optoelectronic components per vehicle, ranging from infrared proximity detectors and high-resolution image sensors to optically isolated power management circuits. This densification of electronic content per vehicle unit is one of the market's most significant structural tailwinds.
From a macro perspective, global new vehicle production is expected to sustain moderate growth through 2033, with electrified platforms — battery electric vehicles (BEVs) and plug-in hybrids — capturing an increasing portion of total production volume. Electric drivetrains require more sophisticated power electronics isolation, a function served in large part by optocouplers and photovoltaic isolation devices, directly amplifying volume demand within the optoelectronics supply chain.
Regulatory pressure is another critical growth catalyst. Safety regulations in the European Union, the United States, China, and Japan are mandating automatic emergency braking, lane-keeping assistance, and pedestrian detection systems — all of which are underpinned by imaging and optical sensing hardware. These legislative requirements create non-discretionary procurement pipelines for Tier 1 suppliers and component manufacturers alike.
On the technology frontier, LiDAR adoption in both autonomous and semi-autonomous vehicles is driving renewed investment in laser diode arrays and photodetector modules. While consumer robotaxi deployments have faced commercial headwinds, the integration of lower-cost solid-state LiDAR into production vehicles from 2026 onward is expected to create a sustained volume uplift for photonic components.
The competitive landscape is moderately consolidated, with major semiconductor and optics firms holding significant IP portfolios. However, Asian manufacturers — particularly from China, Japan, and South Korea — are rapidly ascending the value chain, intensifying price competition in commodity segments while simultaneously investing in premium sensing applications.
Looking ahead, the convergence of vehicle automation, electrification, and connectivity will ensure that the Automotive Optoelectronics Market remains one of the fastest-growing sub-segments of the broader automotive electronics supply chain through the forecast horizon.