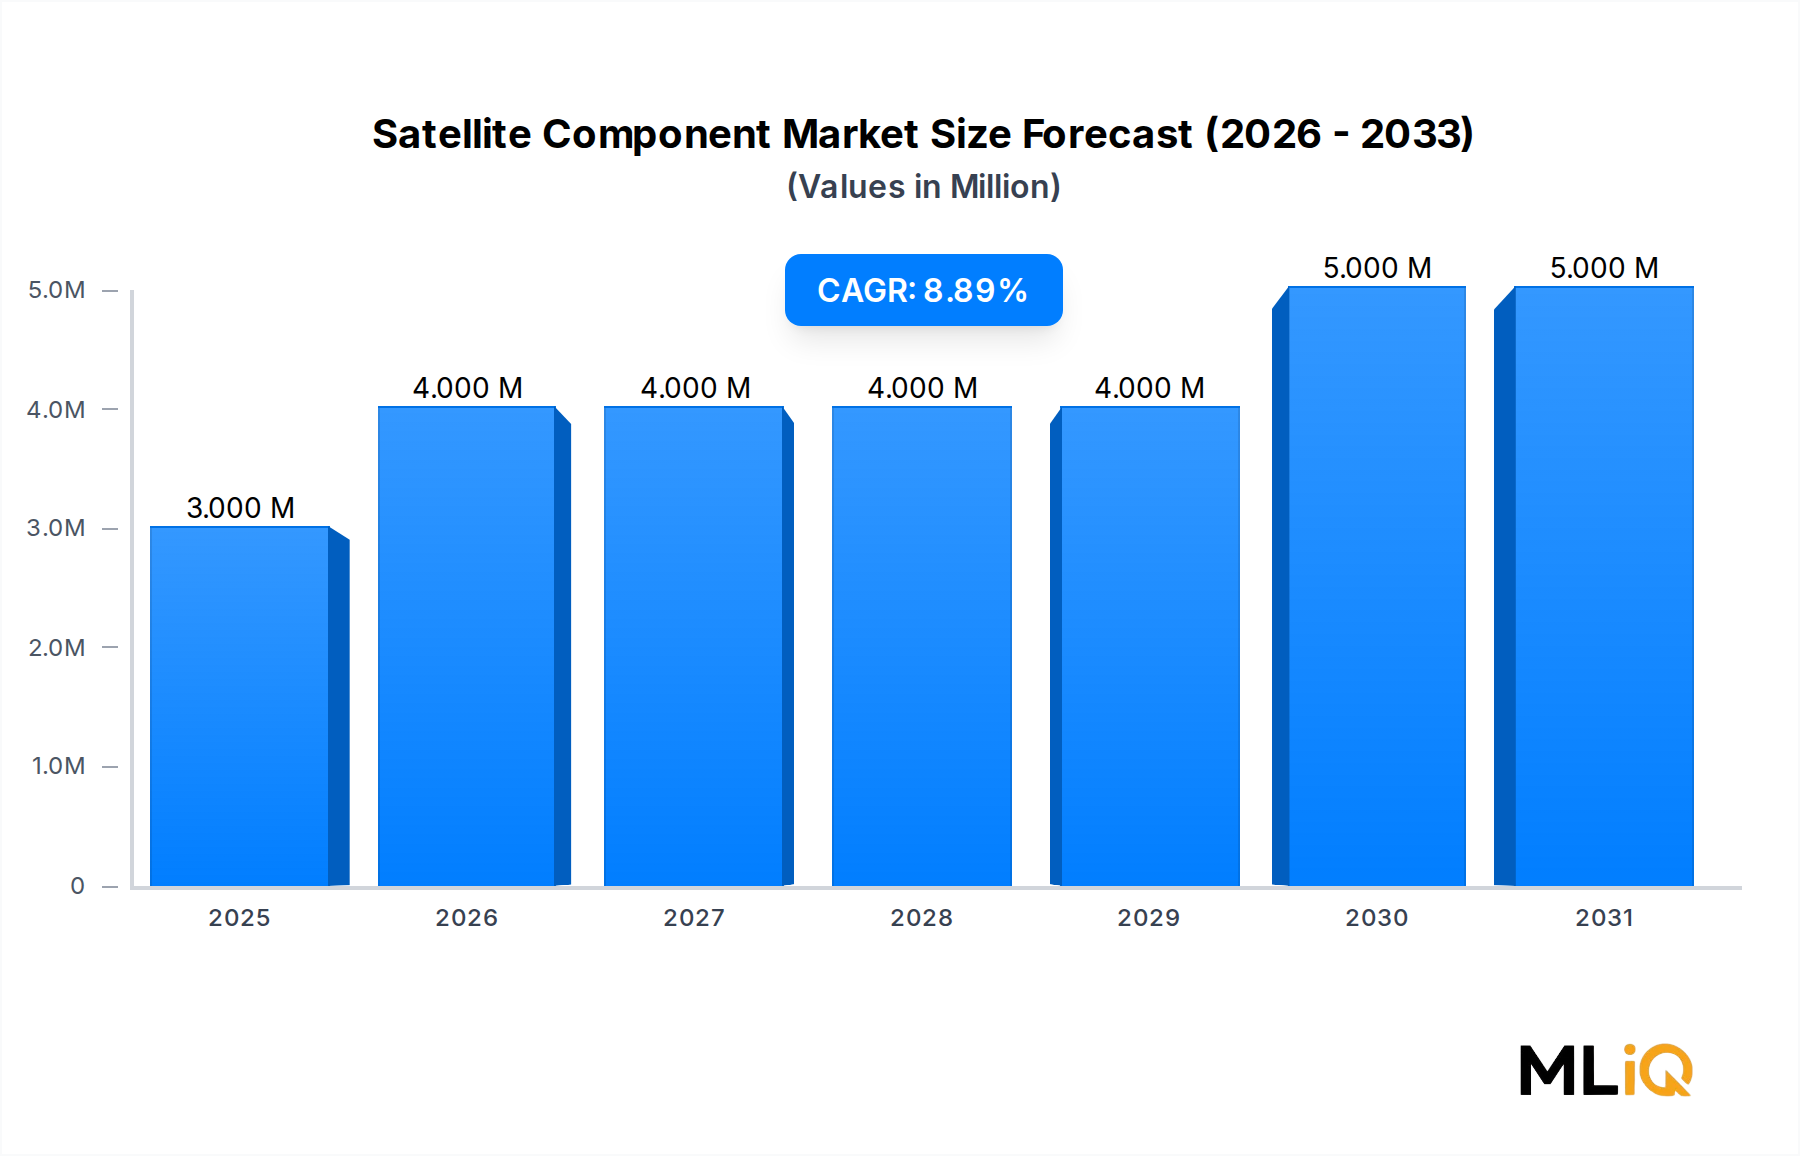
The global Satellite Component Market is valued at $3.37 billion as of the base assessment period and is projected to expand at a compound annual growth rate (CAGR) of 6.7% through 2033, reflecting sustained momentum across both commercial and government-led space programs. This growth trajectory is underpinned by accelerating satellite constellation deployments, expanding demand for broadband connectivity in underserved geographies, and a marked escalation in defense-oriented satellite procurement worldwide.
The proliferation of low Earth orbit (LEO) mega-constellations by both private operators and sovereign space agencies is compelling original equipment manufacturers and Tier-1 suppliers to scale production volumes substantially. Unlike legacy geostationary satellite programs that required a limited number of high-value units annually, LEO constellations demand hundreds to thousands of individual satellites, each integrating antennas, power systems, propulsion assemblies, transponders, and structural components — all of which are manufactured in high-mix, high-volume environments that challenge traditional aerospace supply chains.
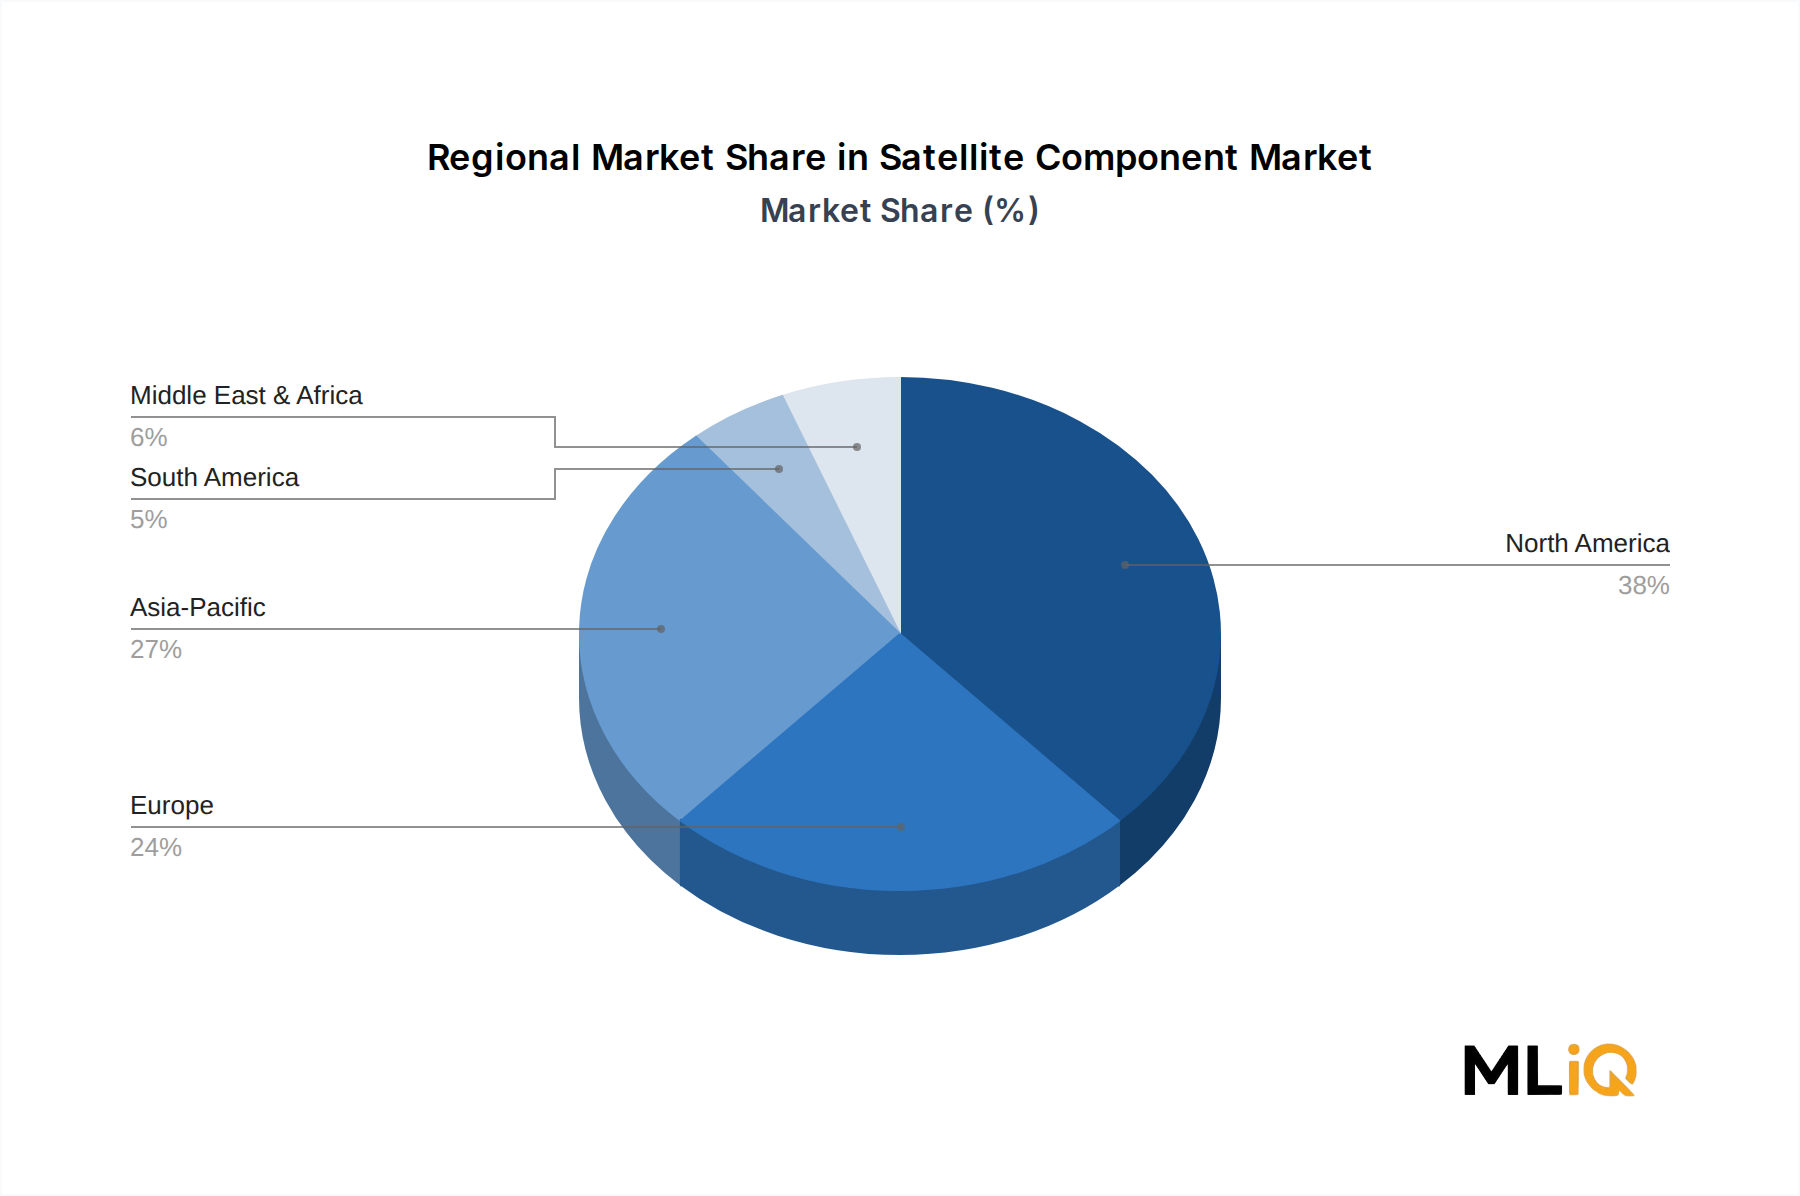
Macro tailwinds amplifying this demand include the global rollout of 5G backhaul infrastructure dependent on satellite relays, the integration of Internet of Things (IoT) sensor networks with satellite connectivity layers, and the modernization of military communication architectures. Governments in North America, Europe, and Asia Pacific are committing multi-year capital expenditures to next-generation satellite programs, creating a stable demand baseline that offsets cyclicality in commercial orders.
From a valuation perspective, the market is expected to approach approximately $5.9 billion by 2033, representing a substantial absolute gain driven by volume expansion rather than per-unit price inflation. Competitive intensity among component suppliers is increasing, with new entrants from the semiconductor and consumer electronics sectors introducing miniaturized, cost-efficient alternatives to traditionally bespoke aerospace hardware.
Key demand drivers identified in this analysis include the rise of autonomous systems requiring real-time satellite data links, growing investment in military and defense satellite communication infrastructure, and the convergence of commercial and government procurement in dual-use satellite platforms. Conversely, cybersecurity threats and signal interference challenges represent structural restraints that are prompting investment in hardened, encrypted component architectures.
The forward-looking outlook for the market through 2033 remains constructive. Supply chain localization efforts, particularly in North America and Europe following geopolitical disruptions, are incentivizing domestic component manufacturing, which may alter traditional trade flows but will also reduce lead times and single-source dependencies. New entrant technologies, including electric propulsion micro-thrusters and phased-array antenna systems, are expected to command premium pricing and reshape the competitive hierarchy within this market.