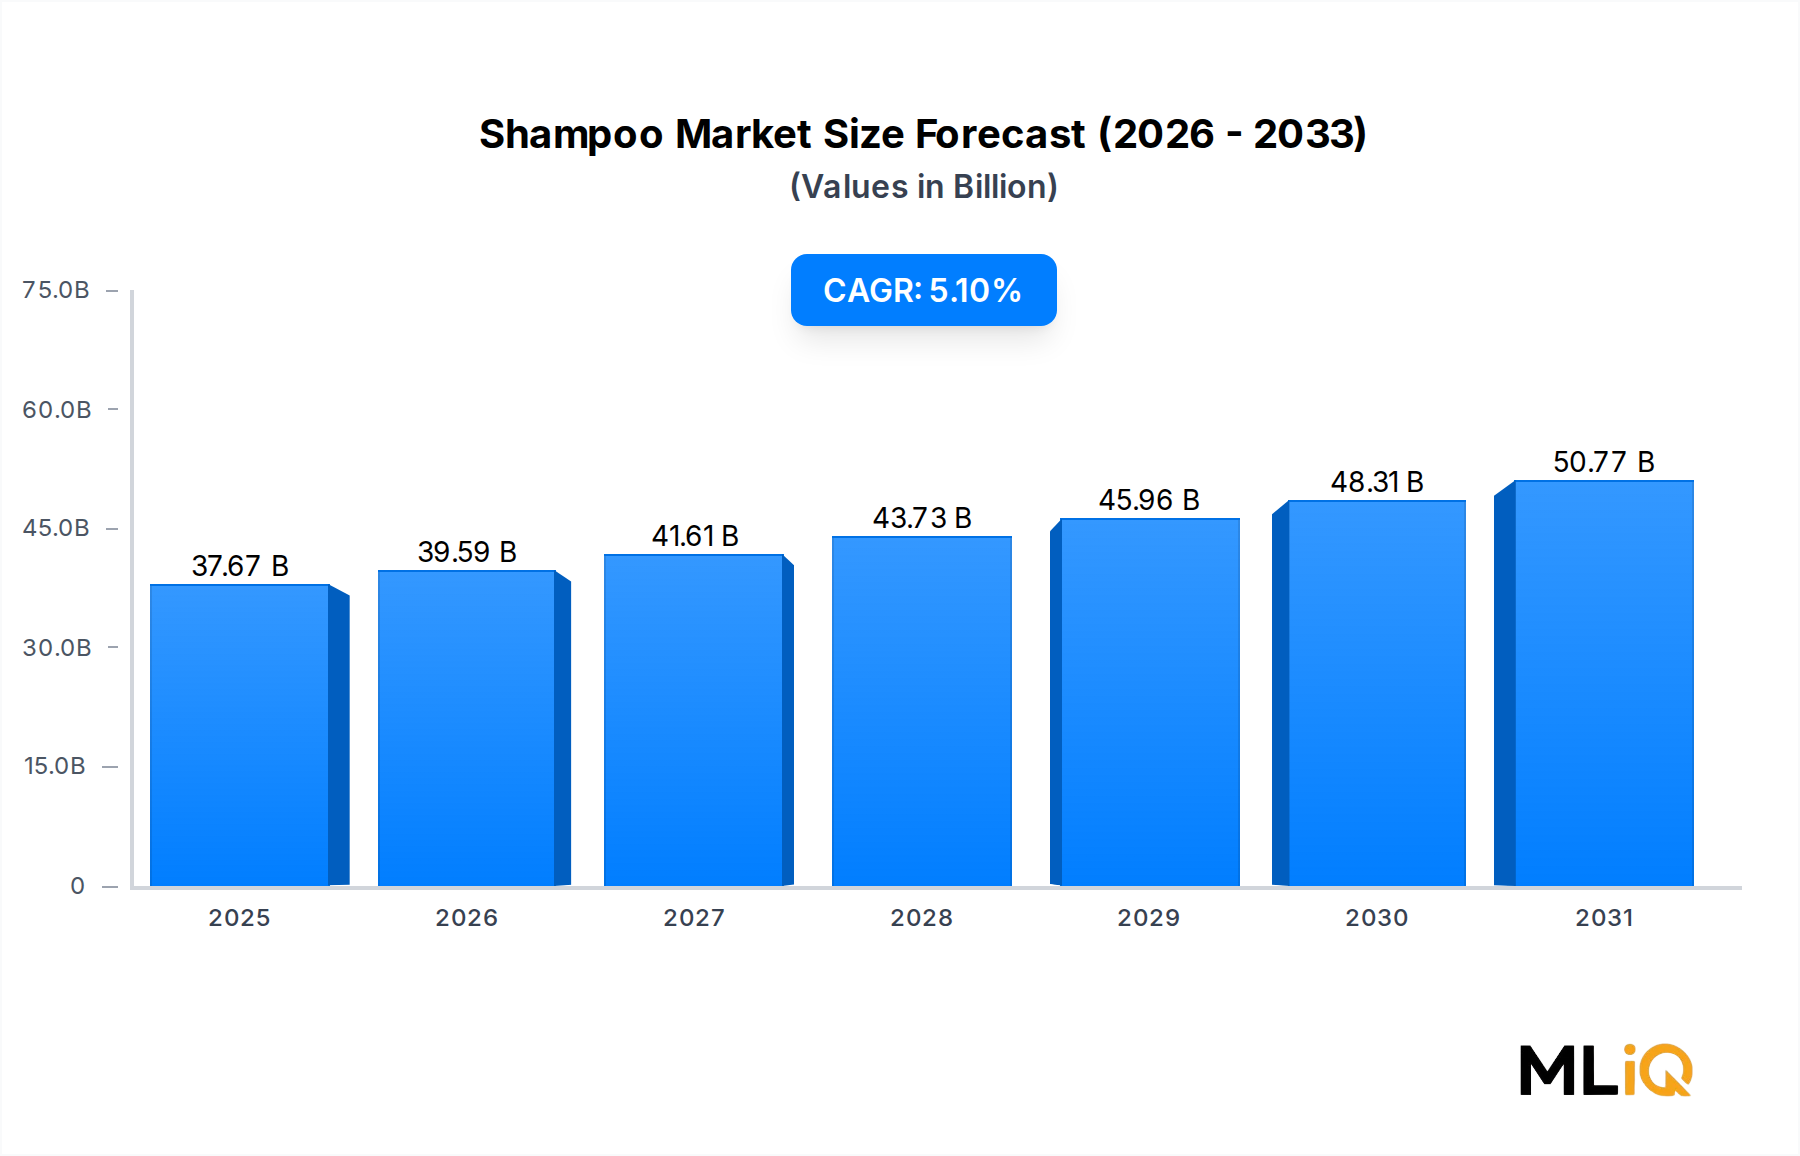
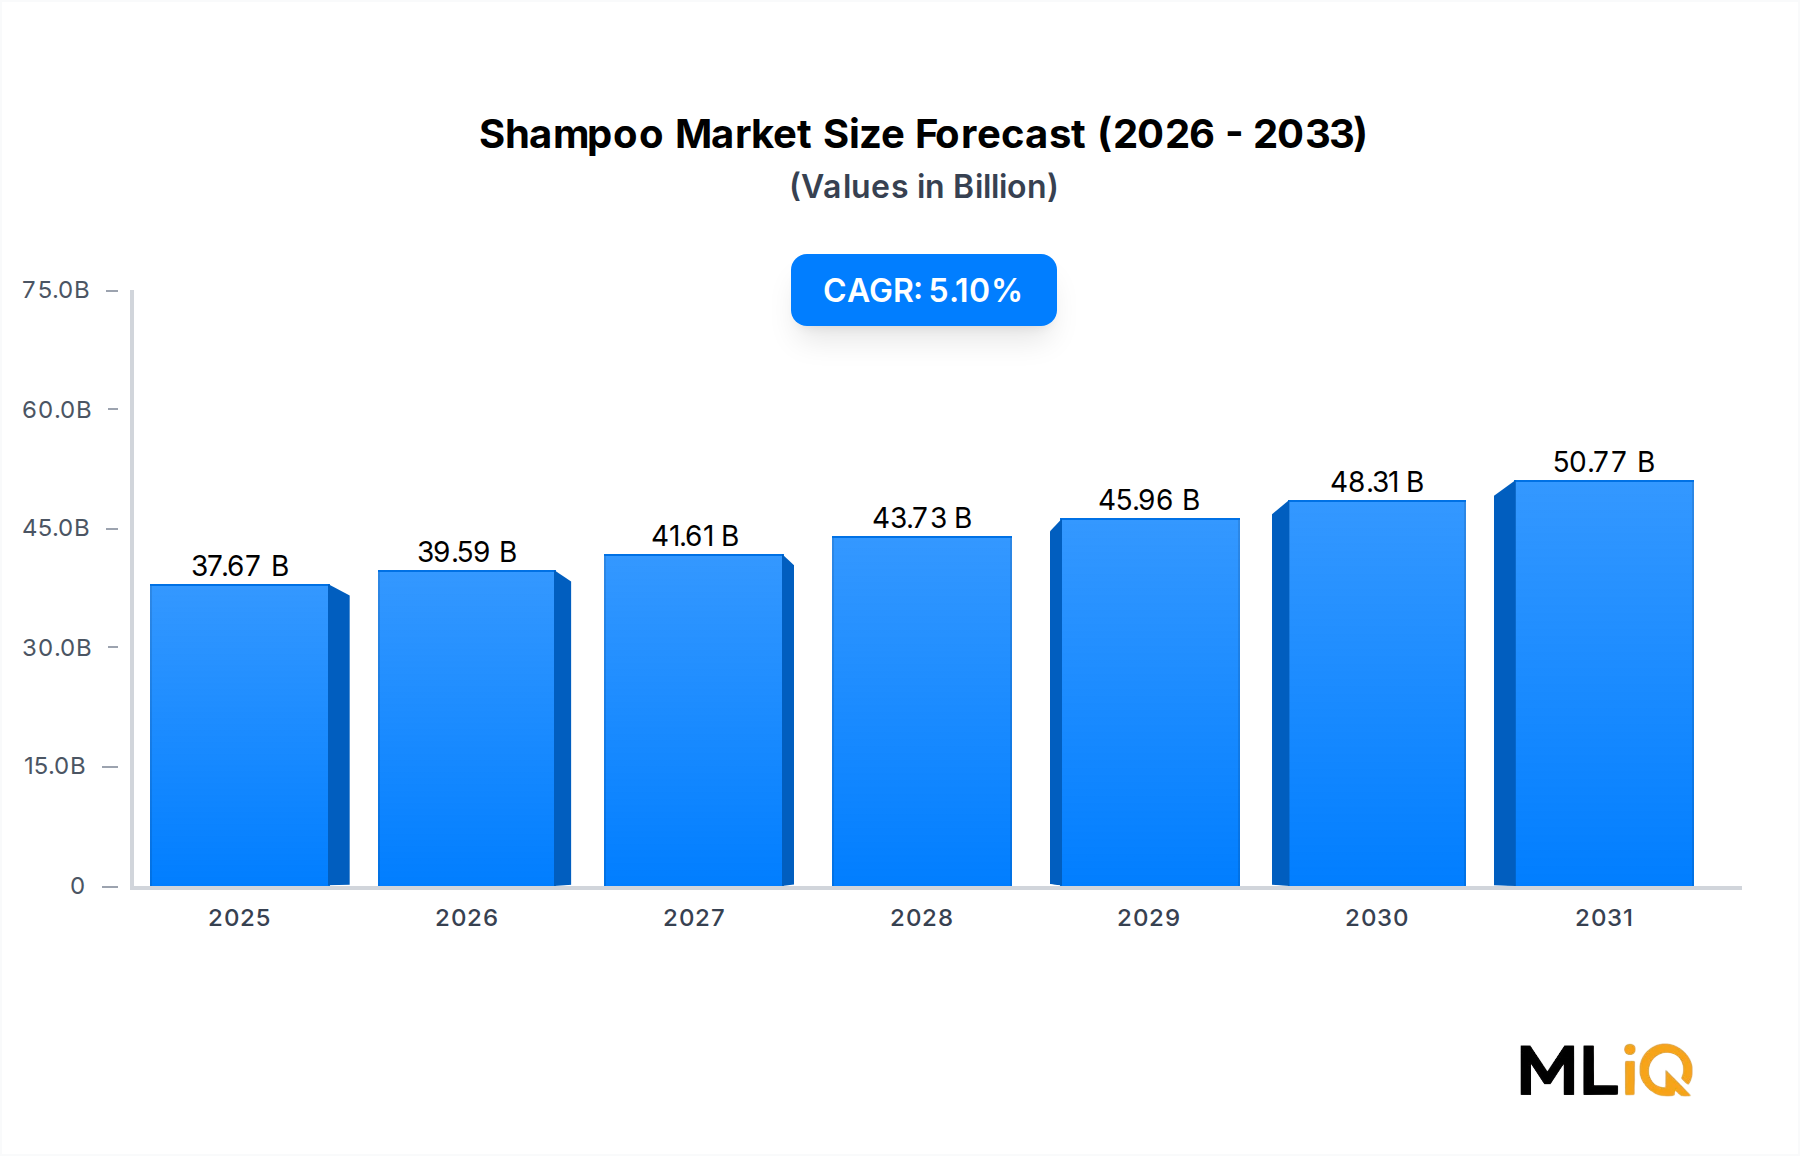
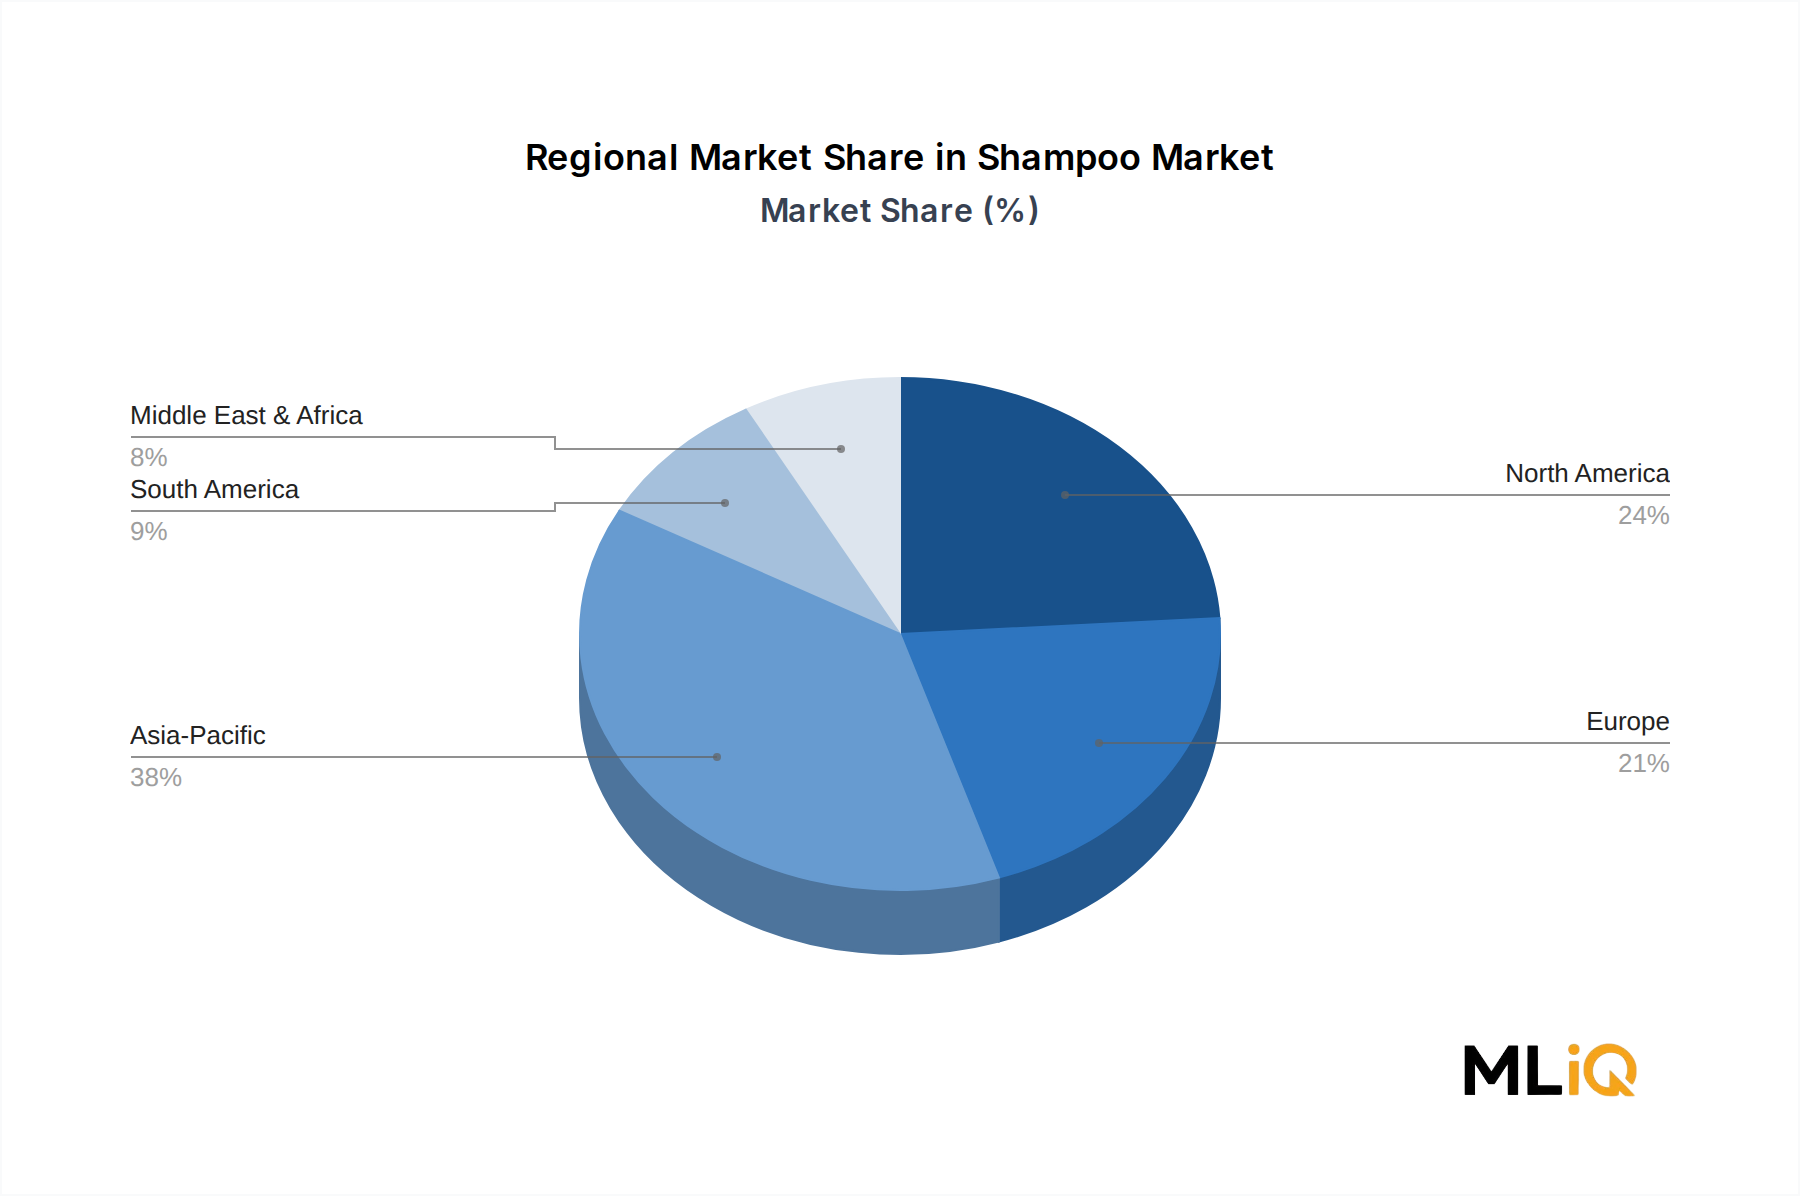
Within the Shampoo Market's product type segmentation, the non-medicated segment commands the largest revenue share, estimated at approximately 65–70% of total global market value. This dominance is rooted in the segment's broad consumer base, accessible price architecture, and the extensive brand portfolio that multinational consumer goods companies have built around everyday cleansing and conditioning benefits.
Non-medicated shampoos encompass a wide spectrum of formulations including moisturizing, volumizing, color-protecting, anti-breakage, and smoothing variants. Unlike medicated counterparts, these products do not require regulatory approval as therapeutic agents in most jurisdictions, enabling faster time-to-market and greater formulation flexibility. This regulatory lightness has historically allowed brands to respond nimbly to consumer trend shifts — from argan oil infusions in the early 2010s to keratin-enriched formulas and, more recently, probiotic and postbiotic scalp-care positioning.
The segment is further stratified by price point — low, medium, and high — with the medium tier capturing the largest share by volume. However, the high-price tier is growing at a disproportionately faster rate, driven by premiumization. Consumers are increasingly willing to pay a premium for clean-label formulations that exclude sulfates, silicones, and synthetic dyes, and brands have responded with premium product lines that carry higher margin profiles.
Key players dominating the non-medicated segment include Procter & Gamble, which leverages its Pantene and Head & Shoulders franchises (the latter straddling both non-medicated and medicated positioning); L'Oreal S.A., whose Elvive and Garnier Fructis lines maintain strong mid-tier penetration; and Unilever's portfolio encompassing Dove, TRESemmé, and Sunsilk. These companies invest heavily in consumer research and sensory science to differentiate products that are, at their chemical core, relatively similar.
The non-medicated segment also benefits from the broadest distribution footprint. Products in this category are stocked across supermarkets and hypermarkets, drug stores, mass merchandisers, departmental stores, mono-brand stores, specialty stores, and online sales channels. The omnichannel availability ensures consistent consumer access regardless of geography or income bracket.
In emerging markets such as India, Indonesia, and Brazil, the non-medicated segment is still in a volume-expansion phase, with sachets and small-format SKUs playing a critical role in driving trial among price-sensitive consumers. Hindustan Unilever Limited and Marico Limited have historically been adept at leveraging sachet economics to penetrate rural and semi-urban markets in India, where the non-medicated everyday-cleansing category represents a significant growth frontier.
Share consolidation within the non-medicated segment is occurring at the premium tier, where a smaller number of brands — often with direct-to-consumer origins — are capturing outsized revenue growth. Brands like Briogeo, Olaplex, and Function of Beauty have demonstrated that personalization and ingredient transparency can command price premiums of 3x–5x relative to mass-market alternatives, reshaping competitive dynamics and forcing legacy players to invest in premiumization strategies.
Looking ahead, the non-medicated segment's dominance is expected to persist through 2033, though its internal composition will shift progressively toward the premium and super-premium tiers as consumer sophistication deepens globally.