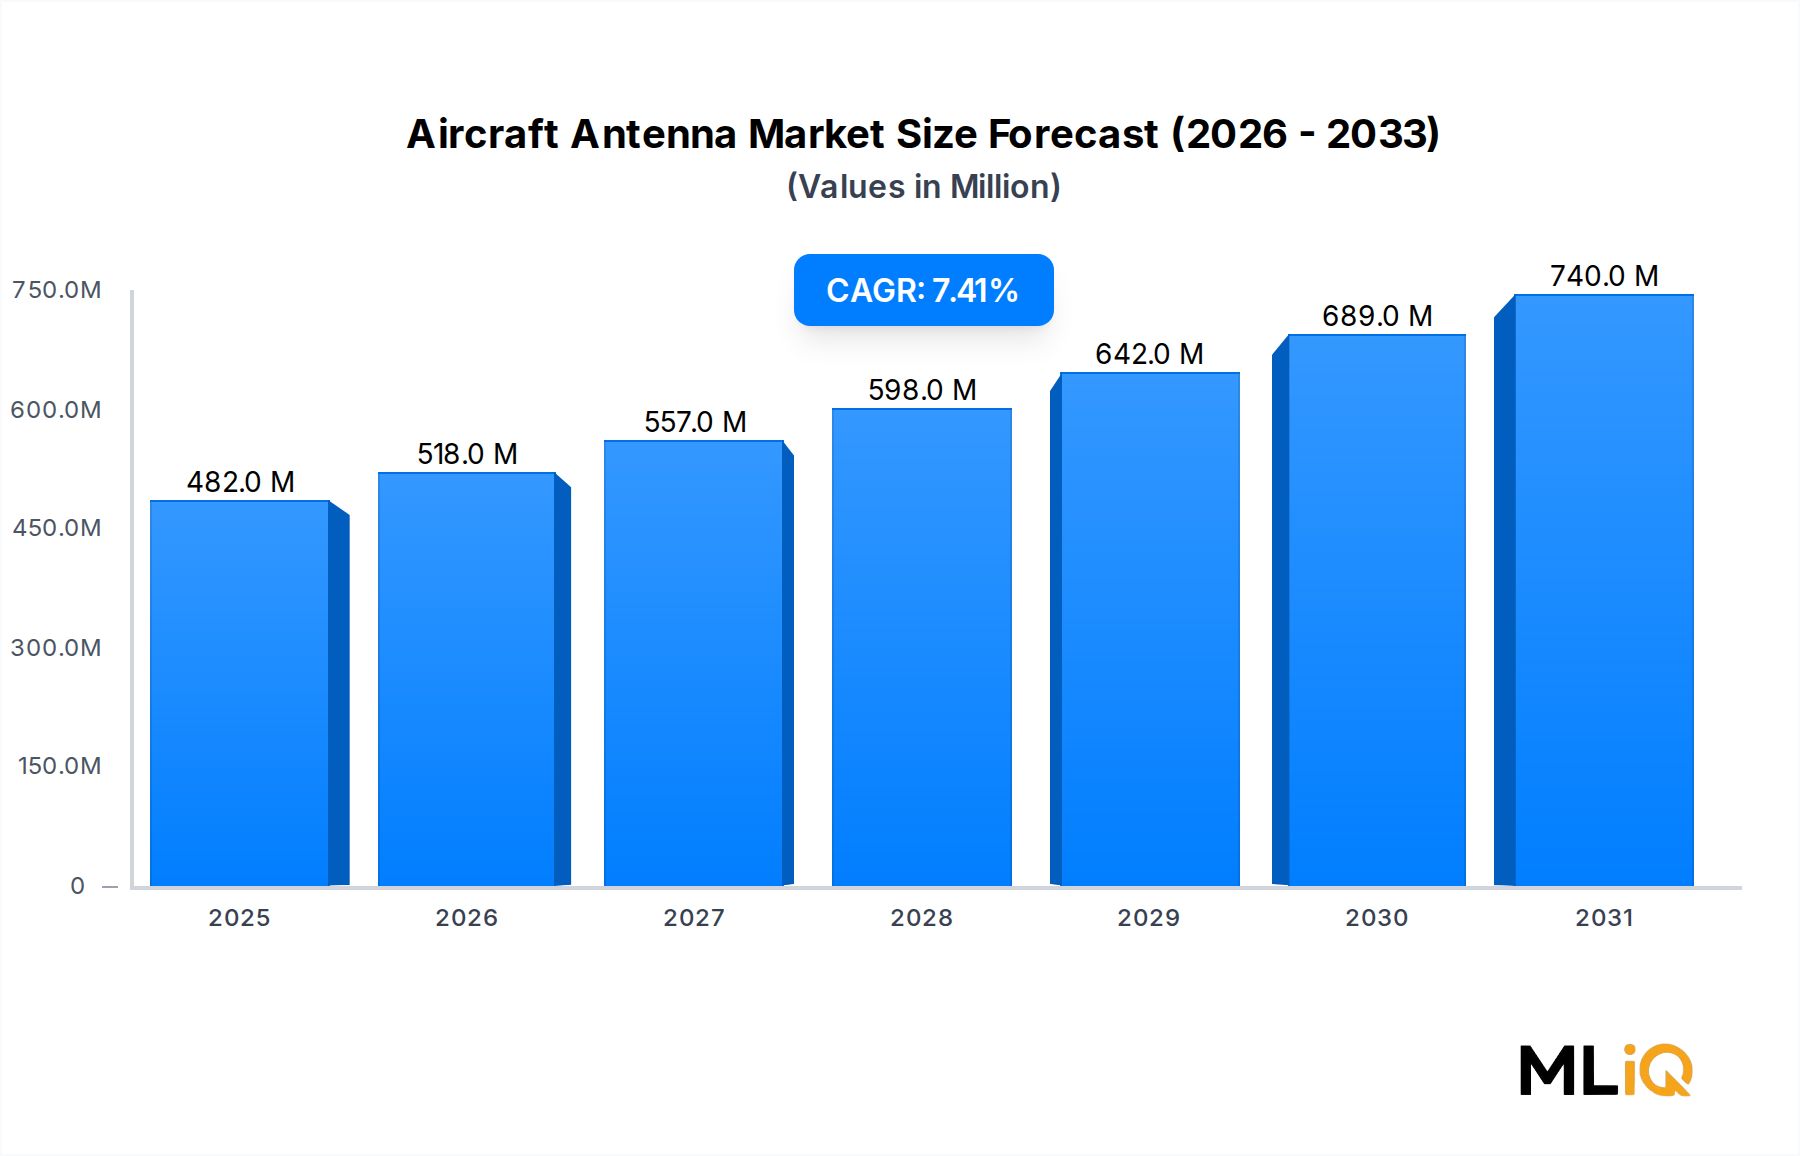
The global Aircraft Antenna Market was valued at $482.47 million in 2024 and is projected to expand at a compound annual growth rate (CAGR) of 7.4% through the forecast period, driven by accelerating demand for high-bandwidth connectivity, next-generation avionics integration, and expanding unmanned aerial vehicle (UAV) deployments worldwide. This growth trajectory places the market on course to surpass $900 million by the early 2030s, underpinned by both commercial aviation recovery and robust defense spending across major economies.
The primary macro tailwinds sustaining this momentum include the global rollout of in-flight connectivity services, the widespread adoption of satellite-based augmentation systems, and increasing regulatory mandates for advanced communication and navigation equipment on commercial and military aircraft. Airlines and defense agencies alike are upgrading legacy antenna arrays to support Ka-band, Ku-band, and emerging wideband communication protocols, generating replacement and retrofit demand in parallel with new platform installations.
Demand is further amplified by the rapid proliferation of unmanned systems across both defense and commercial applications. UAVs require compact, lightweight, and highly reliable antenna solutions capable of sustaining beyond-line-of-sight (BLOS) communications and precision navigation, opening a distinct high-growth segment within the broader market. The integration of multi-function antennas that simultaneously handle communication, surveillance, and navigation functions is emerging as a key design priority for OEMs and system integrators.
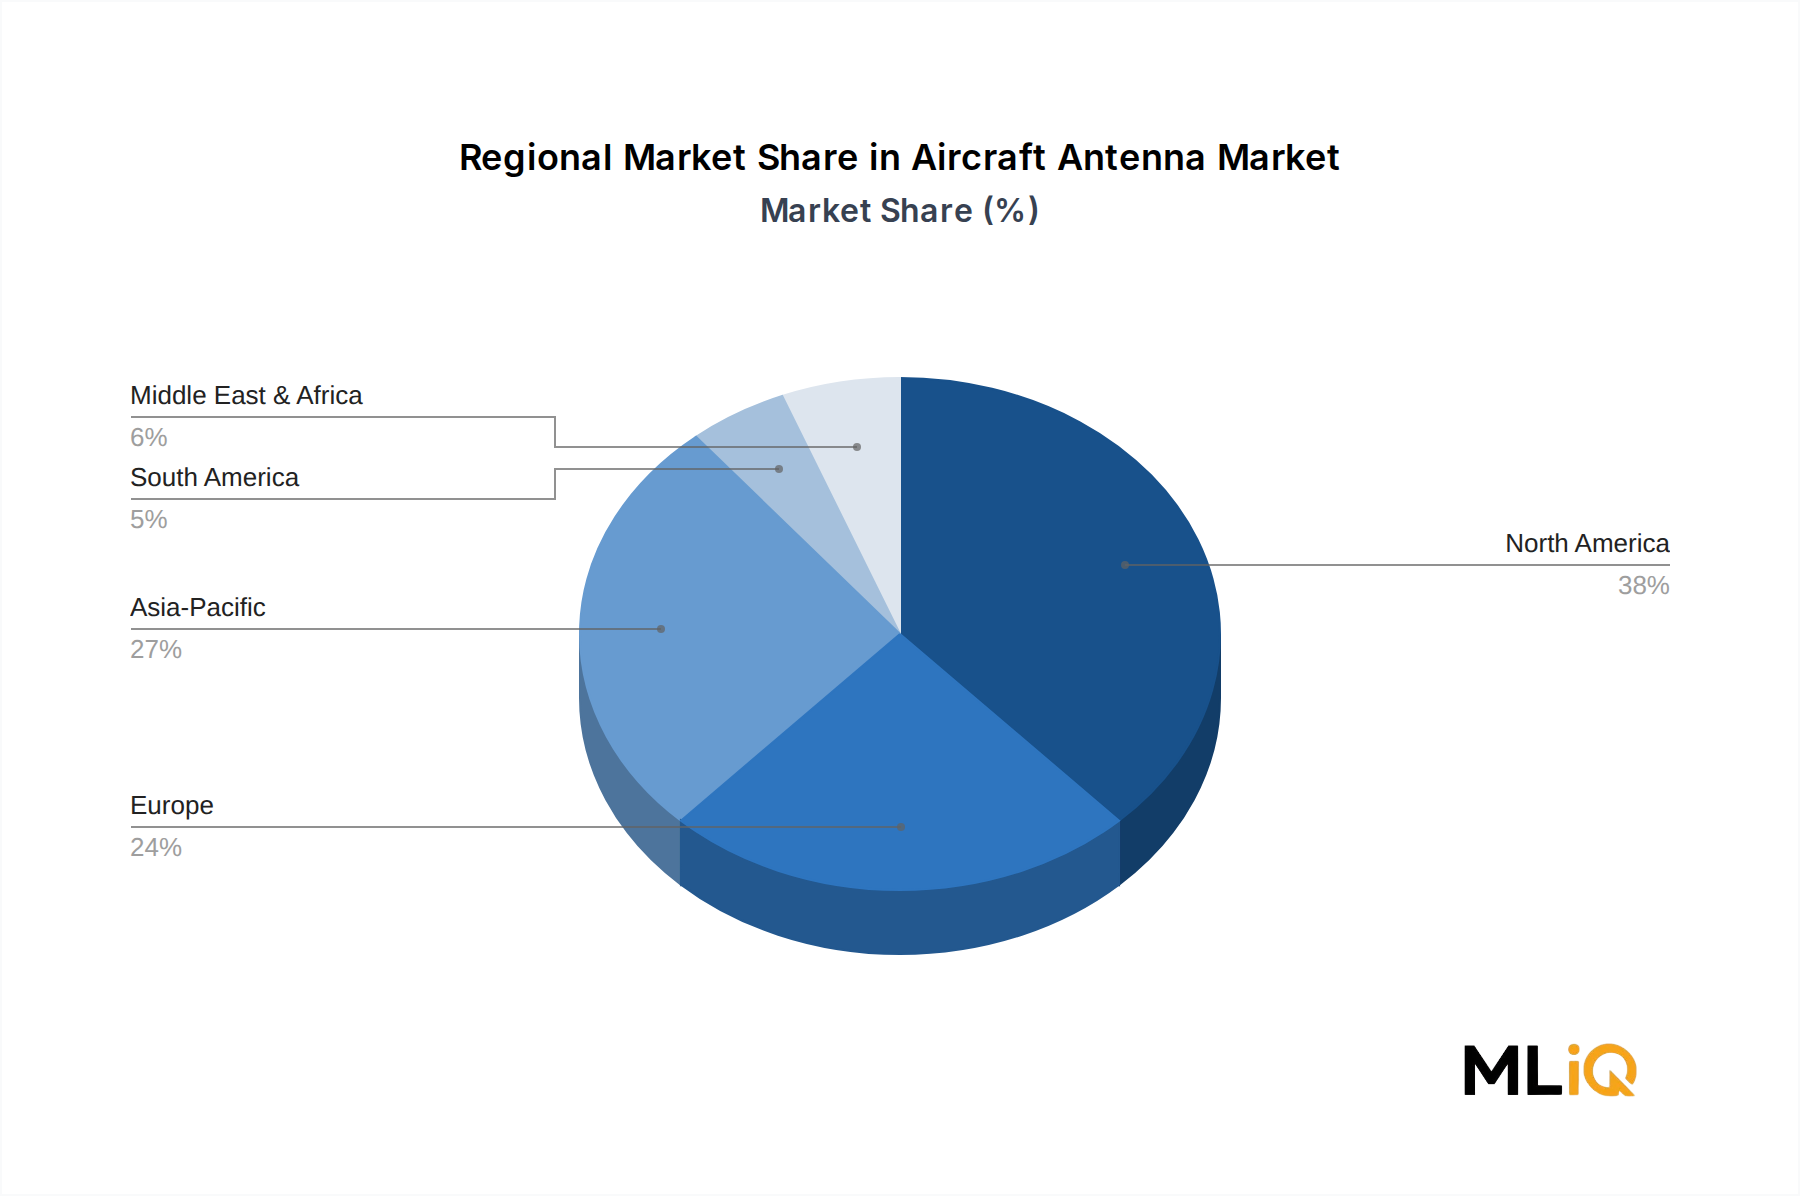
Geographically, North America retains the largest revenue share, supported by the United States Department of Defense modernization programs and a dense commercial aviation fleet requiring continuous upgrades. However, the Asia Pacific region is recording the fastest growth rate, fueled by rising air passenger traffic, indigenous defense platform development in China, India, and South Korea, and increasing investments in satellite infrastructure.
From a competitive standpoint, the market is moderately consolidated, with established players such as Honeywell International Inc., Cobham plc, and Harris Corporation holding significant market share alongside specialized manufacturers like Sensor Systems Inc. and Antcom Corporation. Strategic focus areas include phased-array antenna development, low-profile conformal antenna designs, and software-defined radio compatibility.
Looking forward, the convergence of 5G terrestrial networks with aeronautical communication standards, the expansion of low-Earth orbit (LEO) satellite constellations, and the acceleration of urban air mobility (UAM) programs are expected to create transformative demand inflection points within the Aircraft Antenna Market through 2030 and beyond.