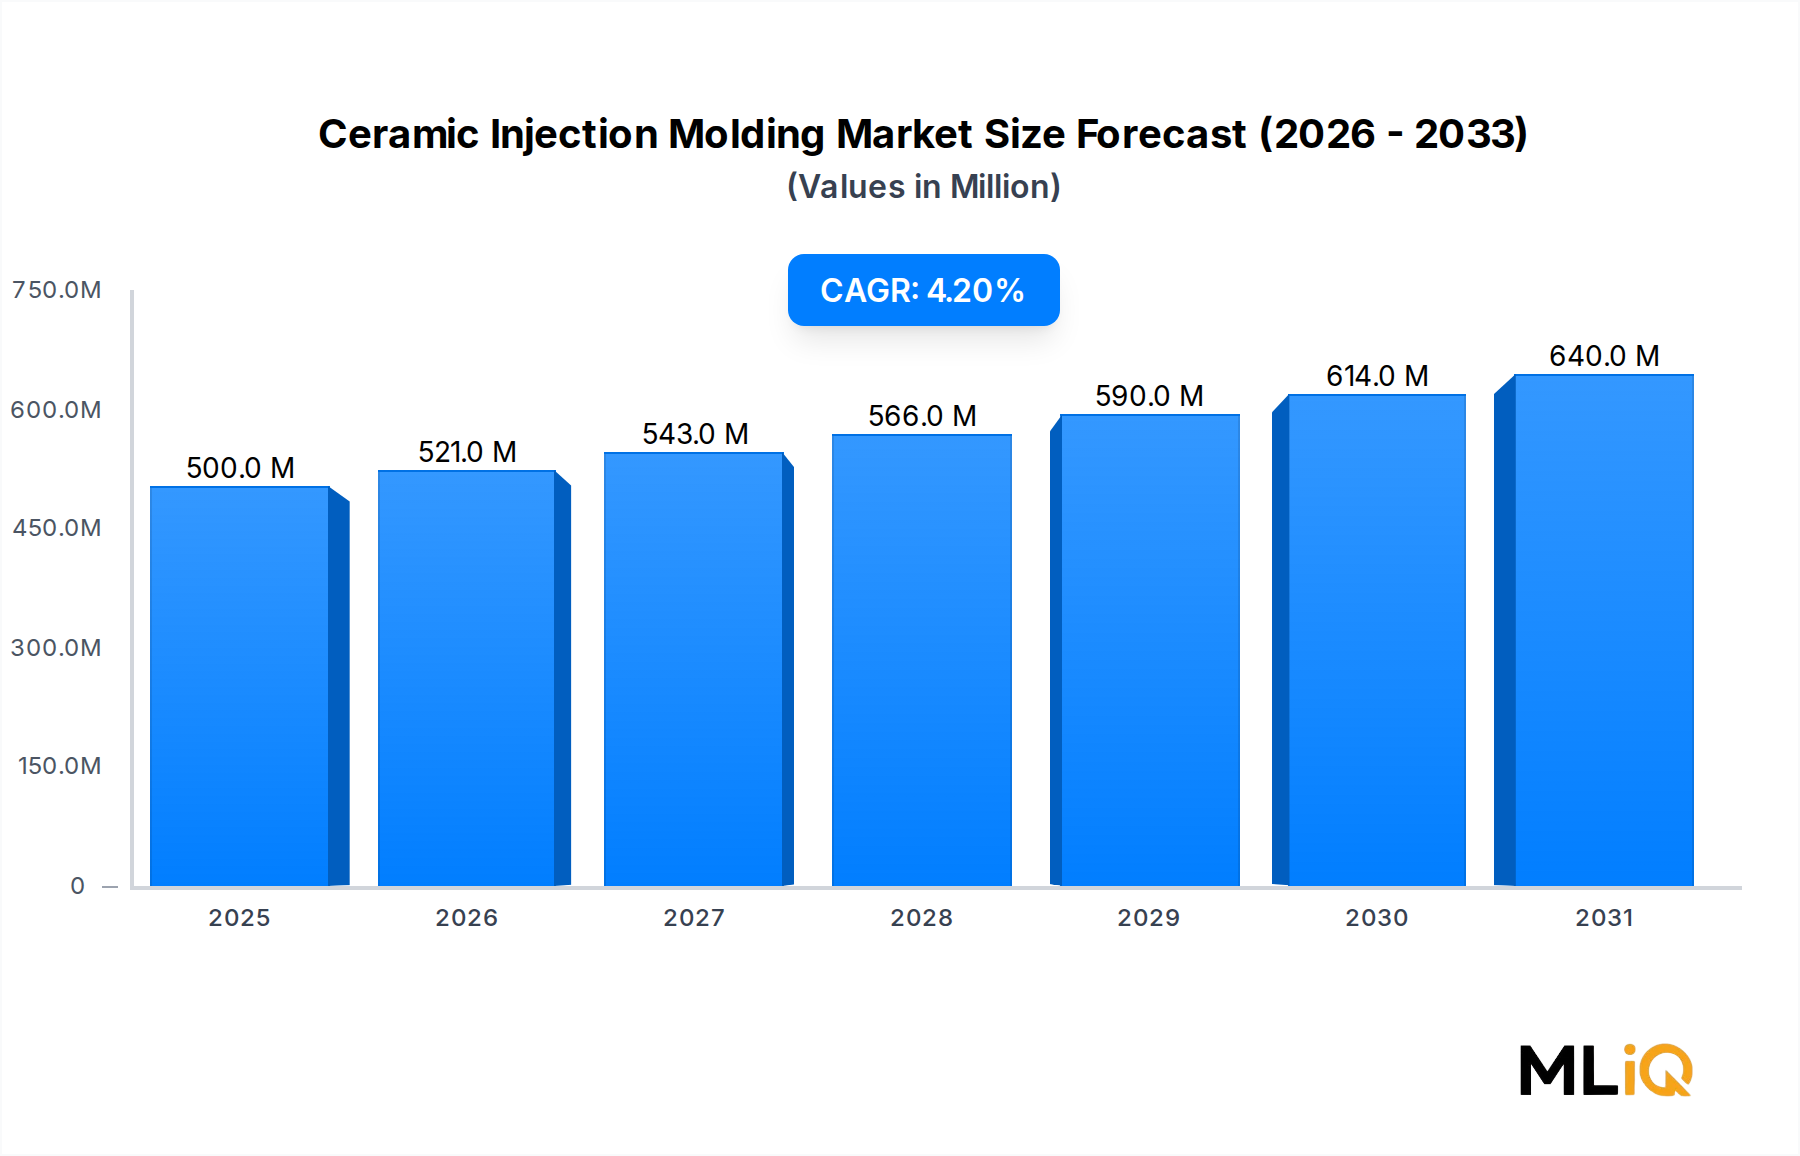
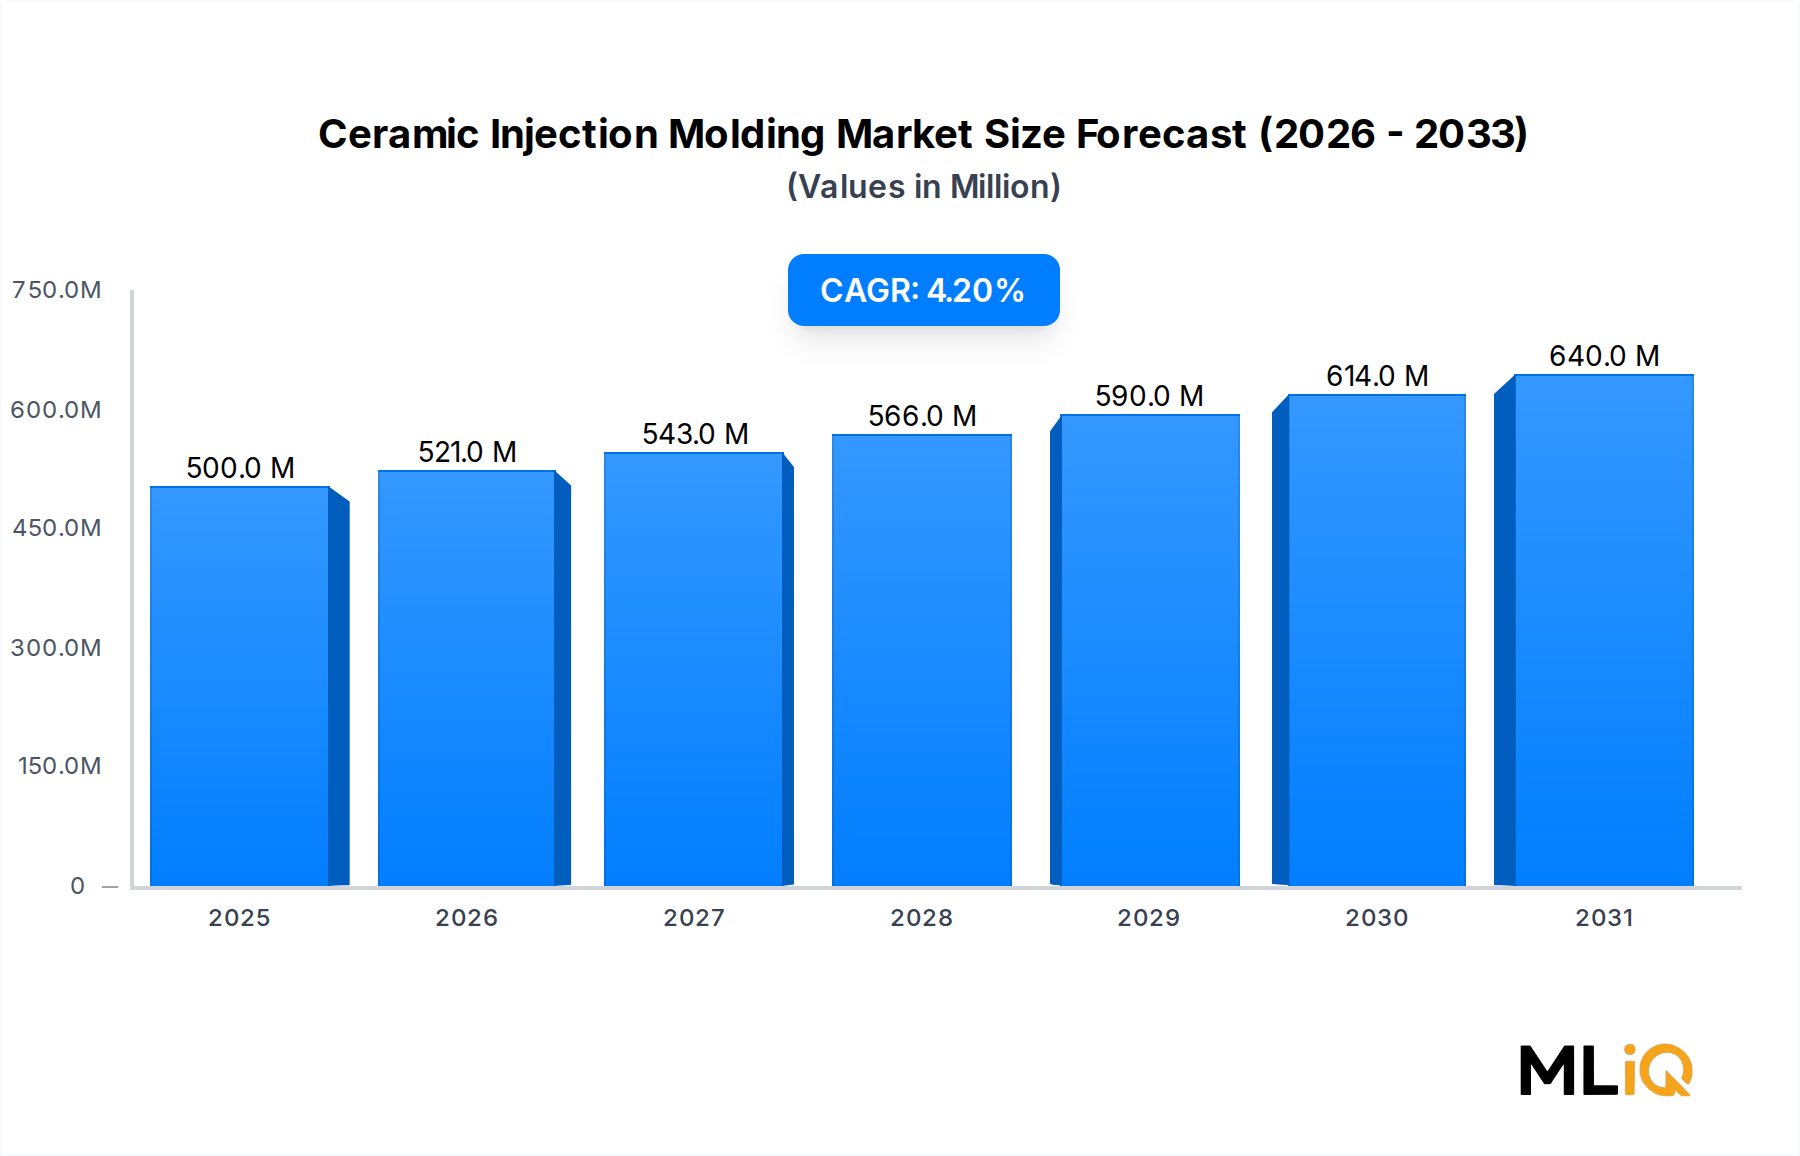
The global Ceramic Injection Molding Market was valued at $500.16 million and is projected to expand at a compound annual growth rate of 4.2% through the forecast period, reflecting sustained demand from high-precision industrial, healthcare, and electronics end-use sectors. This market occupies a specialized but strategically vital niche within the broader Advanced Ceramics Market, leveraging the convergence of materials science advancement and precision manufacturing capabilities.
Ceramic injection molding (CIM) enables the net-shape fabrication of complex, high-tolerance ceramic components that are otherwise difficult or impossible to achieve through conventional machining or pressing. The process involves mixing fine ceramic powders—primarily alumina and zirconia—with thermoplastic or wax-based binders, injecting the feedstock into precision molds, debinding, and sintering to achieve final geometry. This process chain unlocks design freedom that drives its adoption across demanding verticals.
Key demand catalysts include the accelerating miniaturization of electronic components, the surge in minimally invasive surgical instruments requiring biocompatible ceramic parts, and the automotive industry's transition toward electrification, which creates new requirements for thermally stable, electrically insulating ceramic components in battery management systems, sensors, and fuel cell assemblies. The healthcare sector has emerged as a particularly high-value application zone, with zirconia dental prosthetics and alumina orthopedic components driving volume growth.
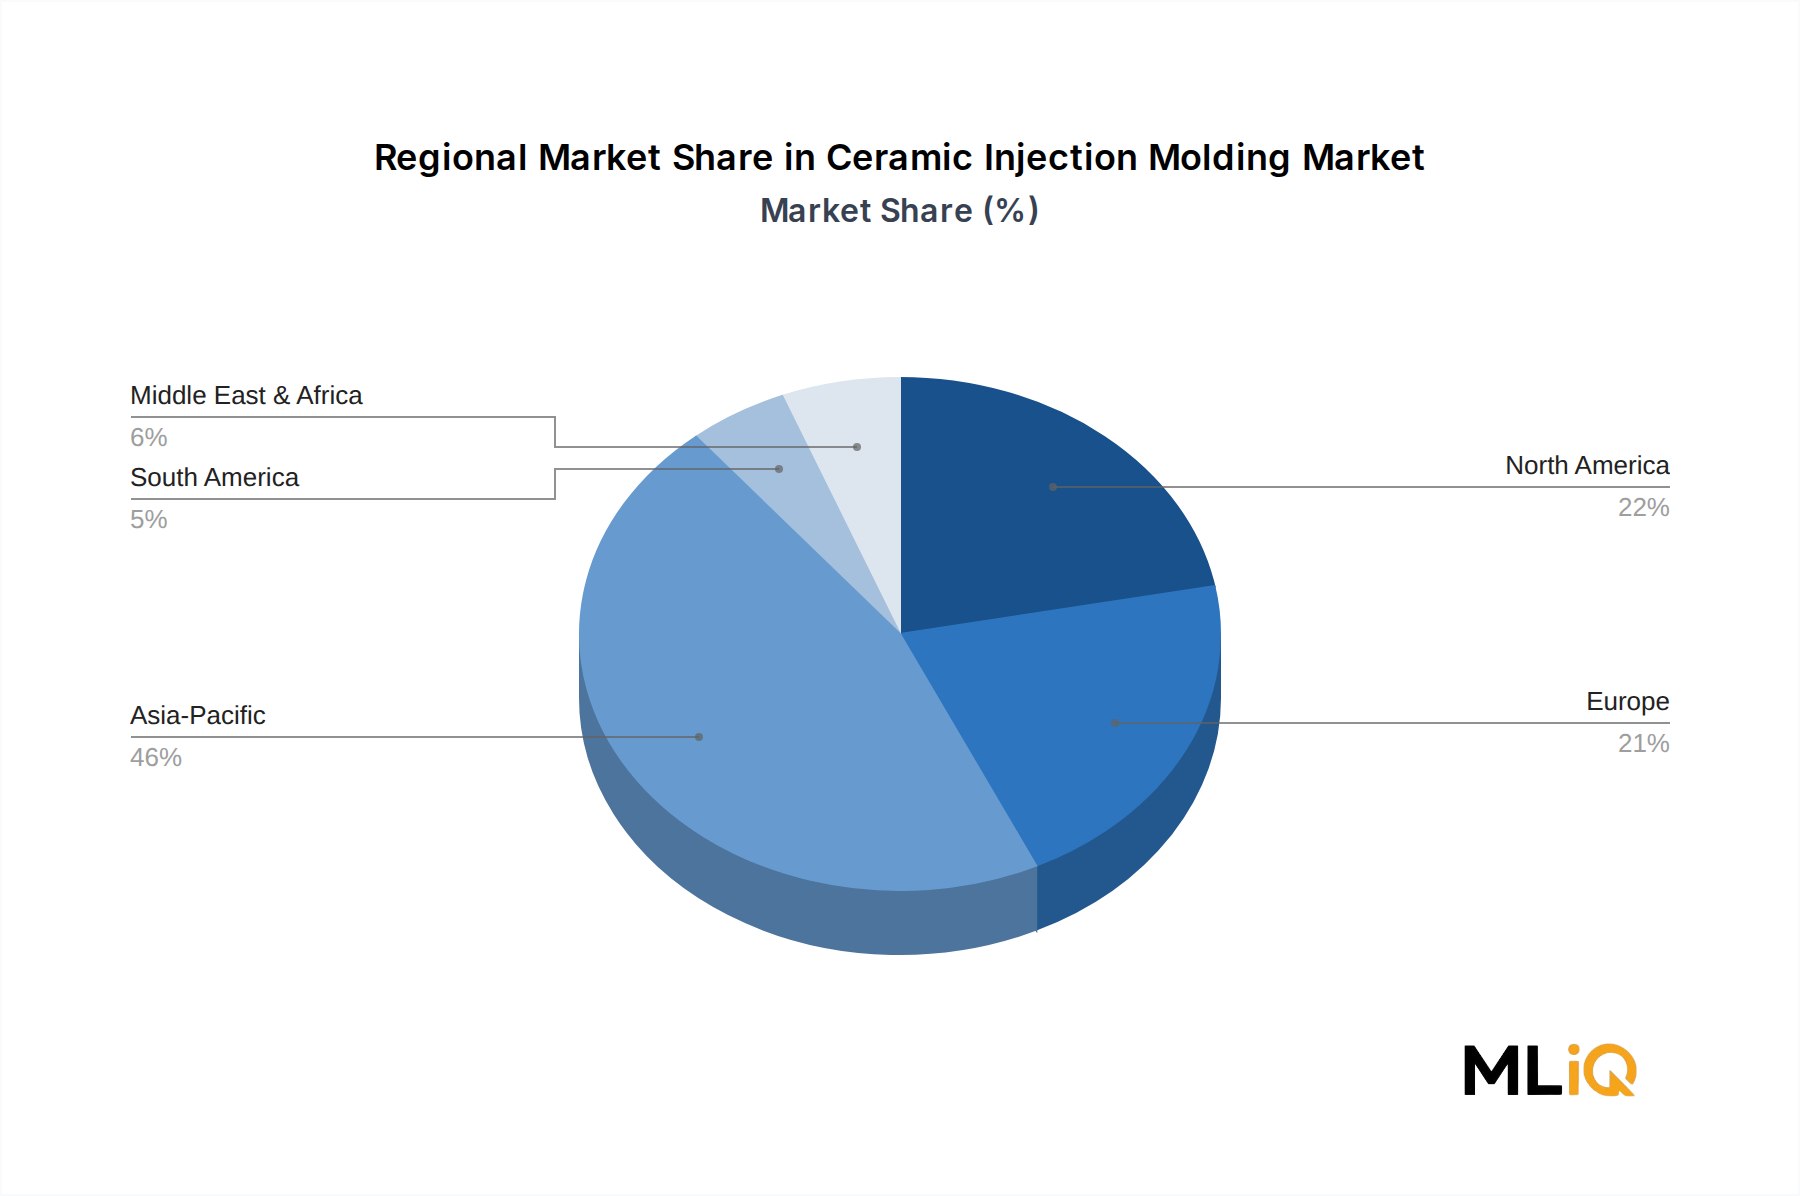
Macroeconomic tailwinds further amplify market momentum. Industrial reshoring trends in North America and Europe are stimulating investment in advanced manufacturing processes including CIM. Simultaneously, China's aggressive build-out of semiconductor fabrication capacity creates structural demand for ceramic precision components used in wafer handling, plasma chambers, and chemical vapor deposition equipment.
On the technology frontier, feedstock formulation innovations—including water-soluble binder systems and catalytic debinding approaches—are reducing cycle times and lowering energy consumption, improving the economics of CIM relative to competing processes. Integration of digital manufacturing tools such as simulation-driven mold design and in-line sintering profile optimization are further compressing defect rates.
The market's growth trajectory, while moderate at 4.2% CAGR, is characterized by high-value unit economics and significant barriers to entry, including proprietary feedstock formulations, sintering know-how, and quality certification requirements in medical and aerospace segments. This underpins pricing stability and margin resilience relative to more commoditized manufacturing markets. Looking ahead, the convergence of CIM with additive manufacturing hybridization and Industry 4.0 process monitoring is expected to unlock new application frontiers and expand the addressable market beyond $620 million by the end of the forecast window.