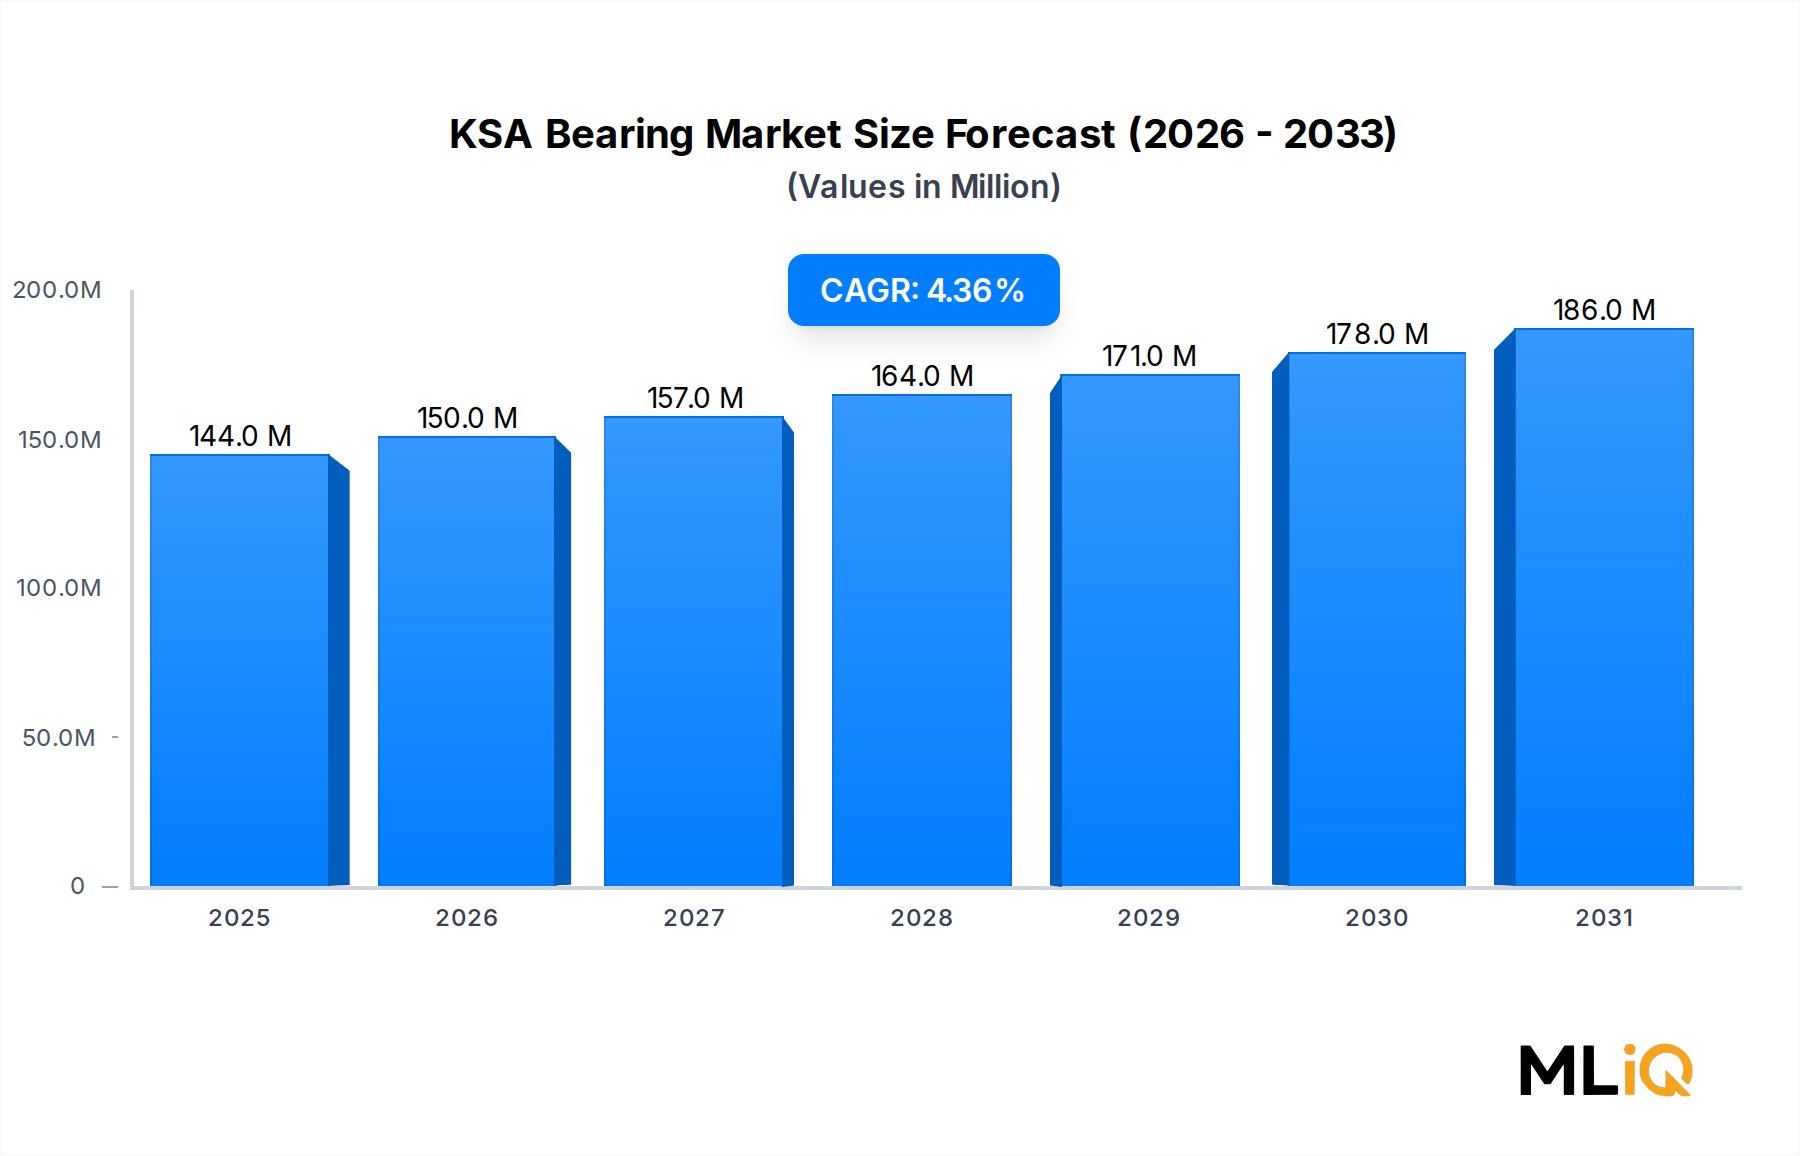
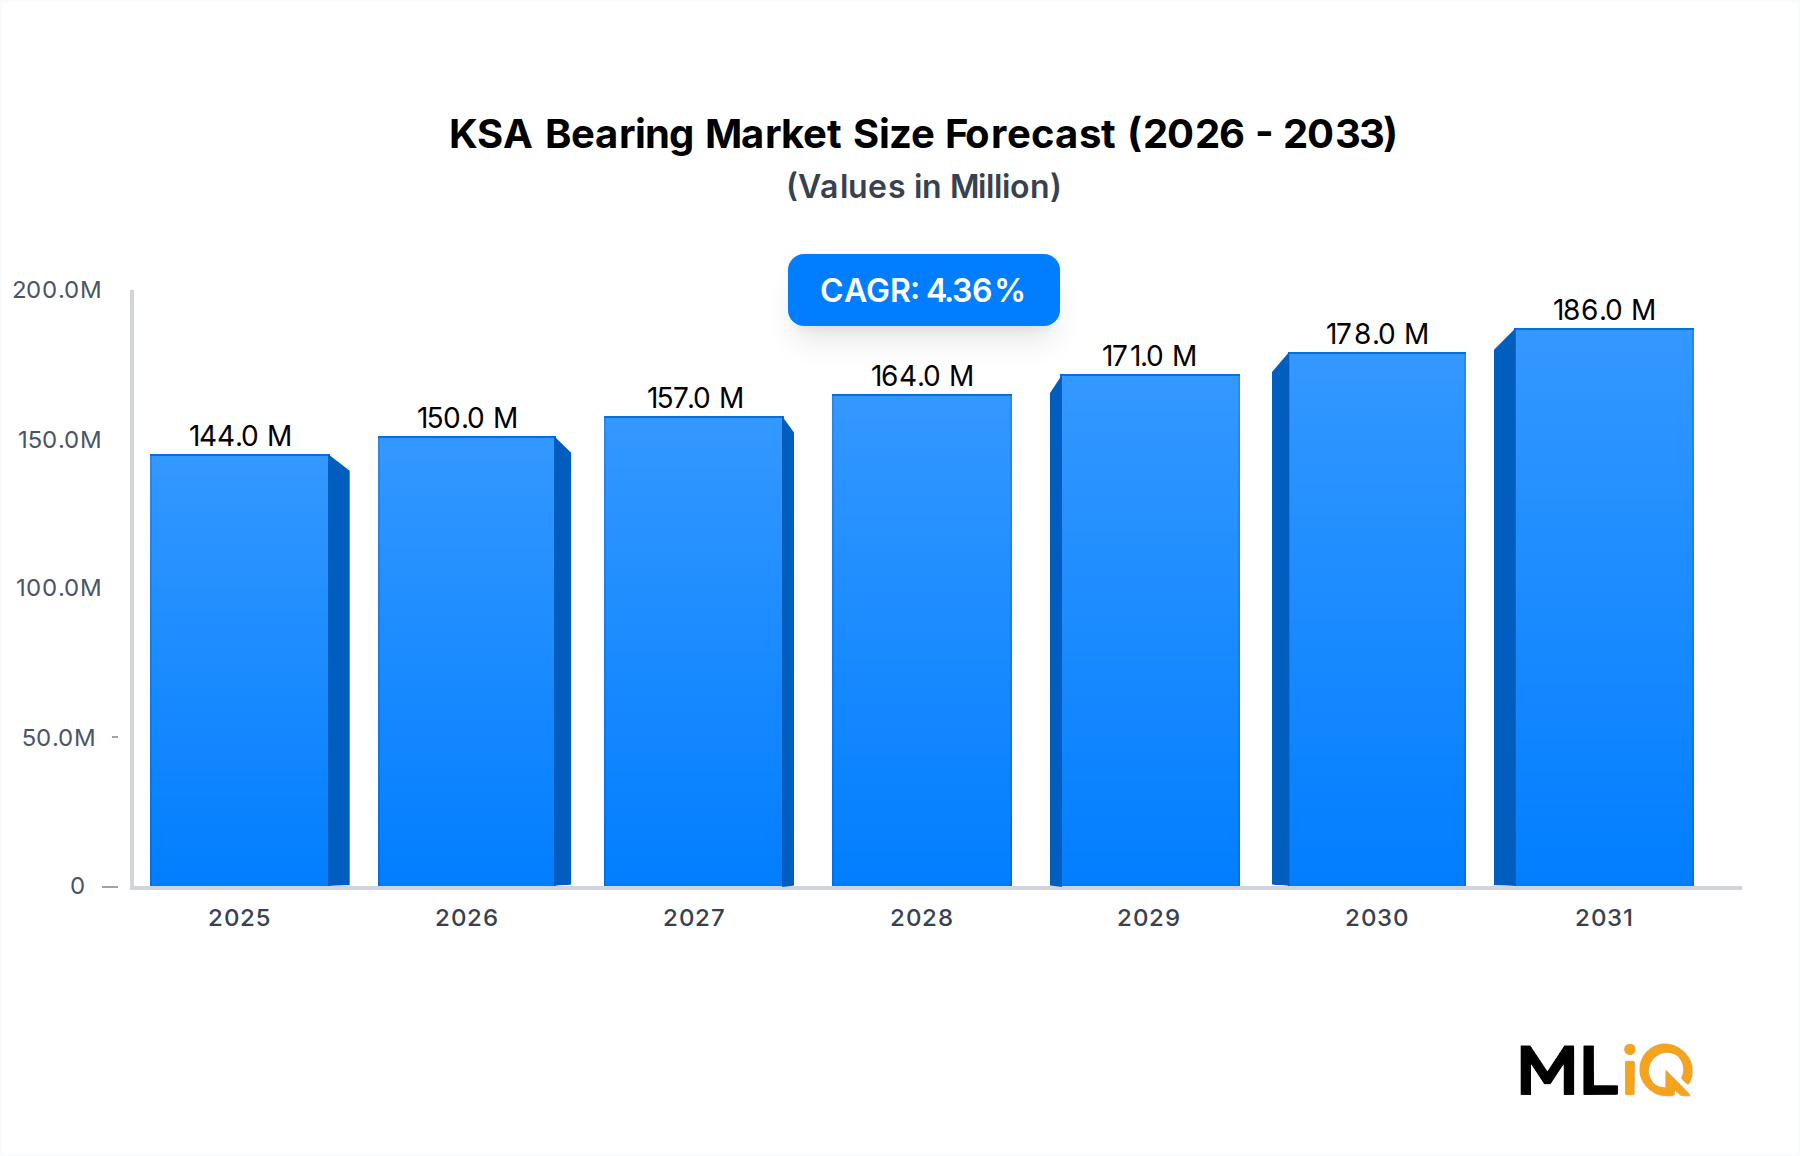
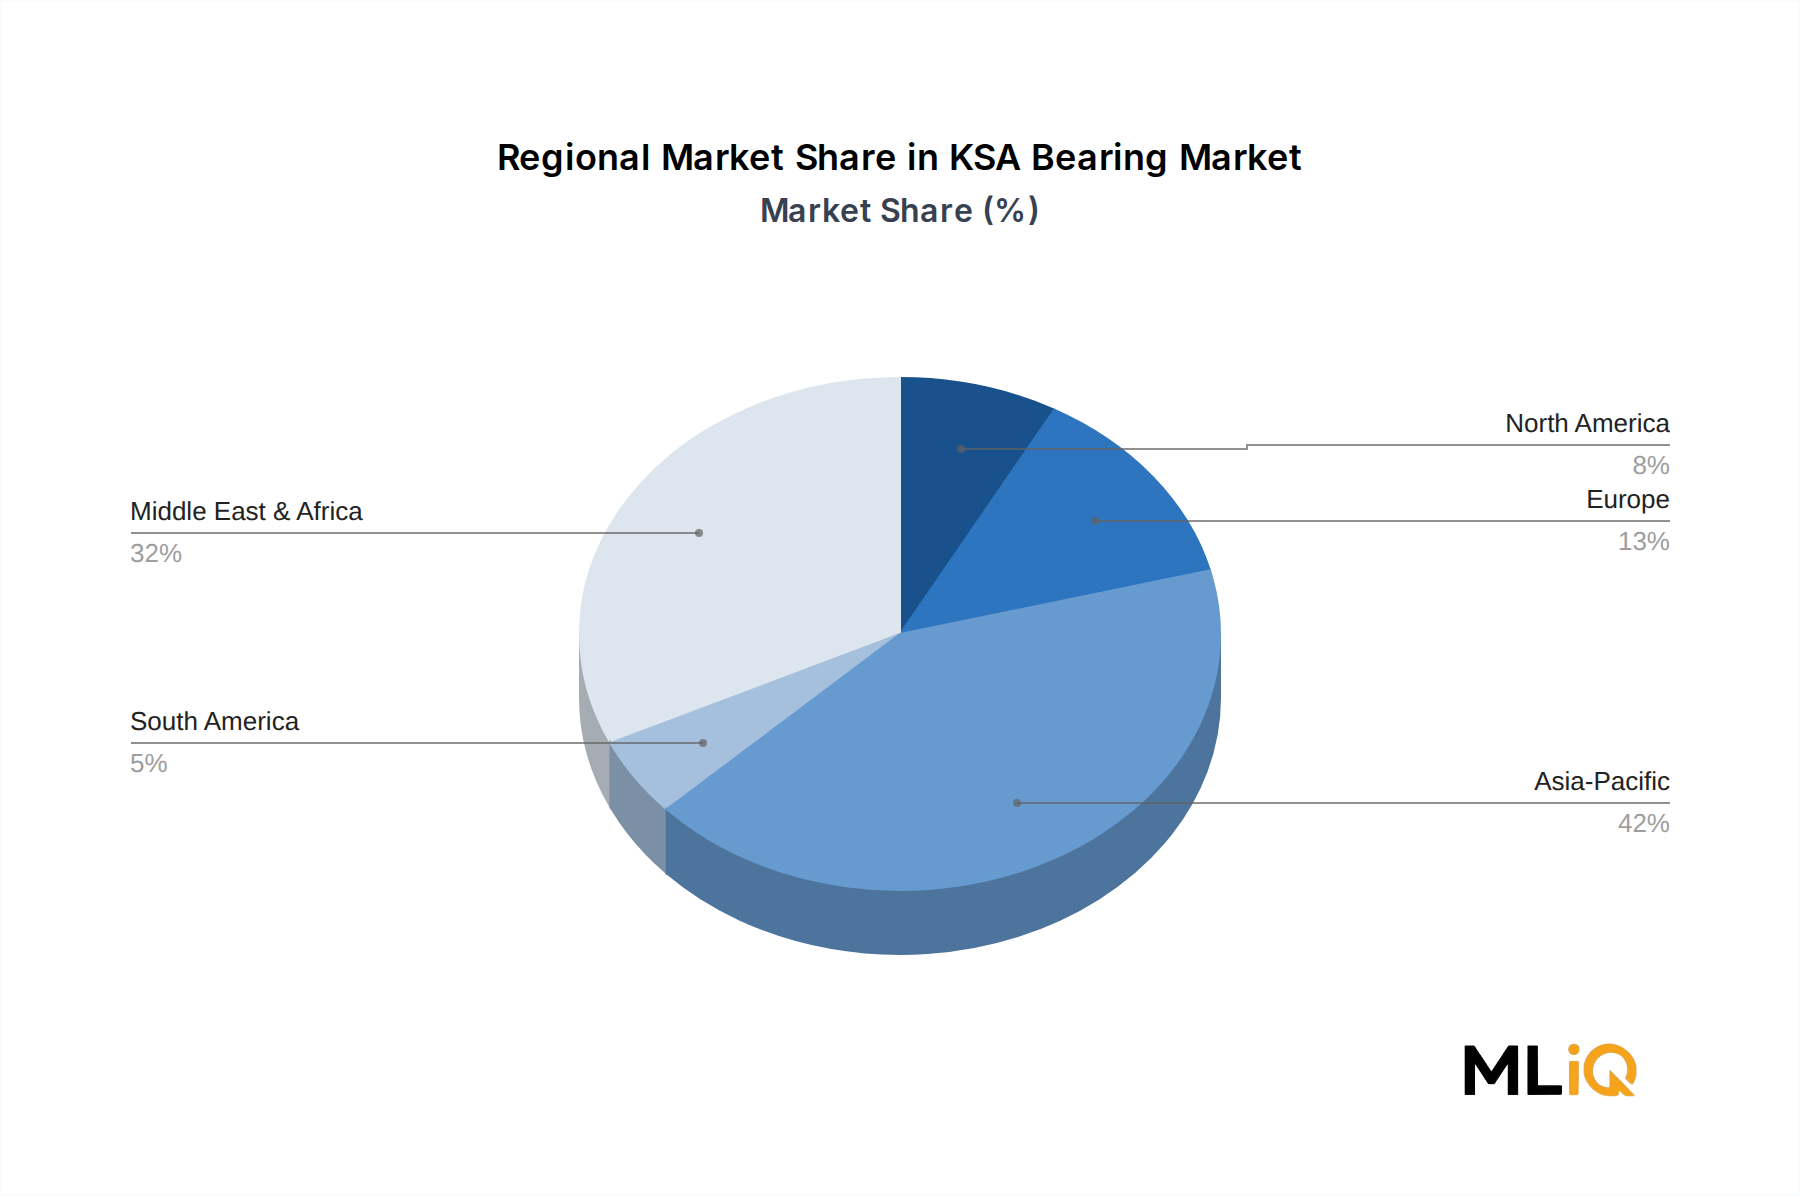
Several quantifiable drivers and constraints shape the KSA Bearing Market's trajectory over the forecast period.
The most consequential demand driver is Saudi Arabia's Vision 2030 infrastructure expenditure program, which has allocated over SAR 1 trillion in capital projects across transportation, energy, tourism, and industrial sectors. Each major project category—whether airports, railways, manufacturing parks, or desalination facilities—generates direct and sustained bearing demand through construction equipment, process machinery, and installed base maintenance.
Automotive fleet expansion represents the second major driver. Saudi Arabia's annual vehicle sales volumes, consistently above 500,000 units in recent years and projected to grow with population increase and urbanization, create a continuous OEM supply requirement and an expanding aftermarket replacement base. The average bearing replacement cycle in passenger vehicles under Saudi operating conditions (high ambient temperatures, dusty environments, frequent urban stop-start driving) is estimated at 40,000–60,000 kilometers, supporting high-frequency aftermarket demand.
The emergence of electric vehicles as a meaningful market segment introduces a structural shift in bearing specifications. Electric vehicles consume approximately 40% more bearings per unit than equivalent ICE vehicles when auxiliary motor bearings are included. As Saudi Arabia progresses toward its EV adoption targets and the Electric Vehicle Components Market matures domestically, bearing specifications will shift toward higher-precision, lower-noise, and higher-speed-rated products.
On the constraint side, the market's heavy dependence on imports introduces supply chain vulnerability. Approximately 80–85% of bearings consumed in Saudi Arabia are imported, primarily from Germany, Japan, Sweden, China, and India. Currency fluctuations, shipping disruptions, and trade policy changes create pricing volatility that compresses distributor margins and complicates end-user procurement planning.
Quality differentiation challenges also constrain market development. The proliferation of counterfeit and substandard bearings in mid-market distribution channels undermines the total cost of ownership proposition of premium brands and creates equipment reliability risks for industrial operators. Industry estimates suggest that counterfeit bearings account for 10–15% of the aftermarket replacement segment in some GCC channels.
Finally, the relatively nascent state of domestic bearing manufacturing means that Saudi end-users lack local supply alternatives for critical or specialized bearing types, extending lead times and increasing inventory carrying costs.