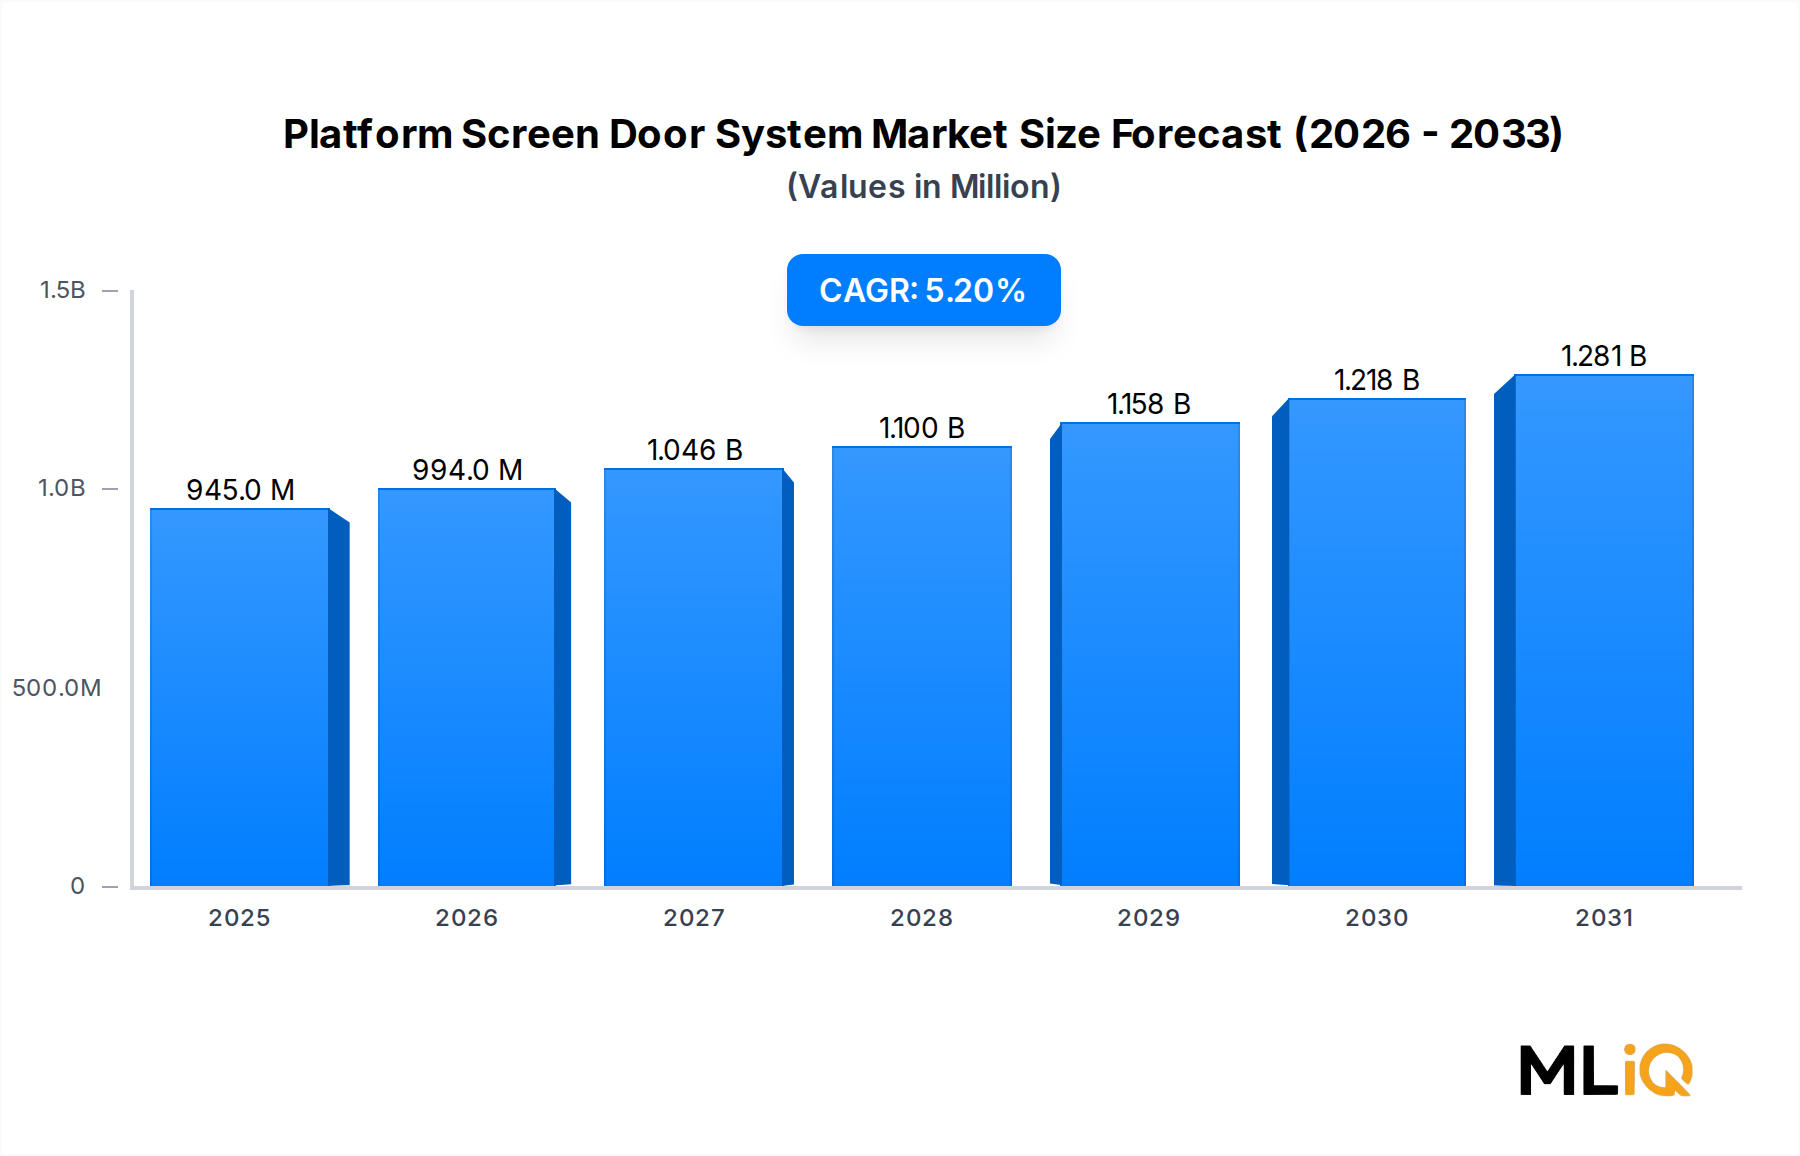
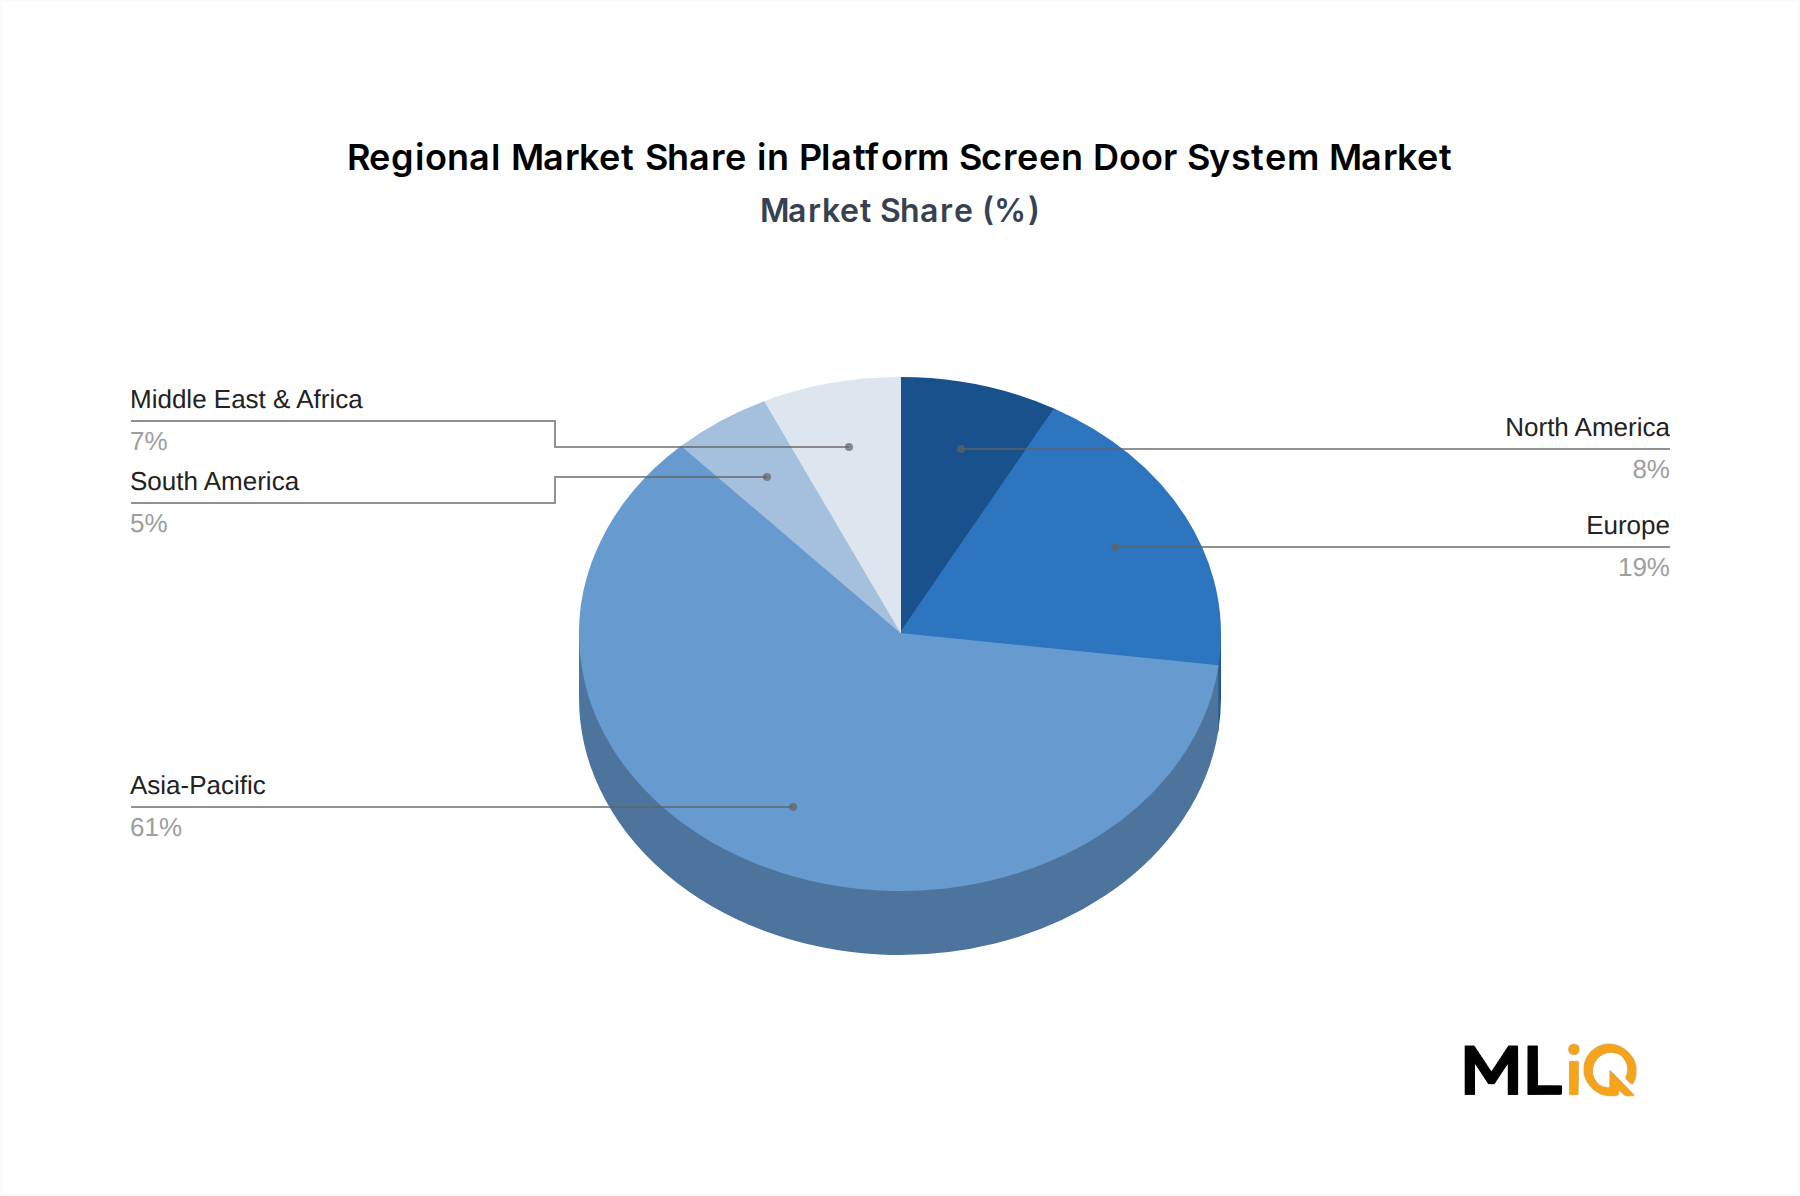
The Platform Screen Door System Market is characterized by significant cross-border trade flows, with manufacturing concentrated in China, Europe, and Japan supplying infrastructure projects across emerging and developed markets globally.
China is the dominant exporting nation for PSD systems and components, leveraging large-scale domestic manufacturing capacity, vertically integrated supply chains, and competitive pricing to win contracts across Southeast Asia, South Asia, the Middle East, and Africa. Chinese manufacturers including Fangda Group and Jiacheng Railway International have established international project delivery capabilities, often bundling PSD supply with installation and commissioning services as part of comprehensive transit infrastructure packages under China's Belt and Road Initiative framework.
Europe — particularly Germany, France, Switzerland, and Spain — exports premium, high-specification PSD systems primarily to other European markets, the Gulf Cooperation Council, and select Asia Pacific clients where system certification under EN and IEC standards is contractually mandated. European systems command significant price premiums relative to Chinese competitors, justified by advanced safety certifications, integration complexity, and long-term maintenance contract value.
Japan exports PSD technology primarily to Southeast Asian markets — notably Singapore, Malaysia, Thailand, and Vietnam — where Japanese transit operators have strong historical infrastructure influence and technical standards alignment.
Tariff and non-tariff barriers represent a meaningful friction point in cross-border PSD trade. India's Production Linked Incentive (PLI) scheme and elevated import duties on manufactured transit equipment create strong incentives for domestic manufacturing or local assembly joint ventures, partially redirecting demand from pure imports toward in-country production arrangements. Similarly, the United States' Buy America provisions under federal transit funding programs effectively require domestic content thresholds for PSD systems procured through federally funded projects, limiting direct imports and encouraging local manufacturing partnerships.
The EU's Carbon Border Adjustment Mechanism (CBAM), while primarily targeting raw materials, is creating indirect compliance costs for exported manufactured goods with high-carbon upstream inputs, which may influence sourcing decisions for steel and aluminum-intensive PSD components over the medium term.