Market Lens IQ is a global market intelligence and strategic consulting firm delivering advanced syndicated research reports, customized industry analysis, competitive intelligence, and data-driven advisory solutions to organizations across international markets. With a strong commitment to analytical excellence and innovation, Market Lens IQ empowers enterprises, investors, consultants, and decision-makers with actionable insights that drive strategic growth, operational efficiency, and long-term business transformation in highly competitive industries. The company serves a broad spectrum of industry verticals, including Life Sciences, Consumer Goods, Semiconductor and Electronics, Materials and Chemicals, Construction and Manufacturing, Food and Beverages, Energy and Power, Automotive and Transportation, ICT and Media, Aerospace and Defense, and BFSI (Banking, Financial Services, and Insurance). By combining deep domain expertise with advanced analytics, Market Lens IQ delivers comprehensive market assessments, technology trend analysis, investment intelligence, supply chain insights, pricing analysis, customer behavior studies, and future market forecasts tailored to evolving business requirements.
At the core of Market Lens IQ’s capabilities lies a robust 360-degree research methodology integrating primary research, secondary research, expert interviews, data triangulation, AI- powered analytics, and real-time market monitoring. Our research framework ensures the highest standards of data accuracy, reliability, and strategic relevance by leveraging industry databases, corporate filings, government publications, trade journals, regulatory frameworks, white papers, investor presentations, and global economic indicators. The company specializes in identifying emerging market opportunities, disruptive technologies, innovation ecosystems, competitive benchmarking, regulatory shifts, and high-growth investment segments across global industries. Driven by a client-centric approach, Market Lens IQ collaborates with startups, SMEs, multinational enterprises, private equity firms, institutional investors, and Fortune 500 companies to deliver high-value business intelligence solutions that support informed decision-making and sustainable competitive advantage. Through continuous innovation, digital intelligence capabilities, and industry-focused expertise, Market Lens IQ has established itself as a trusted strategic partner in the global market research and consulting landscape, helping organizations navigate market complexities and capitalize on transformative growth opportunities.
Air Quality Monitoring Market: 6.7% CAGR, $5.78B Forecast
Air Quality Monitoring Market
Air Quality Monitoring Market: 6.7% CAGR, $5.78B Forecast
Air Quality Monitoring Market by Product Type (Indoor Monitor and Outdoor Monitor), by Pollutant (Chemical, Biological, Physical), by End User (Government & Academic, Oil & Gas, Power Plants, Commercial & Residential, Others), by North America (United States, Canada, Mexico), by South America (Brazil, Argentina, Rest of South America), by Europe (United Kingdom, Germany, France, Italy, Spain, Russia, Benelux, Nordics, Rest of Europe), by Middle East & Africa (Turkey, Israel, GCC, North Africa, South Africa, Rest of Middle East & Africa), by Asia Pacific (China, India, Japan, South Korea, ASEAN, Oceania, Rest of Asia Pacific) Forecast 2026-2034
Updated On : Jul 31, 2026|Base Year : 2025|Pages : 120
USD ~9,100+ Million (estimated by forecast horizon)
Compound Annual Growth Rate (CAGR)
6.7%
Forecast Period
2026–2033
Largest Regional Market
Asia-Pacific
Dominant Segment
Outdoor Monitor (Product Type); Government & Academic (End User)
Key Insights & Executive Summary: Air Quality Monitoring Market
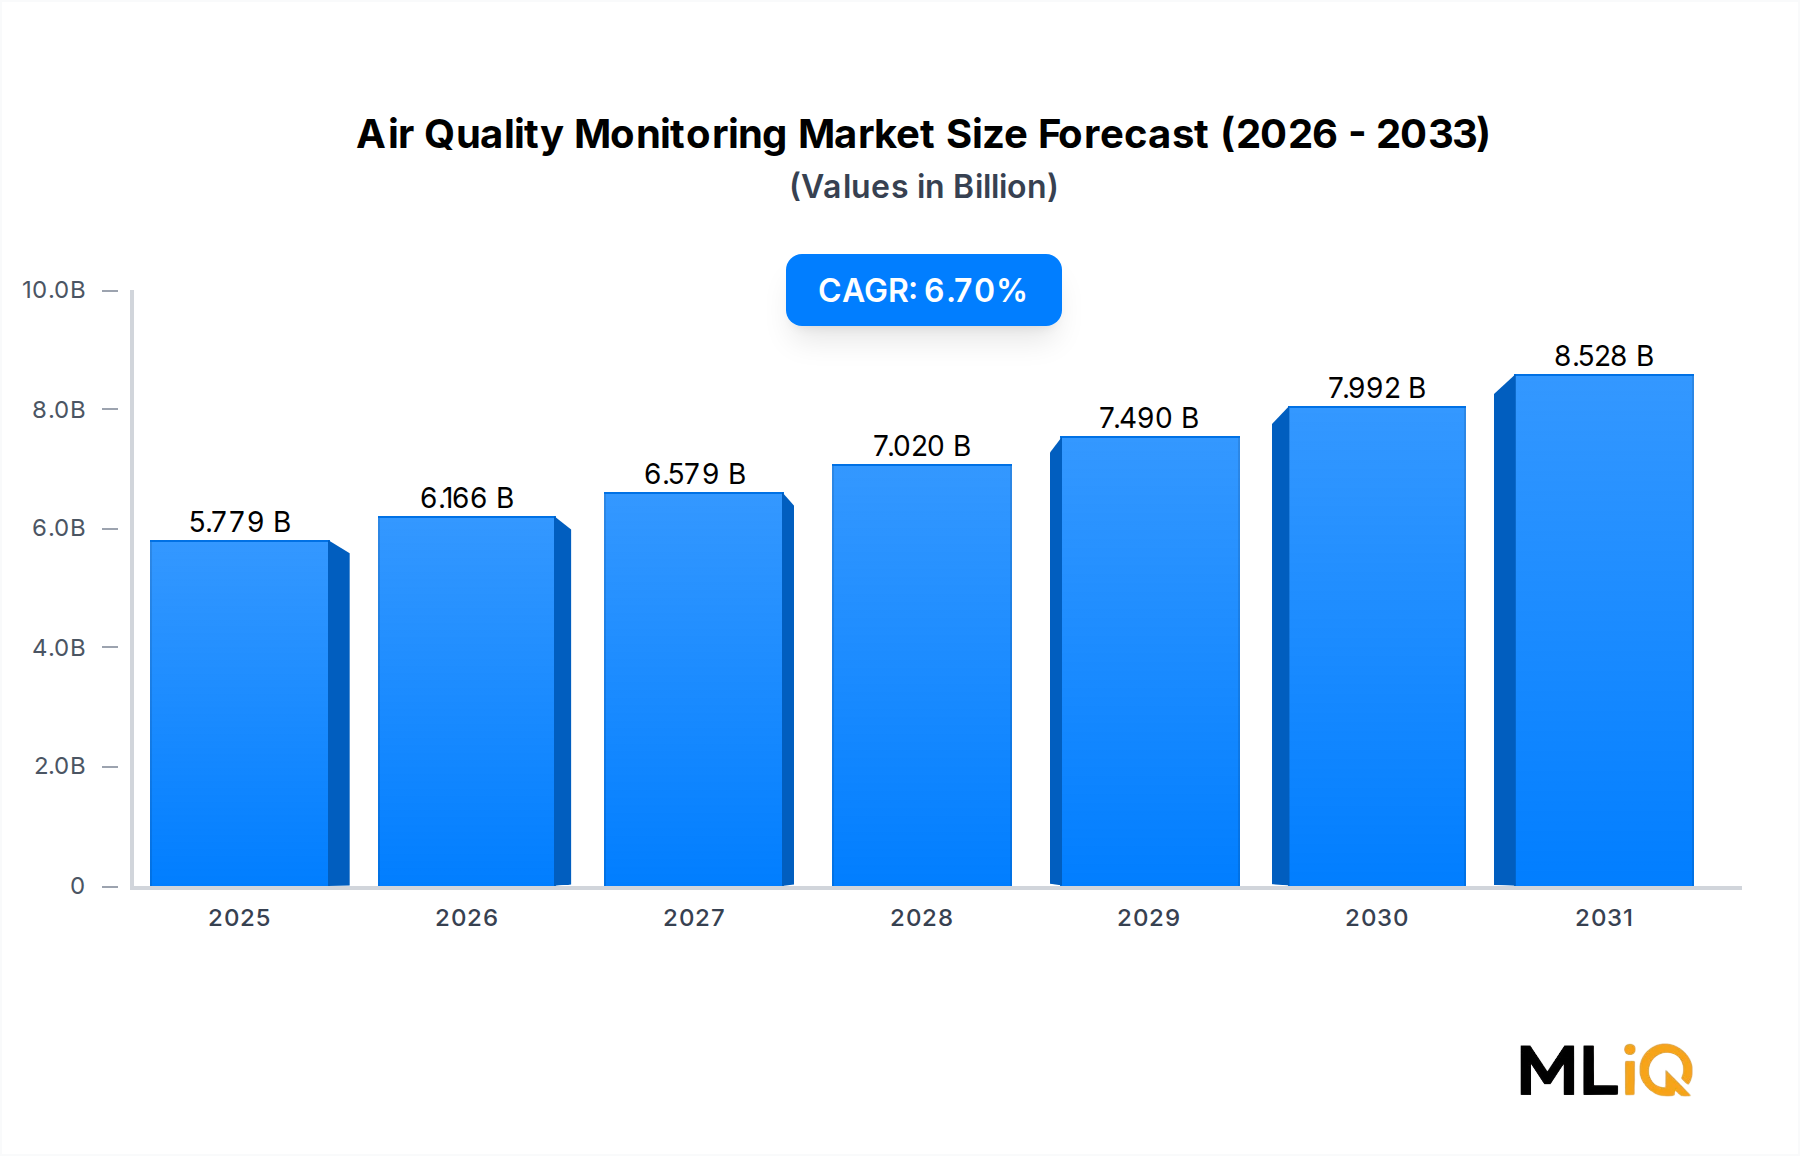
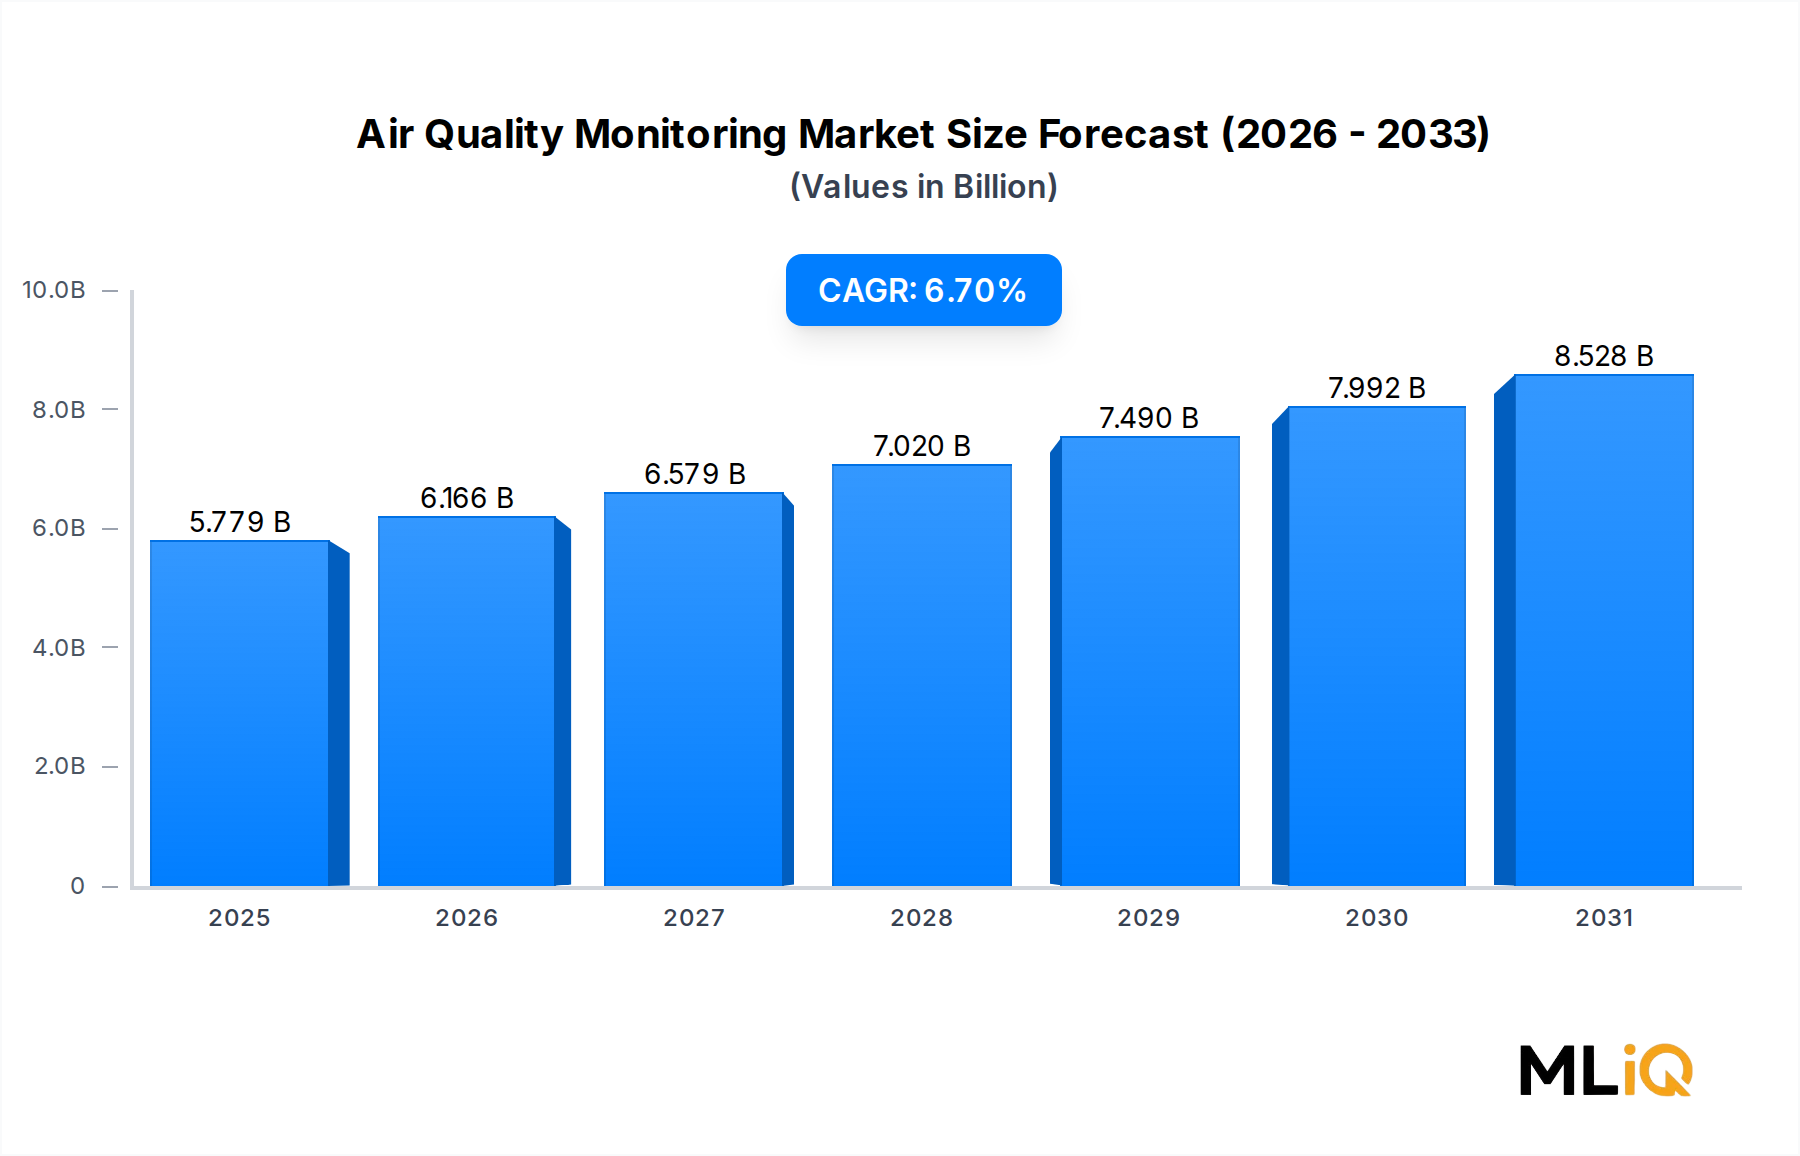
The global Air Quality Monitoring Market is undergoing a structural transformation, moving beyond regulatory compliance into a proactive, data-intelligence-driven paradigm. Valued at USD 5,778.86 million in the base year, the market is projected to expand at a robust CAGR of 6.7%, fueled by converging pressures from urbanization, industrialization, climate accountability mandates, and a growing body of epidemiological evidence linking ambient pollution to chronic disease.
Air Quality Monitoring Market Size (In Billion)
10.0B
8.0B
6.0B
4.0B
2.0B
0
5.779 B
2025
6.166 B
2026
6.579 B
2027
7.020 B
2028
7.490 B
2029
7.992 B
2030
8.528 B
2031
Across construction and manufacturing verticals, air quality monitoring has transitioned from a reactive, endpoint-compliance tool into a real-time operational intelligence asset. Facility operators now embed continuous monitoring networks into production environments to detect volatile organic compounds (VOCs), particulate matter (PM2.5 and PM10), nitrogen oxides (NOx), sulfur dioxide (SO₂), and carbon monoxide (CO) — all critical to workforce safety and regulatory standing.
Macro drivers include the tightening of ambient air quality standards under the U.S. EPA's National Ambient Air Quality Standards (NAAQS), the European Union's revised Ambient Air Quality Directives, and China's Blue Sky Protection Campaign, which collectively mandate denser monitoring infrastructure across both stationary and mobile platforms. The WHO's 2021 revision of global air quality guidelines — introducing significantly stricter PM2.5 thresholds (5 µg/m³ annual mean, down from 10 µg/m³) — has been a particular catalyst, compelling governments and private sector operators to upgrade legacy monitoring infrastructure at scale.
From a strategic standpoint, the market is experiencing powerful tailwinds from the democratization of low-cost sensor technology, the proliferation of Internet of Things (IoT) connectivity, and the integration of AI-powered predictive analytics into monitoring platforms. These innovations are compressing costs, expanding deployment density, and enabling actionable insights that were previously restricted to government reference-grade monitoring stations.
Key strategic growth corridors include Asia-Pacific — particularly China, India, and Southeast Asia — where rapid industrial expansion, urban air quality crises, and government-funded smart city initiatives are driving aggressive monitoring network expansion. North America and Europe remain technology leadership hubs, characterized by high per-unit sensor sophistication and strong enterprise adoption in commercial and industrial real estate segments.
The competitive landscape is consolidating around integrated solutions providers capable of delivering hardware, cloud analytics, and regulatory reporting in unified platforms, creating significant entry barriers for single-product vendors.
Segment Deep-Dive: Government & Academic End-User Dominance in Air Quality Monitoring Market
The Government & Academic end-user segment represents the largest and most foundational revenue contributor within the Air Quality Monitoring Market. This dominance is structural rather than cyclical: national and subnational governments are legally obligated to maintain certified ambient air quality monitoring networks under domestic and international regulatory frameworks, creating non-discretionary, recurring procurement pipelines that span hardware refresh cycles, calibration services, and data management contracts.
Regulatory Mandates as Demand Anchors
Government procurement is primarily driven by compliance imperatives tied to international air quality frameworks. The EU's revised Ambient Air Quality Directive (Directive 2008/50/EC and its ongoing amendments) mandates specific monitoring station density ratios relative to population and pollution-source proximity. Similarly, the U.S. EPA requires states to maintain State and Local Air Monitoring Stations (SLAMS) networks using Federal Reference Methods (FRM) or Federal Equivalent Methods (FEM) instruments. These mandates effectively guarantee baseline procurement volumes irrespective of broader economic cycles, providing vendors with highly predictable revenue.
In Asia-Pacific, China's Ministry of Ecology and Environment has deployed one of the world's most extensive national ambient monitoring networks — exceeding 1,700 state-controlled stations — with ongoing expansion at prefecture and county levels. India's Central Pollution Control Board (CPCB) and state-level boards are similarly scaling their Continuous Ambient Air Quality Monitoring Stations (CAAQMS) under National Clean Air Programme (NCAP) targets.
Academic Research & Environmental Science Sub-Segment
Academic institutions constitute a meaningful sub-segment within this category, procuring reference-grade analyzers, portable monitoring platforms, and sensor networks for atmospheric research, urban heat island studies, and emissions source apportionment projects. University-led research initiatives frequently serve as technology incubators, accelerating the commercialization pathway for next-generation sensor modalities. Institutions such as MIT, ETH Zurich, and IIT Bombay have been active in co-developing low-cost sensor calibration methodologies, contributing to broader market ecosystem development.
Market Share Trajectory & Competitive Dynamics
The Government & Academic segment commands an estimated 35–40% revenue share of the total market, though its share faces modest dilution as commercial and industrial adoption accelerates. Margin pressure is emerging from the increasing penetration of low-cost sensor networks as supplemental data sources alongside reference instruments — a trend that compresses average selling prices (ASPs) for certain equipment categories while expanding total addressable network size.
Key vendors competing intensively for government contracts include Thermo Fisher Scientific, Teledyne Technologies, Horiba Ltd., and Siemens AG — all of whom offer FRM/FEM-certified analyzers capable of meeting the stringent data quality objectives (DQOs) required by regulatory networks. Contract cycles for government monitoring networks typically range from three to seven years, with significant aftermarket revenue from calibration gases, replacement sensors, and software subscriptions.
Indoor vs. Outdoor Monitor Dynamics Within Government Procurement
Within the Product Type segmentation of Indoor Monitor and Outdoor Monitor, government procurement skews overwhelmingly toward outdoor fixed-site reference monitors for ambient network compliance. However, indoor monitoring procurement is growing within the government segment as occupational health agencies, school districts, and public building managers implement IAQ monitoring under post-COVID public health frameworks. The U.S. EPA's Clean Air in Buildings Challenge and the EU's Healthy Workplaces Campaign have been particularly influential in driving indoor monitoring procurement among public sector entities.
Primary Market Drivers & Growth Restraints in Air Quality Monitoring Market
Key Demand Catalysts
Regulatory Stringency and Enforcement Escalation: The single most powerful demand driver is the continuous tightening of permissible exposure limits (PELs) and ambient air quality standards globally. The WHO's 2021 guideline revisions — reducing annual PM2.5 limits from 10 to 5 µg/m³ and PM10 from 20 to 15 µg/m³ — have forced regulatory agencies worldwide to reassess monitoring network adequacy. Nations whose existing networks were calibrated to the prior standards now face mandatory infrastructure upgrades, directly expanding the addressable market for both reference-grade instruments and supplemental sensor networks.
Industrialization and Urban Expansion in Emerging Markets: Rapid industrial output growth across Southeast Asia, South Asia, and Sub-Saharan Africa is generating acute air quality deterioration that is politically and economically untenable. India alone is home to 39 of the world's 50 most polluted cities (IQAir 2023 World Air Quality Report), creating extraordinary governmental pressure to deploy dense monitoring infrastructure. The resulting procurement cycles represent multi-hundred-million-dollar market opportunities for vendors with localized distribution and service capabilities.
Smart City and IoT Integration: The proliferation of smart city programs — with global investment exceeding USD 300 billion annually — embeds air quality monitoring as a core infrastructure layer. The intersection with the Industrial IoT Platform Market has enabled the deployment of low-power, wide-area network (LPWAN)-connected sensor arrays across urban environments at costs unimaginable a decade ago.
Post-Pandemic Indoor Air Quality (IAQ) Awareness: The COVID-19 pandemic permanently elevated public and institutional awareness of indoor air quality, driving demand from commercial real estate, schools, hospitals, and residential developers. This structural behavior change is expected to sustain elevated IAQ monitor procurement for at least the next decade.
Operational Bottlenecks and Restraints
High Capital and Maintenance Costs of Reference-Grade Systems: Certified reference analyzers can cost USD 15,000–USD 80,000 per unit, with annual calibration and maintenance costs adding 15–25% of capital cost annually. This creates significant budget barriers for developing-nation governments and SME industrial operators.
Data Quality and Interoperability Challenges: The proliferation of low-cost sensors has created significant data quality heterogeneity, with accuracy drift and cross-sensitivity to interfering gases undermining regulatory acceptance of sensor-based networks as substitutes for reference instruments. Standardization gaps across sensor data protocols further impede interoperability within integrated monitoring ecosystems.
Supply Chain Vulnerabilities: Dependence on specialized electronic components and rare materials — particularly relevant to the Semiconductor Gas Sensor Market — creates procurement risk and cost volatility, particularly under geopolitically fragmented trade conditions.
Competitive Ecosystem & Key Vendor Profiles: Air Quality Monitoring Market
The competitive landscape of the Air Quality Monitoring Market is characterized by a mix of diversified industrial conglomerates, specialized analytical instrumentation firms, and emerging IoT-native sensor companies. Scale advantages, regulatory certification portfolios, and integrated software capabilities define competitive differentiation.
Emerson Electric Co: A diversified industrial automation leader, Emerson leverages its process measurement and analytical instrumentation portfolio to serve oil & gas, power generation, and industrial manufacturing clients with continuous emissions monitoring systems (CEMS). The company's strength in process automation integration provides a differentiated value proposition in complex industrial environments.
Siemens AG: Siemens competes across both building automation and industrial emissions monitoring segments, integrating air quality data into its broader Desigo CC building management platform. Its focus on smart building ecosystems positions it strongly in the commercial and municipal facility management segment.
General Electric Company (GE): GE's industrial analytics heritage, particularly through its Grid Solutions and Power divisions, supports CEMS deployment at large-scale power generation facilities. The company's digital twin and predictive analytics capabilities add differentiated value to long-term emissions monitoring contracts.
3M Company: 3M applies its advanced materials science expertise to passive air sampling technologies and personal exposure monitoring products, holding a particularly strong position in occupational health monitoring applications intersecting with the Occupational Health and Safety Market.
Thermo Fisher Scientific, Inc: Thermo Fisher is arguably the most comprehensive reference-grade ambient air quality instrument vendor globally, offering FRM/FEM-certified analyzers for SO₂, NO/NOx, CO, O₃, and PM. Its market leadership in government regulatory network procurement is reinforced by extensive global service infrastructure and a dominant calibration standards business.
Merck KGaA: Merck's Life Science division contributes specialty reagents, reference standards, and sorbent materials for air sampling and analytical workflows, supporting laboratory-based air quality analysis rather than direct field monitoring hardware.
TSI, Inc: TSI specializes in precision instruments for aerosol measurement, indoor air quality, and ventilation testing. Its product portfolio is heavily oriented toward research institutions, occupational hygiene, and HVAC commissioning markets.
Testo SE & Co. KGaA: Testo is a leading manufacturer of portable and handheld measurement instruments, with strong penetration in HVAC, food safety, and building inspection segments. Its compact, user-friendly instruments address the growing demand for cost-effective indoor and field monitoring solutions.
Horiba, Ltd: Horiba holds a commanding position in automotive emissions testing and ambient air monitoring analyzers, with particularly strong market presence in Japan, Europe, and increasingly in China's expanding emissions regulatory infrastructure.
Teledyne Technologies Inc: Teledyne's Environmental Instruments division produces a broad range of gas analyzers for ambient monitoring and stack emissions applications, with strong FRM certification credentials that underpin its position in U.S. and European government monitoring networks.
Strategic Milestones & Recent Developments in Air Quality Monitoring Market
The following chronological milestones reflect the most strategically significant developments shaping competitive dynamics and market structure:
March 2023: Thermo Fisher Scientific announced a significant expansion of its environmental monitoring product line, introducing next-generation continuous particulate analyzers with enhanced lower detection limits aligned with the WHO's revised 2021 PM2.5 guidelines, targeting regulatory network upgrades in Europe and North America.
June 2023: Teledyne Technologies completed the integration of its acquired environmental monitoring assets, consolidating its CEMS and ambient air analyzer portfolios under a unified Teledyne Environment brand to streamline enterprise sales and global service operations.
September 2023: Siemens AG announced a strategic partnership with a leading smart city platform provider to embed real-time air quality sensor data streams into municipal digital twin frameworks, targeting tier-1 cities across Europe and the Asia-Pacific region.
January 2024: Horiba, Ltd unveiled its next-generation APNA series ambient air quality monitoring system featuring AI-assisted interference compensation algorithms, specifically designed to meet Japan's Ministry of the Environment updated measurement standards and expanding demand across ASEAN regulatory markets.
April 2024: Emerson Electric Co disclosed a multi-year supply agreement with a major Gulf Cooperation Council (GCC) energy operator for comprehensive CEMS deployment across refinery expansion projects, reinforcing its leadership in the oil & gas end-user segment.
August 2024: 3M Company's Safety & Industrial division launched an expanded portfolio of passive diffusion badges targeting construction and manufacturing facility operators seeking cost-effective personal exposure monitoring solutions compliant with revised OSHA PEL frameworks.
November 2024: TSI, Inc introduced its next-generation AeroTrak+ portable particle counter platform with Bluetooth Low Energy (BLE) connectivity and cloud-native data management, targeting cleanroom qualification and pharmaceutical manufacturing IAQ compliance workflows.
Regional Market Analysis & Growth Corridors for Air Quality Monitoring Market
Asia-Pacific: Dominant and Fastest-Growing Region
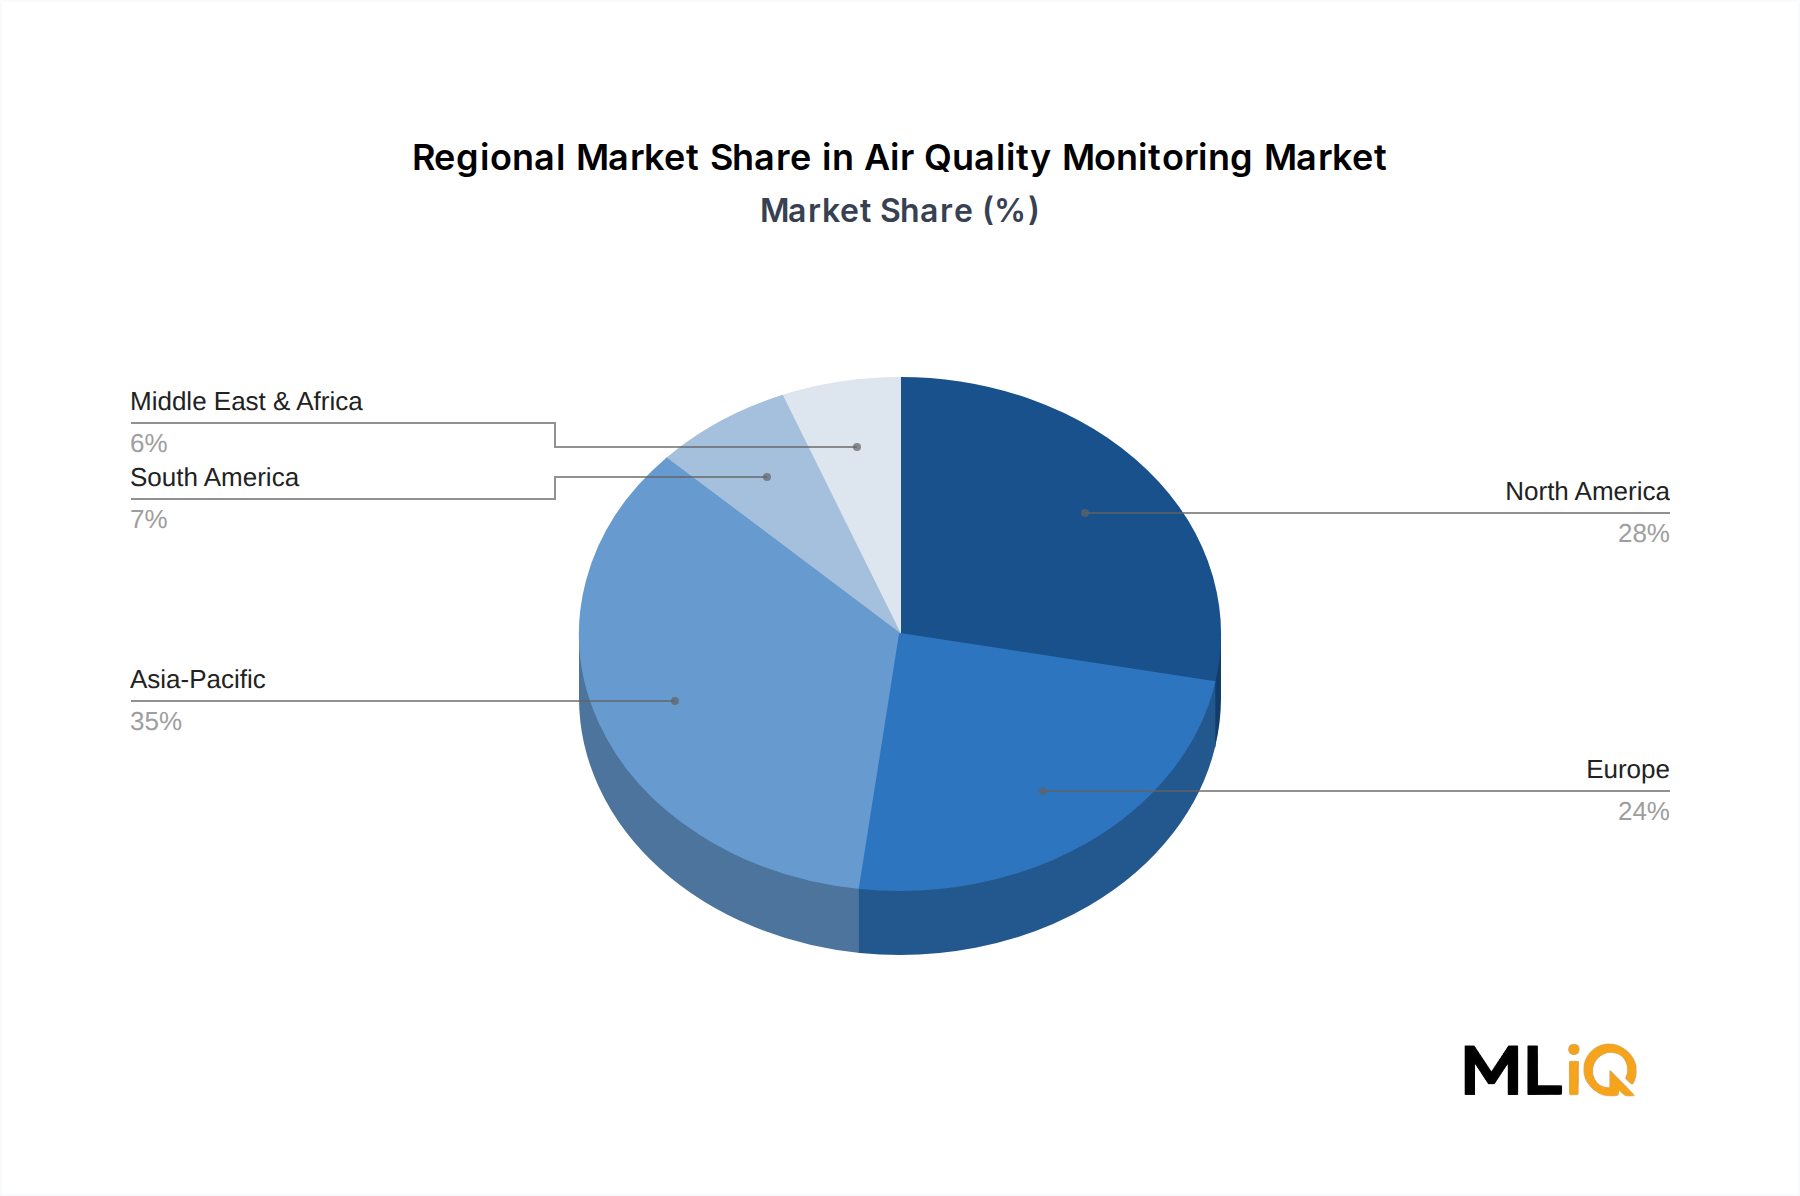
Asia-Pacific commands the largest regional revenue share — estimated at approximately 35–38% of global market value — while simultaneously representing the fastest-growing regional corridor, with a regional CAGR exceeding 8.0%. China remains the single largest national market, driven by the State Council's Blue Sky Protection Campaign, which mandated significant expansion of national ambient monitoring networks and the retirement of legacy coal combustion infrastructure. India represents the highest-growth sub-market, with NCAP funding earmarked for expansion of CAAQMS deployments across 132 non-attainment cities. Japan and South Korea contribute significant demand for high-precision reference instruments aligned with stringent domestic regulatory standards. ASEAN markets — particularly Vietnam, Indonesia, and Thailand — are early-stage but accelerating rapidly as industrialization intensifies regulatory pressure.
North America: Technology Leadership and Regulatory Maturity
North America, led by the United States, represents the most technologically mature market segment, characterized by high ASPs, FRM/FEM certification requirements, and sophisticated enterprise software integration. The EPA's ongoing review of NAAQS PM2.5 standards — proposing to reduce the annual primary standard from 12 to 9 µg/m³ — is expected to trigger substantial monitoring network upgrades across state and local agencies. The U.S. market CAGR is estimated at approximately 5.5–6.0%, with Canada contributing incremental demand through its Air Quality Health Index (AQHI) monitoring expansion programs.
Europe: Regulatory-Driven Modernization
Europe is undergoing a significant monitoring infrastructure modernization cycle driven by the European Green Deal and the revised Ambient Air Quality Directive, which introduces stricter pollutant thresholds and expanded monitoring obligations for ultrafine particles and black carbon. Germany, France, and the United Kingdom are primary demand centers, with Benelux and Nordic markets contributing above-average per-capita monitoring density. The regional CAGR is estimated at 5.8–6.3%, with the regulatory modernization cycle sustaining demand through the early 2030s.
Middle East & Africa and Latin America: Emerging Growth Vectors
The GCC countries are investing heavily in air quality infrastructure to address dust/particulate pollution from construction and petrochemical activities — sectors where the Gas Detection Market and ambient monitoring intersect significantly. South Africa and North Africa represent nascent but growing markets. Latin America — led by Brazil — is expanding monitoring networks under domestic environmental legislation, with Brazil's IBAMA and state-level environmental agencies driving procurement. Combined LAMEA CAGR is estimated at 7.0–7.5%, reflecting a base effect and growing institutional investment.
Technology Innovation & R&D Trajectory in Air Quality Monitoring Market
Low-Cost Electrochemical and Optical Sensor Networks
The most disruptive technological shift in the Air Quality Monitoring Market is the maturation of low-cost electrochemical and optical sensor platforms capable of delivering near-reference-grade accuracy at 1–5% of the cost of traditional analyzers. Advances in MEMS fabrication — central to the Particulate Matter Sensor Market — have enabled the production of miniaturized optical particle counters with detection limits approaching 0.1 µm, previously achievable
Air Quality Monitoring Market Segmentation
1. Product Type
1.1. Indoor Monitor and Outdoor Monitor
2. Pollutant
2.1. Chemical
2.2. Biological
2.3. Physical
3. End User
3.1. Government & Academic
3.2. Oil & Gas
3.3. Power Plants
3.4. Commercial & Residential
3.5. Others
Air Quality Monitoring Market Segmentation By Geography
1. North America
1.1. United States
1.2. Canada
1.3. Mexico
2. South America
2.1. Brazil
2.2. Argentina
2.3. Rest of South America
3. Europe
3.1. United Kingdom
3.2. Germany
3.3. France
3.4. Italy
3.5. Spain
3.6. Russia
3.7. Benelux
3.8. Nordics
3.9. Rest of Europe
4. Middle East & Africa
4.1. Turkey
4.2. Israel
4.3. GCC
4.4. North Africa
4.5. South Africa
4.6. Rest of Middle East & Africa
5. Asia Pacific
5.1. China
5.2. India
5.3. Japan
5.4. South Korea
5.5. ASEAN
5.6. Oceania
5.7. Rest of Asia Pacific
Air Quality Monitoring Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 6.7% from 2020-2034
Segmentation
By Product Type
Indoor Monitor and Outdoor Monitor
By Pollutant
Chemical
Biological
Physical
By End User
Government & Academic
Oil & Gas
Power Plants
Commercial & Residential
Others
By Geography
North America
United States
Canada
Mexico
South America
Brazil
Argentina
Rest of South America
Europe
United Kingdom
Germany
France
Italy
Spain
Russia
Benelux
Nordics
Rest of Europe
Middle East & Africa
Turkey
Israel
GCC
North Africa
South Africa
Rest of Middle East & Africa
Asia Pacific
China
India
Japan
South Korea
ASEAN
Oceania
Rest of Asia Pacific
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. MIQ Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Product Type
5.1.1. Indoor Monitor and Outdoor Monitor
5.2. Market Analysis, Insights and Forecast - by Pollutant
5.2.1. Chemical
5.2.2. Biological
5.2.3. Physical
5.3. Market Analysis, Insights and Forecast - by End User
5.3.1. Government & Academic
5.3.2. Oil & Gas
5.3.3. Power Plants
5.3.4. Commercial & Residential
5.3.5. Others
5.4. Market Analysis, Insights and Forecast - by Region
5.4.1. North America
5.4.2. South America
5.4.3. Europe
5.4.4. Middle East & Africa
5.4.5. Asia Pacific
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Product Type
6.1.1. Indoor Monitor and Outdoor Monitor
6.2. Market Analysis, Insights and Forecast - by Pollutant
6.2.1. Chemical
6.2.2. Biological
6.2.3. Physical
6.3. Market Analysis, Insights and Forecast - by End User
6.3.1. Government & Academic
6.3.2. Oil & Gas
6.3.3. Power Plants
6.3.4. Commercial & Residential
6.3.5. Others
7. South America Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Product Type
7.1.1. Indoor Monitor and Outdoor Monitor
7.2. Market Analysis, Insights and Forecast - by Pollutant
7.2.1. Chemical
7.2.2. Biological
7.2.3. Physical
7.3. Market Analysis, Insights and Forecast - by End User
7.3.1. Government & Academic
7.3.2. Oil & Gas
7.3.3. Power Plants
7.3.4. Commercial & Residential
7.3.5. Others
8. Europe Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Product Type
8.1.1. Indoor Monitor and Outdoor Monitor
8.2. Market Analysis, Insights and Forecast - by Pollutant
8.2.1. Chemical
8.2.2. Biological
8.2.3. Physical
8.3. Market Analysis, Insights and Forecast - by End User
8.3.1. Government & Academic
8.3.2. Oil & Gas
8.3.3. Power Plants
8.3.4. Commercial & Residential
8.3.5. Others
9. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Product Type
9.1.1. Indoor Monitor and Outdoor Monitor
9.2. Market Analysis, Insights and Forecast - by Pollutant
9.2.1. Chemical
9.2.2. Biological
9.2.3. Physical
9.3. Market Analysis, Insights and Forecast - by End User
9.3.1. Government & Academic
9.3.2. Oil & Gas
9.3.3. Power Plants
9.3.4. Commercial & Residential
9.3.5. Others
10. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Product Type
10.1.1. Indoor Monitor and Outdoor Monitor
10.2. Market Analysis, Insights and Forecast - by Pollutant
10.2.1. Chemical
10.2.2. Biological
10.2.3. Physical
10.3. Market Analysis, Insights and Forecast - by End User
10.3.1. Government & Academic
10.3.2. Oil & Gas
10.3.3. Power Plants
10.3.4. Commercial & Residential
10.3.5. Others
11. Competitive Analysis
11.1. Company Profiles
11.1.1. Emerson Electric Co
11.1.1.1. Company Overview
11.1.1.2. Products
11.1.1.3. Company Financials
11.1.1.4. SWOT Analysis
11.1.2. Siemens AG
11.1.2.1. Company Overview
11.1.2.2. Products
11.1.2.3. Company Financials
11.1.2.4. SWOT Analysis
11.1.3. General Electric Company (GE)
11.1.3.1. Company Overview
11.1.3.2. Products
11.1.3.3. Company Financials
11.1.3.4. SWOT Analysis
11.1.4. 3M Company
11.1.4.1. Company Overview
11.1.4.2. Products
11.1.4.3. Company Financials
11.1.4.4. SWOT Analysis
11.1.5. Thermo Fisher Scientific Inc
11.1.5.1. Company Overview
11.1.5.2. Products
11.1.5.3. Company Financials
11.1.5.4. SWOT Analysis
11.1.6. Merck KGaA
11.1.6.1. Company Overview
11.1.6.2. Products
11.1.6.3. Company Financials
11.1.6.4. SWOT Analysis
11.1.7. TSI Inc
11.1.7.1. Company Overview
11.1.7.2. Products
11.1.7.3. Company Financials
11.1.7.4. SWOT Analysis
11.1.8. Test SE & Co. KGaA
11.1.8.1. Company Overview
11.1.8.2. Products
11.1.8.3. Company Financials
11.1.8.4. SWOT Analysis
11.1.9. Horiba Ltd
11.1.9.1. Company Overview
11.1.9.2. Products
11.1.9.3. Company Financials
11.1.9.4. SWOT Analysis
11.1.10. Teledyne Technologies Inc
11.1.10.1. Company Overview
11.1.10.2. Products
11.1.10.3. Company Financials
11.1.10.4. SWOT Analysis
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Air Quality Monitoring Market Revenue Breakdown (million, %) by Region 2026 & 2034
Figure 2: North America Air Quality Monitoring Market Revenue (million), by Product Type 2026 & 2034
Figure 3: North America Air Quality Monitoring Market Revenue Share (%), by Product Type 2026 & 2034
Figure 4: North America Air Quality Monitoring Market Revenue (million), by Pollutant 2026 & 2034
Figure 5: North America Air Quality Monitoring Market Revenue Share (%), by Pollutant 2026 & 2034
Figure 6: North America Air Quality Monitoring Market Revenue (million), by End User 2026 & 2034
Figure 7: North America Air Quality Monitoring Market Revenue Share (%), by End User 2026 & 2034
Figure 8: North America Air Quality Monitoring Market Revenue (million), by Country 2026 & 2034
Figure 9: North America Air Quality Monitoring Market Revenue Share (%), by Country 2026 & 2034
Figure 10: South America Air Quality Monitoring Market Revenue (million), by Product Type 2026 & 2034
Figure 11: South America Air Quality Monitoring Market Revenue Share (%), by Product Type 2026 & 2034
Figure 12: South America Air Quality Monitoring Market Revenue (million), by Pollutant 2026 & 2034
Figure 13: South America Air Quality Monitoring Market Revenue Share (%), by Pollutant 2026 & 2034
Figure 14: South America Air Quality Monitoring Market Revenue (million), by End User 2026 & 2034
Figure 15: South America Air Quality Monitoring Market Revenue Share (%), by End User 2026 & 2034
Figure 16: South America Air Quality Monitoring Market Revenue (million), by Country 2026 & 2034
Figure 17: South America Air Quality Monitoring Market Revenue Share (%), by Country 2026 & 2034
Figure 18: Europe Air Quality Monitoring Market Revenue (million), by Product Type 2026 & 2034
Figure 19: Europe Air Quality Monitoring Market Revenue Share (%), by Product Type 2026 & 2034
Figure 20: Europe Air Quality Monitoring Market Revenue (million), by Pollutant 2026 & 2034
Figure 21: Europe Air Quality Monitoring Market Revenue Share (%), by Pollutant 2026 & 2034
Figure 22: Europe Air Quality Monitoring Market Revenue (million), by End User 2026 & 2034
Figure 23: Europe Air Quality Monitoring Market Revenue Share (%), by End User 2026 & 2034
Figure 24: Europe Air Quality Monitoring Market Revenue (million), by Country 2026 & 2034
Figure 25: Europe Air Quality Monitoring Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Middle East & Africa Air Quality Monitoring Market Revenue (million), by Product Type 2026 & 2034
Figure 27: Middle East & Africa Air Quality Monitoring Market Revenue Share (%), by Product Type 2026 & 2034
Figure 28: Middle East & Africa Air Quality Monitoring Market Revenue (million), by Pollutant 2026 & 2034
Figure 29: Middle East & Africa Air Quality Monitoring Market Revenue Share (%), by Pollutant 2026 & 2034
Figure 30: Middle East & Africa Air Quality Monitoring Market Revenue (million), by End User 2026 & 2034
Figure 31: Middle East & Africa Air Quality Monitoring Market Revenue Share (%), by End User 2026 & 2034
Figure 32: Middle East & Africa Air Quality Monitoring Market Revenue (million), by Country 2026 & 2034
Figure 33: Middle East & Africa Air Quality Monitoring Market Revenue Share (%), by Country 2026 & 2034
Figure 34: Asia Pacific Air Quality Monitoring Market Revenue (million), by Product Type 2026 & 2034
Figure 35: Asia Pacific Air Quality Monitoring Market Revenue Share (%), by Product Type 2026 & 2034
Figure 36: Asia Pacific Air Quality Monitoring Market Revenue (million), by Pollutant 2026 & 2034
Figure 37: Asia Pacific Air Quality Monitoring Market Revenue Share (%), by Pollutant 2026 & 2034
Figure 38: Asia Pacific Air Quality Monitoring Market Revenue (million), by End User 2026 & 2034
Figure 39: Asia Pacific Air Quality Monitoring Market Revenue Share (%), by End User 2026 & 2034
Figure 40: Asia Pacific Air Quality Monitoring Market Revenue (million), by Country 2026 & 2034
Figure 41: Asia Pacific Air Quality Monitoring Market Revenue Share (%), by Country 2026 & 2034
List of Tables
Table 1: Air Quality Monitoring Market Revenue million Forecast, by Product Type 2020 & 2034
Table 2: Air Quality Monitoring Market Revenue million Forecast, by Pollutant 2020 & 2034
Table 3: Air Quality Monitoring Market Revenue million Forecast, by End User 2020 & 2034
Table 4: Air Quality Monitoring Market Revenue million Forecast, by Region 2020 & 2034
Table 5: North America Air Quality Monitoring Market Revenue million Forecast, by Product Type 2020 & 2034
Table 6: North America Air Quality Monitoring Market Revenue million Forecast, by Pollutant 2020 & 2034
Table 7: North America Air Quality Monitoring Market Revenue million Forecast, by End User 2020 & 2034
Table 8: North America Air Quality Monitoring Market Revenue million Forecast, by Country 2020 & 2034
Table 9: United States Air Quality Monitoring Market Revenue (million) Forecast, by Application 2020 & 2034
Table 10: Canada Air Quality Monitoring Market Revenue (million) Forecast, by Application 2020 & 2034
Table 11: Mexico Air Quality Monitoring Market Revenue (million) Forecast, by Application 2020 & 2034
Table 12: South America Air Quality Monitoring Market Revenue million Forecast, by Product Type 2020 & 2034
Table 13: South America Air Quality Monitoring Market Revenue million Forecast, by Pollutant 2020 & 2034
Table 14: South America Air Quality Monitoring Market Revenue million Forecast, by End User 2020 & 2034
Table 15: South America Air Quality Monitoring Market Revenue million Forecast, by Country 2020 & 2034
Table 16: Brazil Air Quality Monitoring Market Revenue (million) Forecast, by Application 2020 & 2034
Table 17: Argentina Air Quality Monitoring Market Revenue (million) Forecast, by Application 2020 & 2034
Table 18: Rest of South America Air Quality Monitoring Market Revenue (million) Forecast, by Application 2020 & 2034
Table 19: Europe Air Quality Monitoring Market Revenue million Forecast, by Product Type 2020 & 2034
Table 20: Europe Air Quality Monitoring Market Revenue million Forecast, by Pollutant 2020 & 2034
Table 21: Europe Air Quality Monitoring Market Revenue million Forecast, by End User 2020 & 2034
Table 22: Europe Air Quality Monitoring Market Revenue million Forecast, by Country 2020 & 2034
Table 23: United Kingdom Air Quality Monitoring Market Revenue (million) Forecast, by Application 2020 & 2034
Table 24: Germany Air Quality Monitoring Market Revenue (million) Forecast, by Application 2020 & 2034
Table 25: France Air Quality Monitoring Market Revenue (million) Forecast, by Application 2020 & 2034
Table 26: Italy Air Quality Monitoring Market Revenue (million) Forecast, by Application 2020 & 2034
Table 27: Spain Air Quality Monitoring Market Revenue (million) Forecast, by Application 2020 & 2034
Table 28: Russia Air Quality Monitoring Market Revenue (million) Forecast, by Application 2020 & 2034
Table 29: Benelux Air Quality Monitoring Market Revenue (million) Forecast, by Application 2020 & 2034
Table 30: Nordics Air Quality Monitoring Market Revenue (million) Forecast, by Application 2020 & 2034
Table 31: Rest of Europe Air Quality Monitoring Market Revenue (million) Forecast, by Application 2020 & 2034
Table 32: Middle East & Africa Air Quality Monitoring Market Revenue million Forecast, by Product Type 2020 & 2034
Table 33: Middle East & Africa Air Quality Monitoring Market Revenue million Forecast, by Pollutant 2020 & 2034
Table 34: Middle East & Africa Air Quality Monitoring Market Revenue million Forecast, by End User 2020 & 2034
Table 35: Middle East & Africa Air Quality Monitoring Market Revenue million Forecast, by Country 2020 & 2034
Table 36: Turkey Air Quality Monitoring Market Revenue (million) Forecast, by Application 2020 & 2034
Table 37: Israel Air Quality Monitoring Market Revenue (million) Forecast, by Application 2020 & 2034
Table 38: GCC Air Quality Monitoring Market Revenue (million) Forecast, by Application 2020 & 2034
Table 39: North Africa Air Quality Monitoring Market Revenue (million) Forecast, by Application 2020 & 2034
Table 40: South Africa Air Quality Monitoring Market Revenue (million) Forecast, by Application 2020 & 2034
Table 41: Rest of Middle East & Africa Air Quality Monitoring Market Revenue (million) Forecast, by Application 2020 & 2034
Table 42: Asia Pacific Air Quality Monitoring Market Revenue million Forecast, by Product Type 2020 & 2034
Table 43: Asia Pacific Air Quality Monitoring Market Revenue million Forecast, by Pollutant 2020 & 2034
Table 44: Asia Pacific Air Quality Monitoring Market Revenue million Forecast, by End User 2020 & 2034
Table 45: Asia Pacific Air Quality Monitoring Market Revenue million Forecast, by Country 2020 & 2034
Table 46: China Air Quality Monitoring Market Revenue (million) Forecast, by Application 2020 & 2034
Table 47: India Air Quality Monitoring Market Revenue (million) Forecast, by Application 2020 & 2034
Table 48: Japan Air Quality Monitoring Market Revenue (million) Forecast, by Application 2020 & 2034
Table 49: South Korea Air Quality Monitoring Market Revenue (million) Forecast, by Application 2020 & 2034
Table 50: ASEAN Air Quality Monitoring Market Revenue (million) Forecast, by Application 2020 & 2034
Table 51: Oceania Air Quality Monitoring Market Revenue (million) Forecast, by Application 2020 & 2034
Table 52: Rest of Asia Pacific Air Quality Monitoring Market Revenue (million) Forecast, by Application 2020 & 2034
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
The foundation of this report rests on a rigorous primary research framework, accounting for 70–80% of the total research effort. This approach ensures that market estimations, competitive dynamics, and regional demand patterns are grounded in first-hand intelligence sourced directly from key participants across the air quality monitoring value chain.
Company Types Engaged Across the Value Chain:
Sensor & Transducer Manufacturers – Original component producers specializing in electrochemical, photoionization detection (PID), optical particle counters, and metal oxide semiconductor (MOS) sensors used in air quality monitors.
Air Quality Monitor OEMs & System Integrators – Firms that design, assemble, and commercialize complete indoor and outdoor monitoring units (e.g., fixed-site analyzers, portable handheld monitors, and IoT-enabled continuous emission monitoring systems).
Environmental Data Analytics & Software Platform Providers – Companies offering cloud-based dashboards, AI-driven pollutant forecasting engines, and regulatory compliance reporting tools integrated with monitoring hardware.
Calibration, Maintenance & Third-Party Testing Service Providers – Specialized firms offering NIST-traceable calibration services, field maintenance contracts, and independent certification testing for deployed monitoring networks.
End-User Procurement Organizations – Government environmental agencies, industrial plant operators (oil & gas, power utilities), commercial building management companies, and academic research institutions that specify, procure, and operate monitoring systems.
Key Stakeholder Interviews Conducted:
Environmental Compliance & Health, Safety, and Environment (HSE) Managers at oil & gas upstream/downstream facilities and power generation plants, responsible for continuous emission monitoring system (CEMS) procurement and regulatory adherence.
Air Quality Program Directors & Atmospheric Scientists within national and regional environmental protection agencies and academic research departments, overseeing network design and pollutant threshold policy.
IoT Product Development Engineers & Sensor Technology R&D Leads at monitor OEMs, providing technical insight into sensor miniaturization, multi-pollutant detection capabilities, and next-generation product roadmaps.
Facilities & Building Automation Managers at commercial real estate and residential property management firms, offering demand-side perspective on indoor air quality (IAQ) monitoring adoption driven by occupant wellness mandates and green building certifications.
Primary data was gathered through structured questionnaires, in-depth telephone interviews, and virtual focus groups conducted across North America, Europe, Asia Pacific, Middle East & Africa, and South America. Responses were normalized for regional purchasing power parity and regulatory context before integration into the demand model.
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Environmental Compliance & HSE Managers
30%
Air Quality Program Directors & Atmospheric Scientists
25%
IoT Product Development Engineers & Sensor R&D Leads
22%
Facilities & Building Automation Managers
23%
Industry Ecosystem Breakdown
Company Type
Representation (%)
Sensor & Transducer Manufacturers
22%
Air Quality Monitor OEMs & System Integrators
30%
Environmental Data Analytics & Software Platform Providers
18%
Calibration, Maintenance & Third-Party Testing Service Providers
12%
End-User Procurement Organizations
18%
Secondary Research & Industry Benchmarking
Secondary research contributes the remaining 20–30% of the research framework, providing historical baselines, regulatory context, technology benchmarking, and macroeconomic overlays that validate and contextualize primary findings.
Financial & Business Intelligence Databases Leveraged:
Bloomberg Terminal – For publicly traded air quality monitoring company financials, M&A deal flows, and equity analyst coverage.
Factiva (Dow Jones) – For global news intelligence, product launch announcements, and regulatory policy tracking across all covered geographies.
Hoovers (Dun & Bradstreet) – For private company profiling, revenue estimation, and competitive landscape mapping of regional sensor manufacturers.
PitchBook – For venture capital investment tracking into air quality tech startups, strategic partnership analysis, and early-stage technology pipeline assessment.
Authoritative Government, Regulatory & Trade Association Sources:
European Environment Agency (EEA) – EU Air Quality Directive compliance datasets, AirBase monitoring station inventories, and member-state pollutant exposure reports.
Air & Waste Management Association (AWMA) – Industry association publications, technical conference proceedings, and professional membership data informing competitive and technology benchmarking.
Secondary sources were further supplemented with national census data, trade flow statistics from UN Comtrade, energy sector emission inventories, and urban development indices to model regional demand heterogeneity across 40+ countries covered in this report.
Demand Modeling & Market Estimation
Market sizing was executed using a dual-methodology approach combining top-down and bottom-up modeling, with multi-level data triangulation applied at each stage to minimize estimation error.
Top-Down Approach: Global environmental monitoring equipment expenditure data, government air quality infrastructure budgets, and industrial emission compliance capex allocations were disaggregated by product type (indoor vs. outdoor monitors), pollutant category (chemical, biological, physical), and end-user vertical using allocation coefficients derived from primary interviews and regulatory program data.
Bottom-Up Approach: Market size was independently reconstructed from the ground up using the following key metrics and estimation variables:
Installed Base of Monitoring Stations × Average Unit Selling Price (ASP) by Product Tier – Derived from EPA AQS, EEA AirBase, and equivalent national network inventories, segmented by fixed-site reference analyzers, low-cost sensor nodes, and portable/personal monitors, with ASP bands validated through OEM interviews and distributor channel checks.
Annual Regulatory Compliance Capex per Industrial Facility – Estimated from mandatory CEMS installation requirements under emission trading schemes (EU ETS), U.S. Clean Air Act Title V permits, and equivalent frameworks in China (GB standards) and India (CPCB mandates), multiplied by the number of regulated facilities in each jurisdiction.
Per-Capita Indoor Air Quality Monitoring Adoption Rate × Addressable Commercial & Residential Floor Area – Calculated using smart building penetration rates, WELL Building Standard and LEED certification growth trajectories, and urban population density indices across key metros in each region.
R&D Expenditure as a Percentage of Revenue for Sensor Technology Innovation – Used as a proxy variable to project technology refresh cycles, product obsolescence rates, and replacement demand cadence across OEM cohorts, cross-referenced with PitchBook funding rounds and Bloomberg R&D disclosures.
Bottom-up and top-down outputs were reconciled through three-stage triangulation: (1) cross-validation against aggregate revenue disclosures of publicly listed peers, (2) sanity-checking against macroeconomic air pollution control spending as a share of GDP in key markets, and (3) expert panel review with primary research respondents for directional alignment.
Data Accuracy & Quality Check
All data integrated into this report undergoes a multi-checkpoint quality assurance process, targeting a guaranteed estimated data accuracy level of 85–90%.
Source Hierarchy Validation: Every data point is classified by source tier (Tier 1: primary interview; Tier 2: official government/regulatory database; Tier 3: financial database; Tier 4: trade press). Tier 3 and 4 data points are only accepted when corroborated by at least one higher-tier source.
Inter-Analyst Peer Review: Independent analyst teams working on separate regional modules (North America, Europe, Asia Pacific, MEA, South America) cross-review segment totals to identify inconsistencies before consolidation into the global model.
Outlier Detection & Normalization: Statistical outlier screening is applied to all primary survey responses. Responses deviating beyond ±2 standard deviations from the segment mean are flagged, re-interviewed where possible, or excluded with documented rationale.
Continuous Data Refresh: This report is maintained on a rolling update basis and reflects data current as of the date of purchase. Regional regulatory changes (e.g., new WHO air quality guideline adoption, EU Air Quality Directive revisions, China's 14th Five-Year Plan emission targets), product launches, and M&A events are incorporated on an ongoing basis to ensure subscribers receive the most current market intelligence available.
Currency & Inflation Normalization: All revenue figures are reported in constant USD unless otherwise stated, with historical data adjusted using World Bank GDP deflators and regional CPI indices to ensure cross-period and cross-geography comparability.
Frequently Asked Questions
1. What are the key product types and pollutant segments in the air quality monitoring market?
The market segments by product type into indoor and outdoor monitors, with outdoor units dominating due to industrial and municipal deployment requirements. On the pollutant side, chemical monitoring commands the largest sub-segment share, followed by biological and physical pollutant detection. End-user demand across government, oil & gas, and power plants reinforces demand for multi-pollutant capable systems.
2. How active is venture capital and institutional investment in the air quality monitoring space?
Established players such as Thermo Fisher Scientific and Teledyne Technologies have driven consolidation through acquisitions, signaling strong institutional confidence in sensor and analytics sub-segments. The market's $5,778.86 million valuation and 6.7% CAGR make it an attractive target for industrial tech funds focused on ESG-linked infrastructure. Early-stage funding has also flowed into IoT-integrated portable monitor startups serving commercial and residential end users.
3. Which region leads the air quality monitoring market and why?
Asia-Pacific holds the largest regional share at approximately 35%, driven by China and India's rapid industrialization, severe urban air pollution, and government-mandated monitoring network expansions. China's national ambient air quality standards and India's NCAP (National Clean Air Programme) are direct procurement catalysts. Japan and South Korea add high-precision industrial monitoring demand layered on top of regulatory baseline requirements.
4. How do export-import dynamics shape international trade flows in air quality monitoring equipment?
North America and Europe are net exporters of high-precision monitoring instruments, with companies like Emerson Electric and Siemens AG supplying government and industrial buyers across Asia-Pacific and the Middle East. Asia-Pacific nations import significant volumes of reference-grade analyzers while increasingly exporting lower-cost portable and IoT-enabled units. Trade flows are influenced by WTO environmental goods agreements and bilateral customs classifications for gas analyzers under HS code 9027.
5. Which end-user industries generate the most downstream demand for air quality monitoring systems?
Government and academic institutions represent the largest end-user segment, procuring continuous ambient monitoring stations for national air quality networks. Oil & gas and power plant operators form the second major demand cluster, requiring stack emissions and fence-line monitoring to meet permit conditions. Commercial and residential adoption is the fastest-growing sub-segment, fueled by sub-$500 consumer-grade sensors and smart building integration.
6. How does the regulatory environment influence compliance costs and procurement decisions in this market?
Stringent regulations such as the U.S. Clean Air Act, EU Air Quality Directive 2008/50/EC, and China's GB 3095-2012 standard mandate continuous emissions monitoring, directly driving equipment procurement cycles. Non-compliance penalties can reach millions of dollars per violation, making certified reference monitors from suppliers like Horiba Ltd and TSI Inc essential capital expenditures rather than discretionary purchases. Regulatory revisions—such as the EPA's updated PM2.5 NAAQS finalized in 2024—consistently expand the addressable market by requiring upgraded sensor networks.