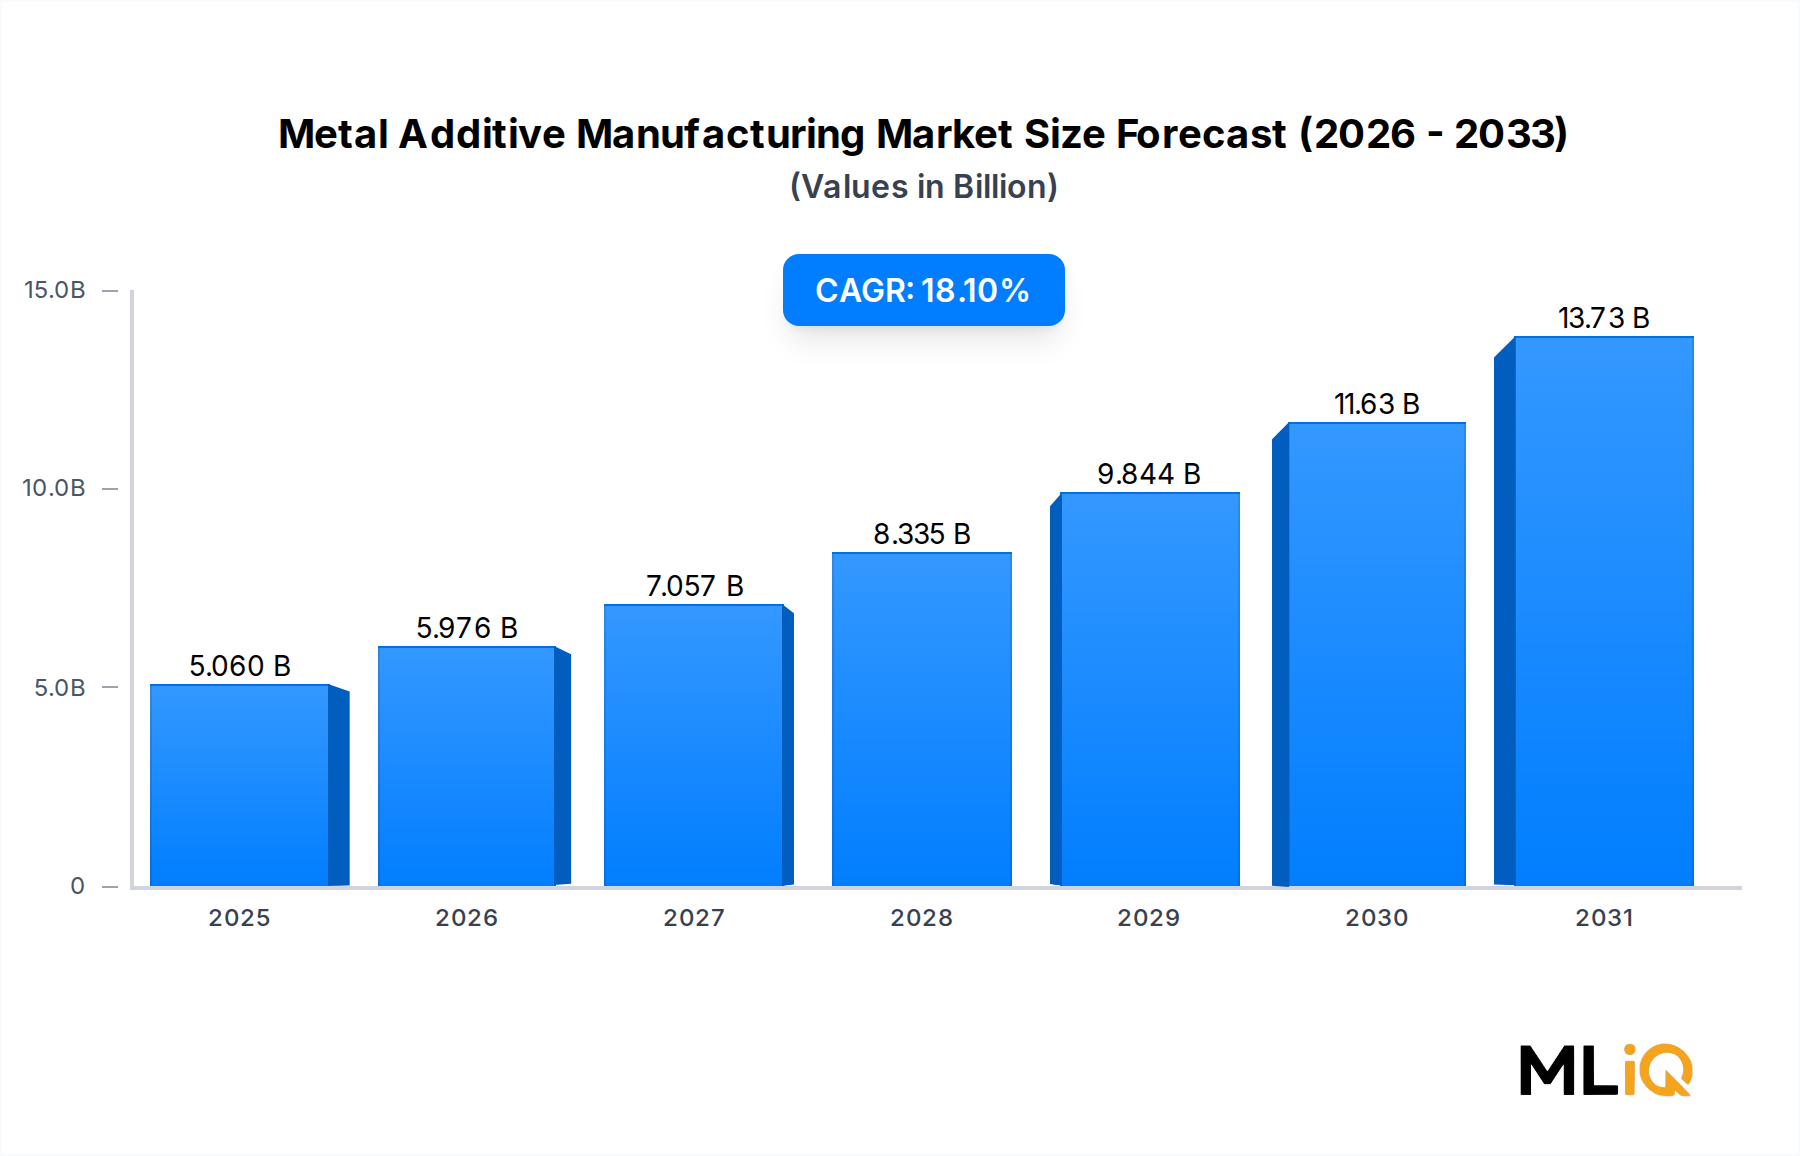
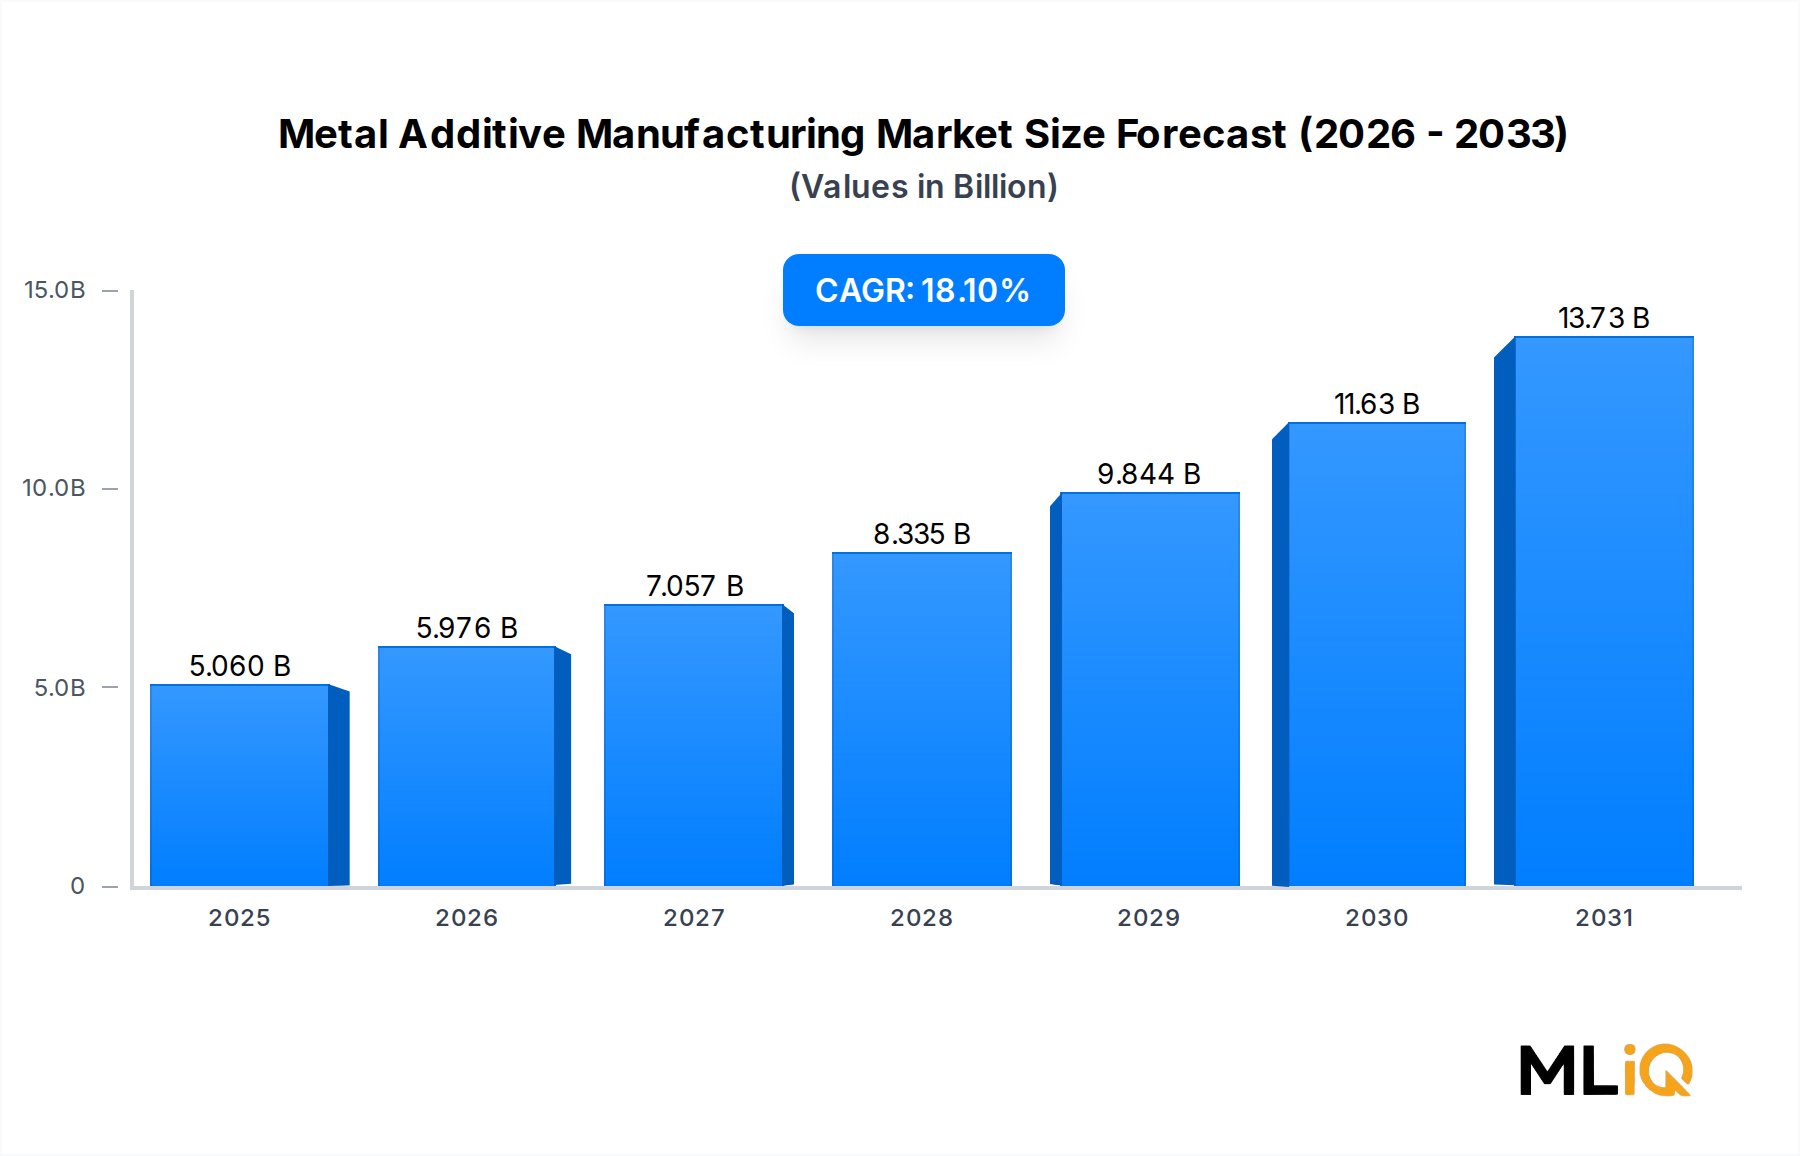
The global Metal Additive Manufacturing Market is entering a high-conviction growth phase, underpinned by a CAGR of 18.1% through 2033. Starting from a base valuation of USD 5.06 billion, the market is projected to approach approximately USD 22.5 billion by the end of the forecast period—a trajectory that reflects a fundamental transition from prototyping novelty to mission-critical production infrastructure across aerospace, automotive, healthcare, and defense verticals.
Several macro-structural forces are converging to accelerate this expansion. First, supply chain localization imperatives—intensified by geopolitical fragmentation and post-pandemic resilience mandates—are pushing manufacturers to invest in on-demand, near-net-shape metal part production capabilities. Second, the exponential rise in geometric design complexity requirements, particularly driven by topology optimization in aerospace and medical implant sectors, is rendering traditional subtractive manufacturing economically non-viable for an increasing share of components. Third, material science breakthroughs in high-performance alloys—nickel superalloys, titanium-aluminum composites, and refractory metals—are expanding the viable application envelope of metal additive systems.
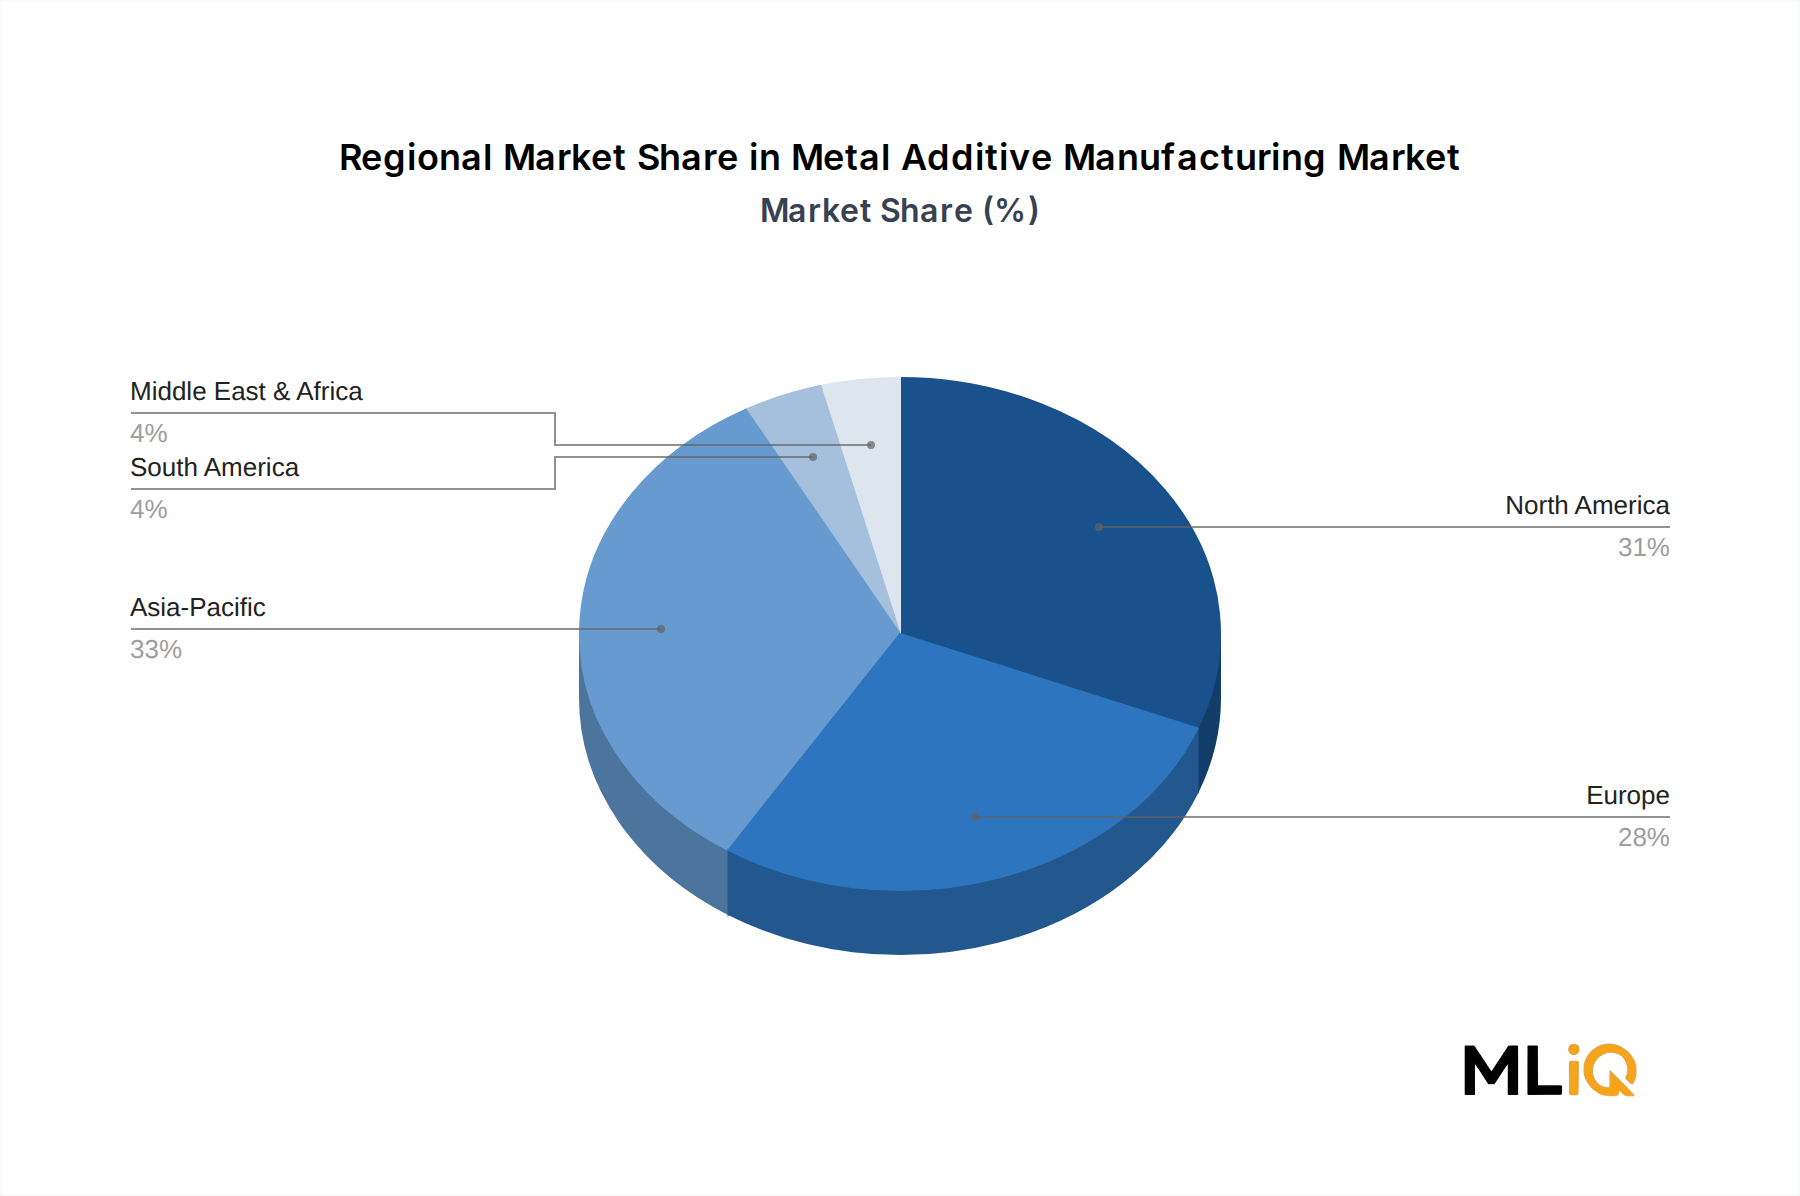
North America retains pole position as the most mature and highest-revenue market, driven by sustained Department of Defense investment, robust aerospace OEM adoption, and the concentration of leading technology developers. Europe, particularly Germany and the United Kingdom, is the epicenter of precision engineering adoption and regulatory standardization for additive processes. Asia-Pacific, led by China and South Korea, is the fastest-growing region, fueled by state-sponsored manufacturing modernization programs and a rapidly maturing domestic vendor ecosystem.
On the competitive front, the market is populated by a mix of vertically integrated industrial conglomerates (GE Additive, DMG Mori, Trumpf) and specialized platform developers (EOS GmbH, SLM Solutions, Renishaw plc.). The intensifying convergence of hardware, software, and materials-as-a-service models is reshaping competitive moats and creating new margin structures.
Strategically, the market's growth trajectory is not without headwinds. High capital expenditure for industrial-grade systems, the scarcity of qualified metallurgical operators, and post-process finishing requirements continue to constrain faster adoption curves among mid-tier manufacturers. Nonetheless, the directional vector remains strongly positive, with total addressable market expansion driven by both broadening application reach and declining per-part production costs as machine throughput and build rates improve across all major process categories.