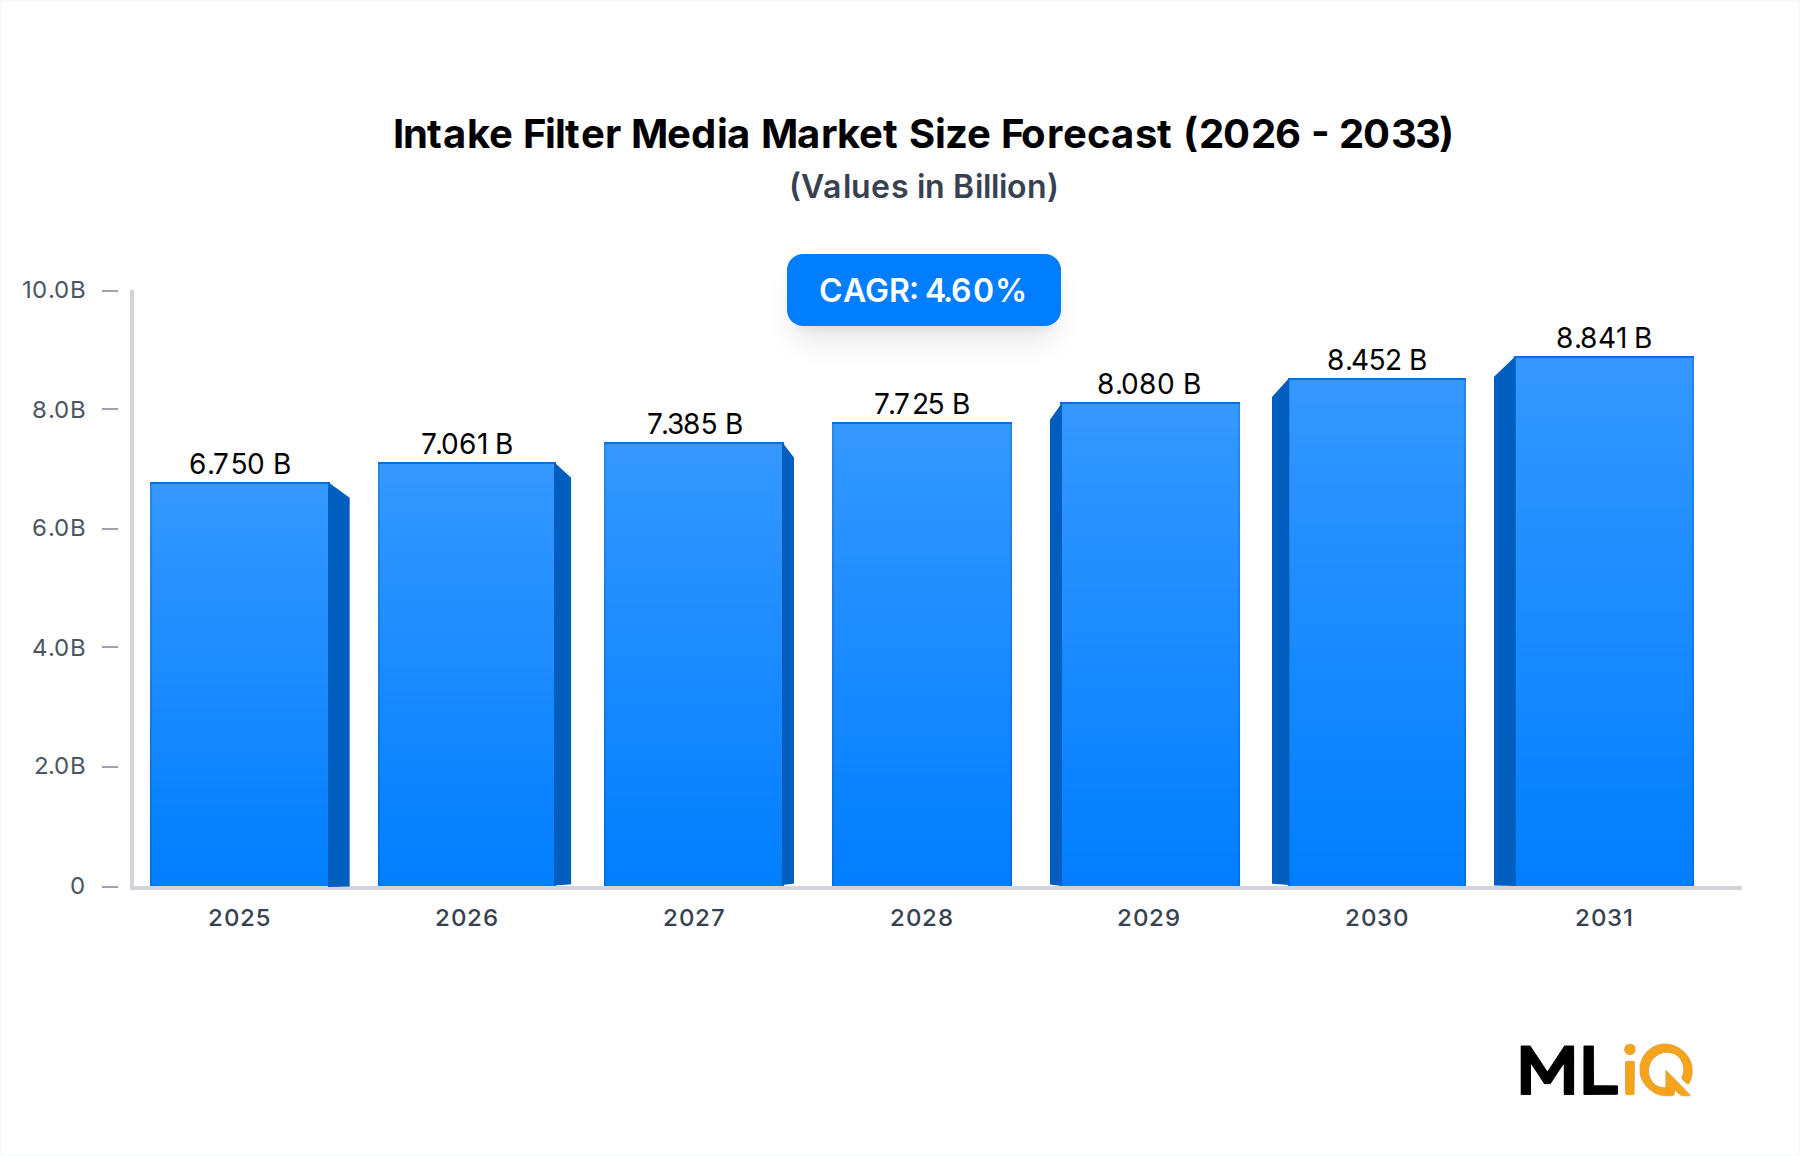
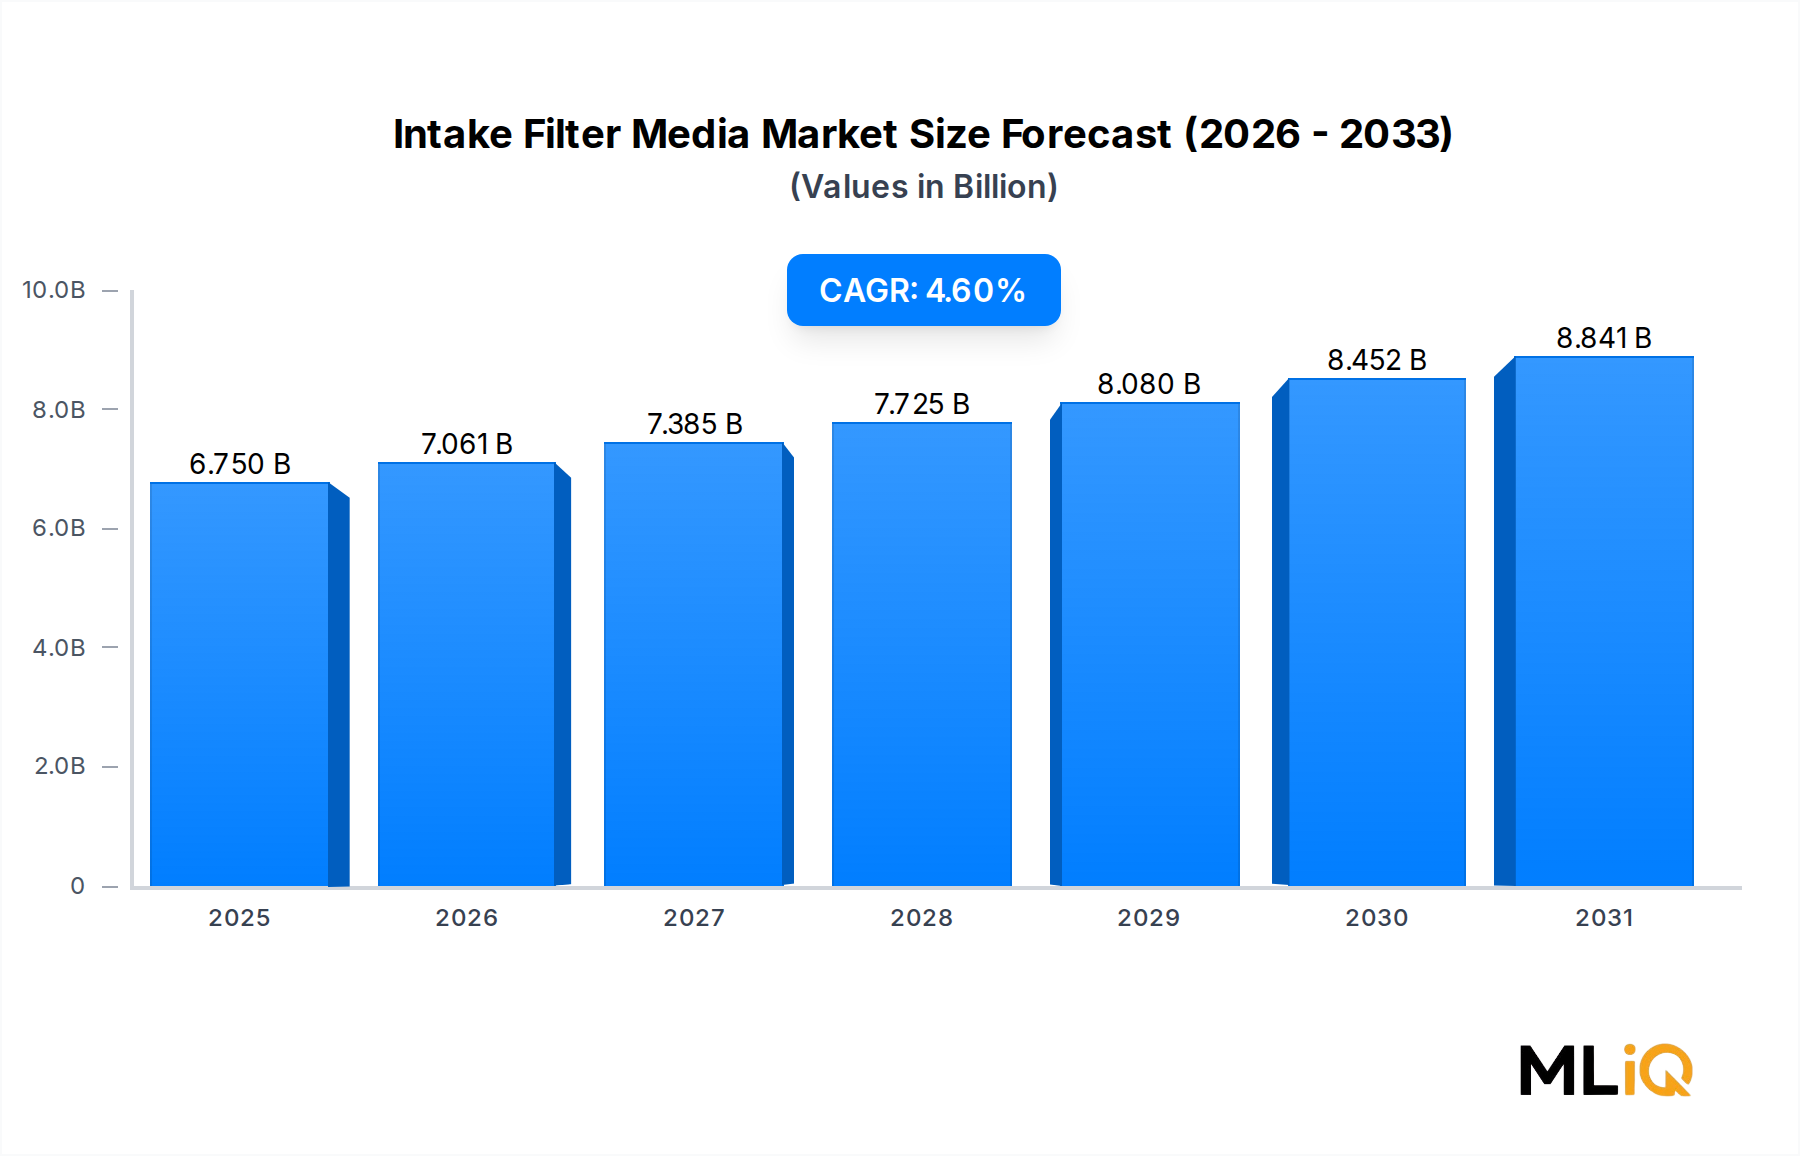
The global Intake Filter Media Market was valued at $6.75 billion in the base year and is projected to expand at a compound annual growth rate of 4.6% through the forecast horizon of 2025–2033, reflecting sustained demand across automotive, aerospace, marine, and industrial end-use applications. This growth trajectory is underpinned by tightening global emissions legislation, a rapid expansion of global vehicle parc, and the accelerating replacement cycles driven by consumer awareness of engine protection and fuel efficiency optimization.
The market's primary engine remains the automotive sector, where both passenger car and commercial vehicle segments are registering consistent filter media replacement volumes. Stricter particulate emission norms — including Euro 7 in Europe and Bharat Stage VI in India — are compelling original equipment manufacturers and aftermarket suppliers to deploy higher-efficiency filter media with improved dust-holding capacity and lower pressure drop characteristics. These regulatory mandates represent a structural demand floor that insulates the market from cyclical automotive production downturns.
Macroeconomic tailwinds further amplify this picture. Infrastructure buildout across Asia Pacific, the Middle East, and Africa is generating sustained demand for construction equipment and heavy-duty on-road vehicles, both of which consume filter media at higher replacement frequencies than light-duty passenger vehicles. Meanwhile, the resurgence of global air travel post-pandemic is revitalizing aerospace filter media demand, particularly for turboprop and turbofan intake systems where contamination control is mission-critical.
On the supply side, material innovation is reshaping the competitive landscape. Cellulose-synthetic blended media continues to command dominant volume share, but the transition toward meltblown polypropylene and electrospun nanofiber layers is accelerating. These advanced substrate technologies improve filtration efficiency ratings — often achieving ISO 5011 beta ratios exceeding 200 at 10-micron particle sizes — while enabling weight reduction in filter assemblies, a priority for electric vehicle platform designers seeking to minimize parasitic loads.
Key participants, including MANN+HUMMEL INTERNATIONAL GMBH & CO. KG, Donaldson Company Inc., and MAHLE GmbH, are intensifying R&D spending on sustainable filter media incorporating bio-based fibers and recyclable thermoplastic frames, responding to OEM sustainability mandates. The aftermarket distribution channel is simultaneously digitalizing, with e-commerce platforms capturing an increasing share of filter media unit sales, compressing traditional distribution margins and pushing suppliers toward direct-to-consumer and direct-to-workshop fulfillment models.
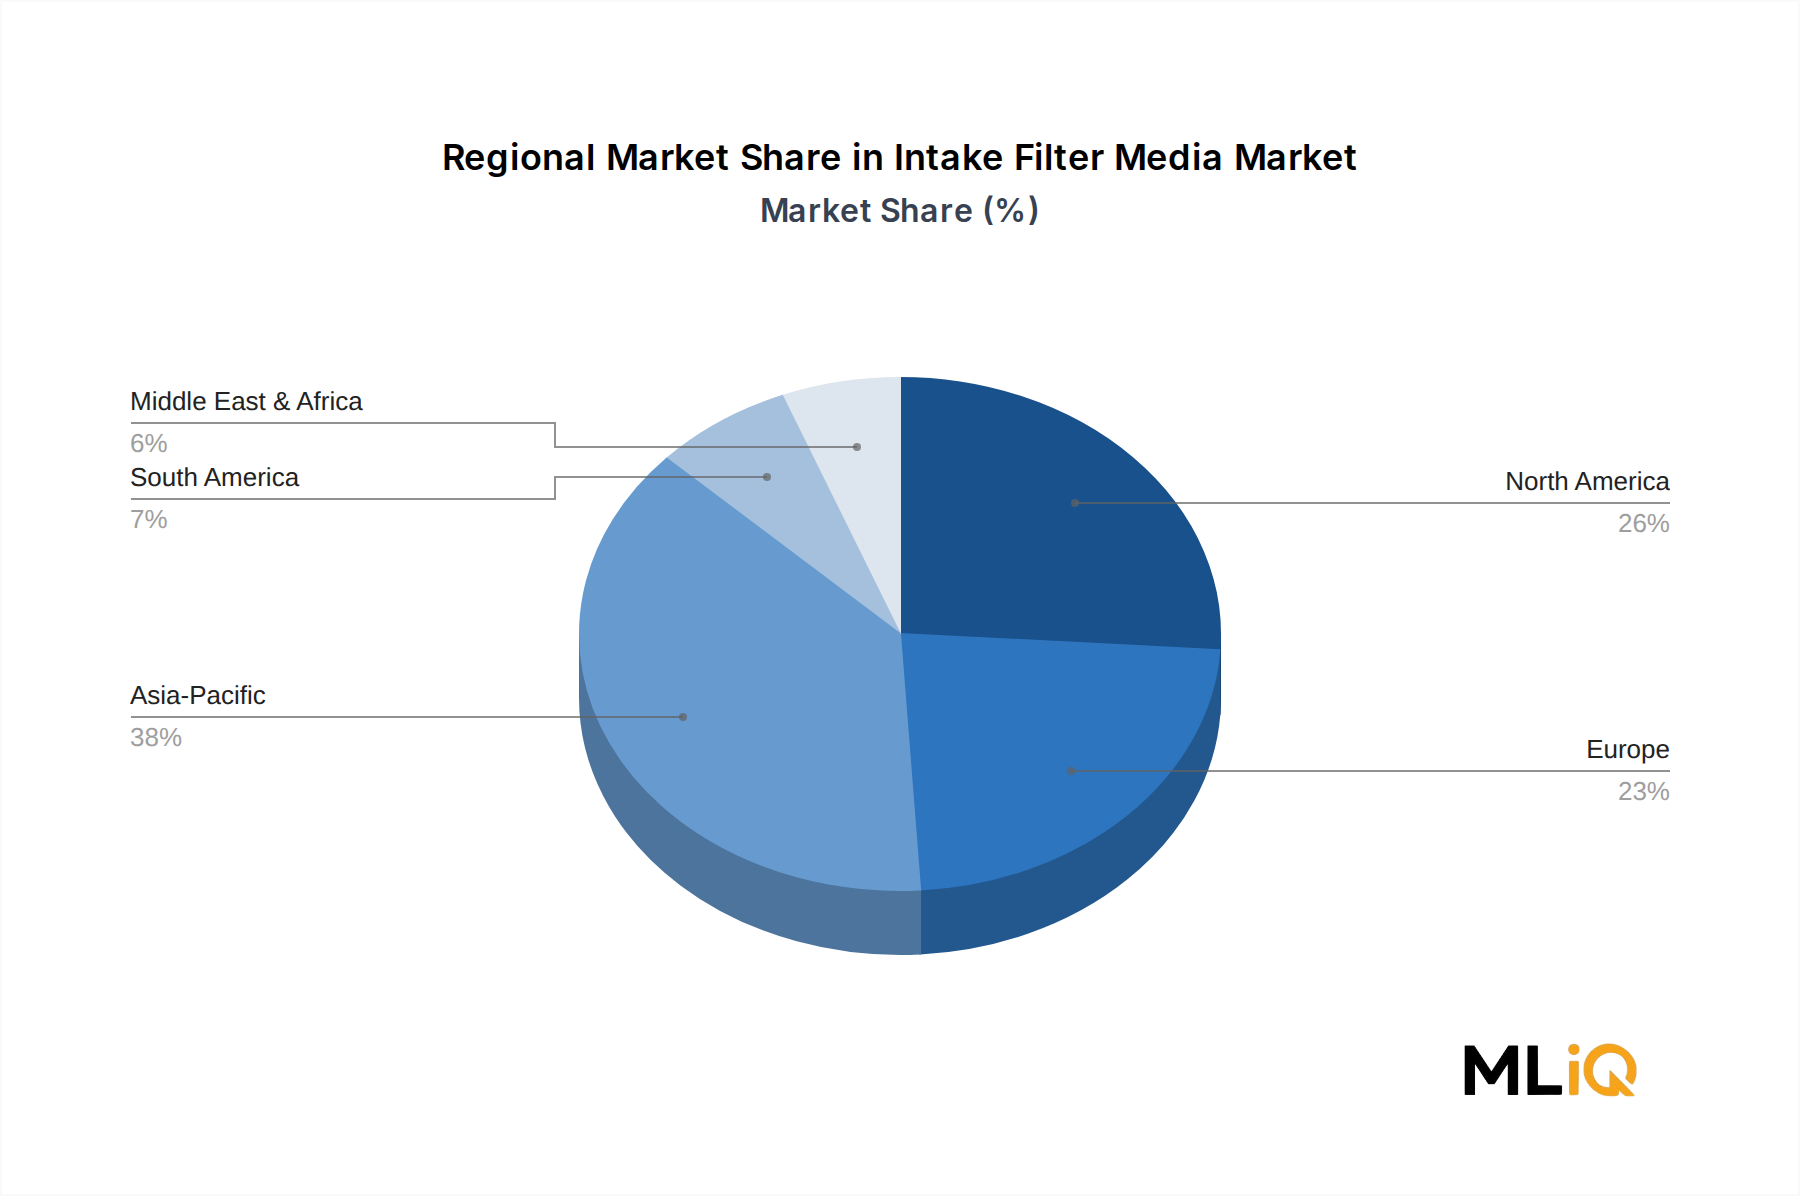
The forward-looking outlook for 2025–2033 is broadly constructive. Asia Pacific — driven by China and India — is expected to account for the largest absolute increment in market value, while North America and Europe remain high-value, mature regions anchored by stringent regulatory frameworks and robust aftermarket ecosystems. Collectively, these dynamics position the Intake Filter Media Market as a resilient, innovation-driven segment within the broader filtration industry.