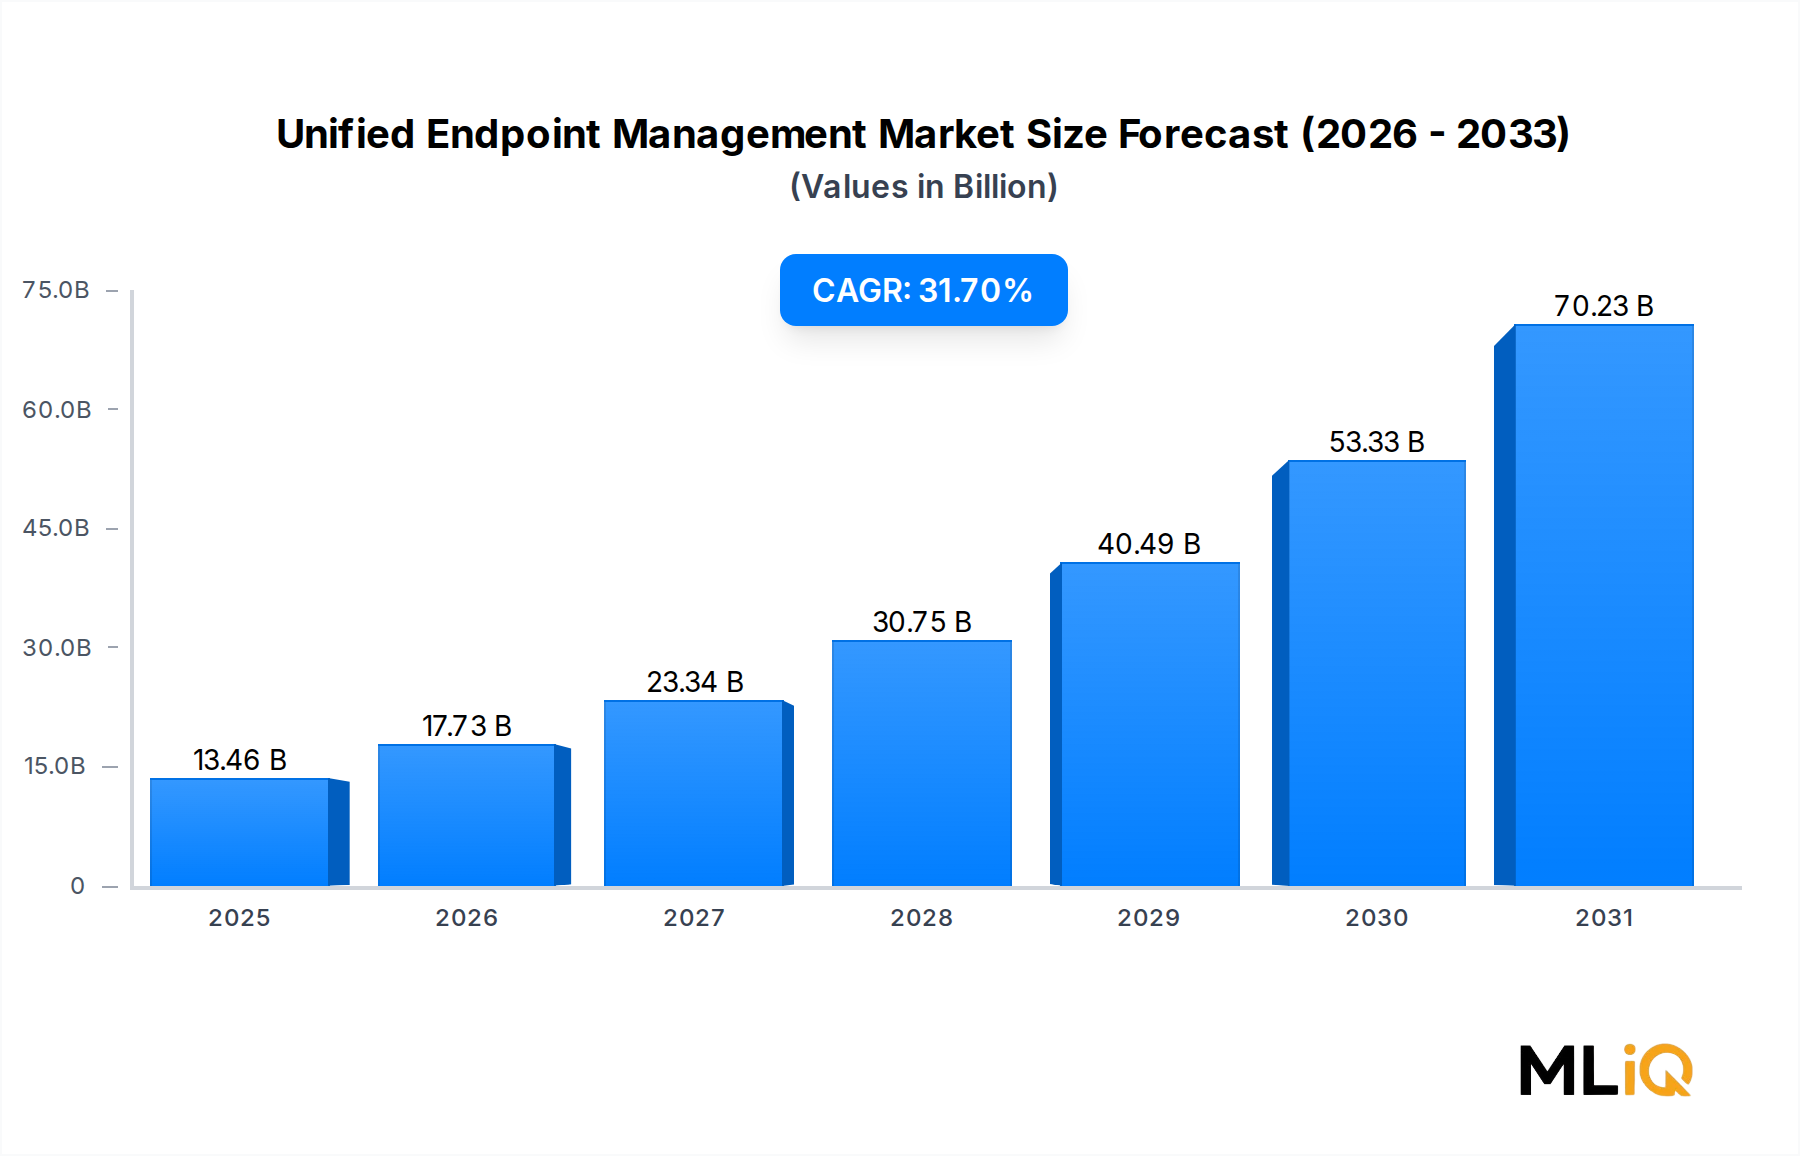
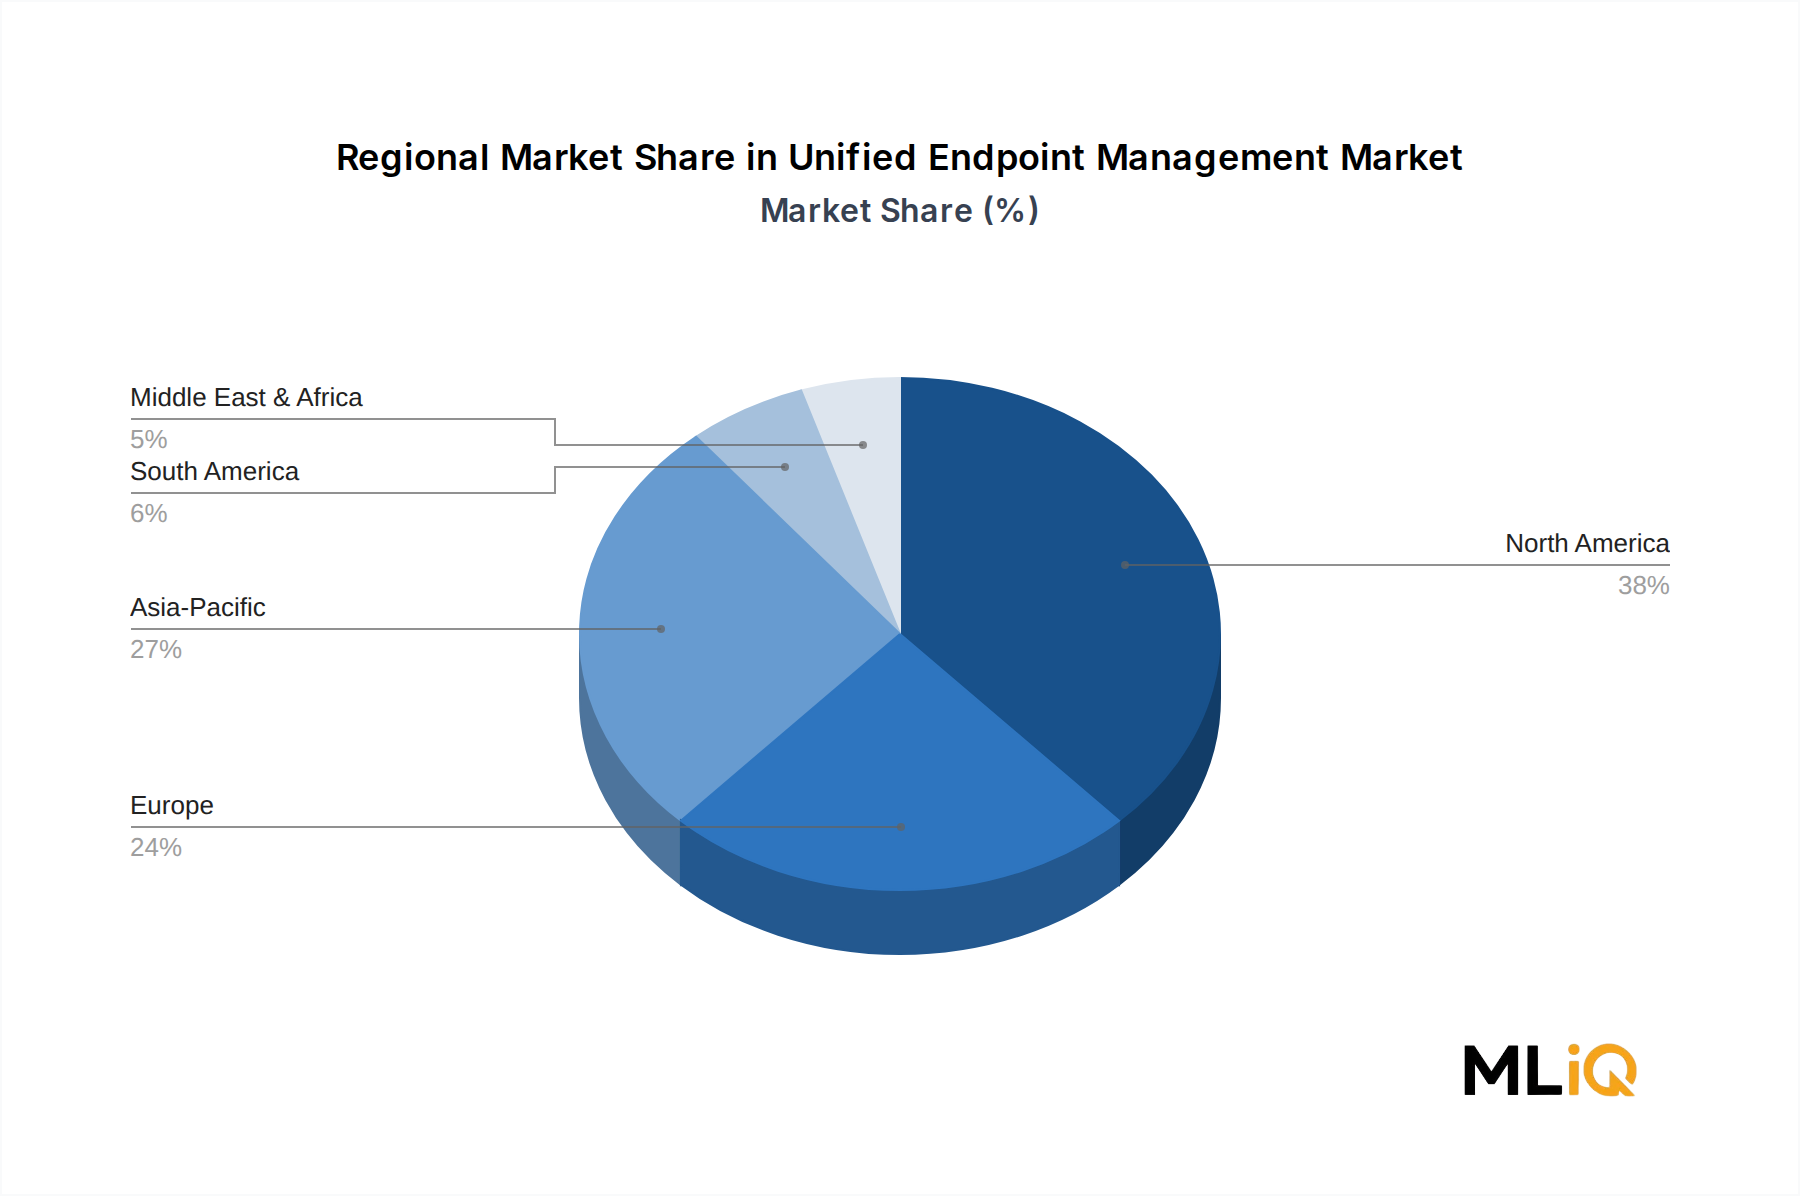
The Unified Endpoint Management Market is governed by a set of quantifiable drivers and identifiable constraints that shape investment patterns, vendor strategies, and adoption velocity across enterprise segments.
Driver 1 — Remote Work Normalization: The International Labour Organization estimated that approximately 17% of the global workforce operated remotely as of 2023, a figure that remains structurally elevated relative to pre-pandemic baselines. Each remote worker represents an endpoint operating outside the traditional network perimeter, directly increasing demand for UEM platforms capable of enforcing security policies without VPN dependency.
Driver 2 — BYOD and Multi-OS Complexity: Enterprise device environments now routinely span four or more operating systems simultaneously. Organizations managing Windows, macOS, iOS, and Android endpoints require a unified management layer to prevent policy fragmentation. UEM platforms that deliver OS-agnostic policy enforcement are commanding premium pricing, with average contract values for multi-OS deployments exceeding single-OS contracts by an estimated 35–45% in competitive deal data.
Driver 3 — Regulatory Compliance Mandates: The global regulatory environment is intensifying. The EU's NIS2 Directive, effective October 2024, explicitly requires member state organizations to implement technical controls over endpoint access. Compliance-driven procurement now represents a material portion of UEM deal closures in regulated industries including finance, healthcare, and critical infrastructure.
Constraint 1 — Integration Complexity: Enterprises operating legacy IT environments face significant integration friction when deploying UEM platforms. Heterogeneous environments with aging MDM solutions, disparate ITSM ticketing systems, and siloed identity providers create implementation timelines that can extend to 12–18 months for large organizations, dampening short-term adoption velocity.
Constraint 2 — Privacy Regulation Conflicts: In certain jurisdictions, particularly within the European Union, the comprehensive device monitoring capabilities of UEM platforms create tension with employee data privacy rights under GDPR. Legal and compliance reviews required before deployment add procurement cycle length, particularly for multinational organizations.
Constraint 3 — Skills Gap: The global cybersecurity workforce shortage, estimated at 4 million unfilled positions as of 2023 by ISC2, means many organizations lack internal expertise to configure and operationalize advanced UEM capabilities, limiting realized value and creating dependency on external managed services.