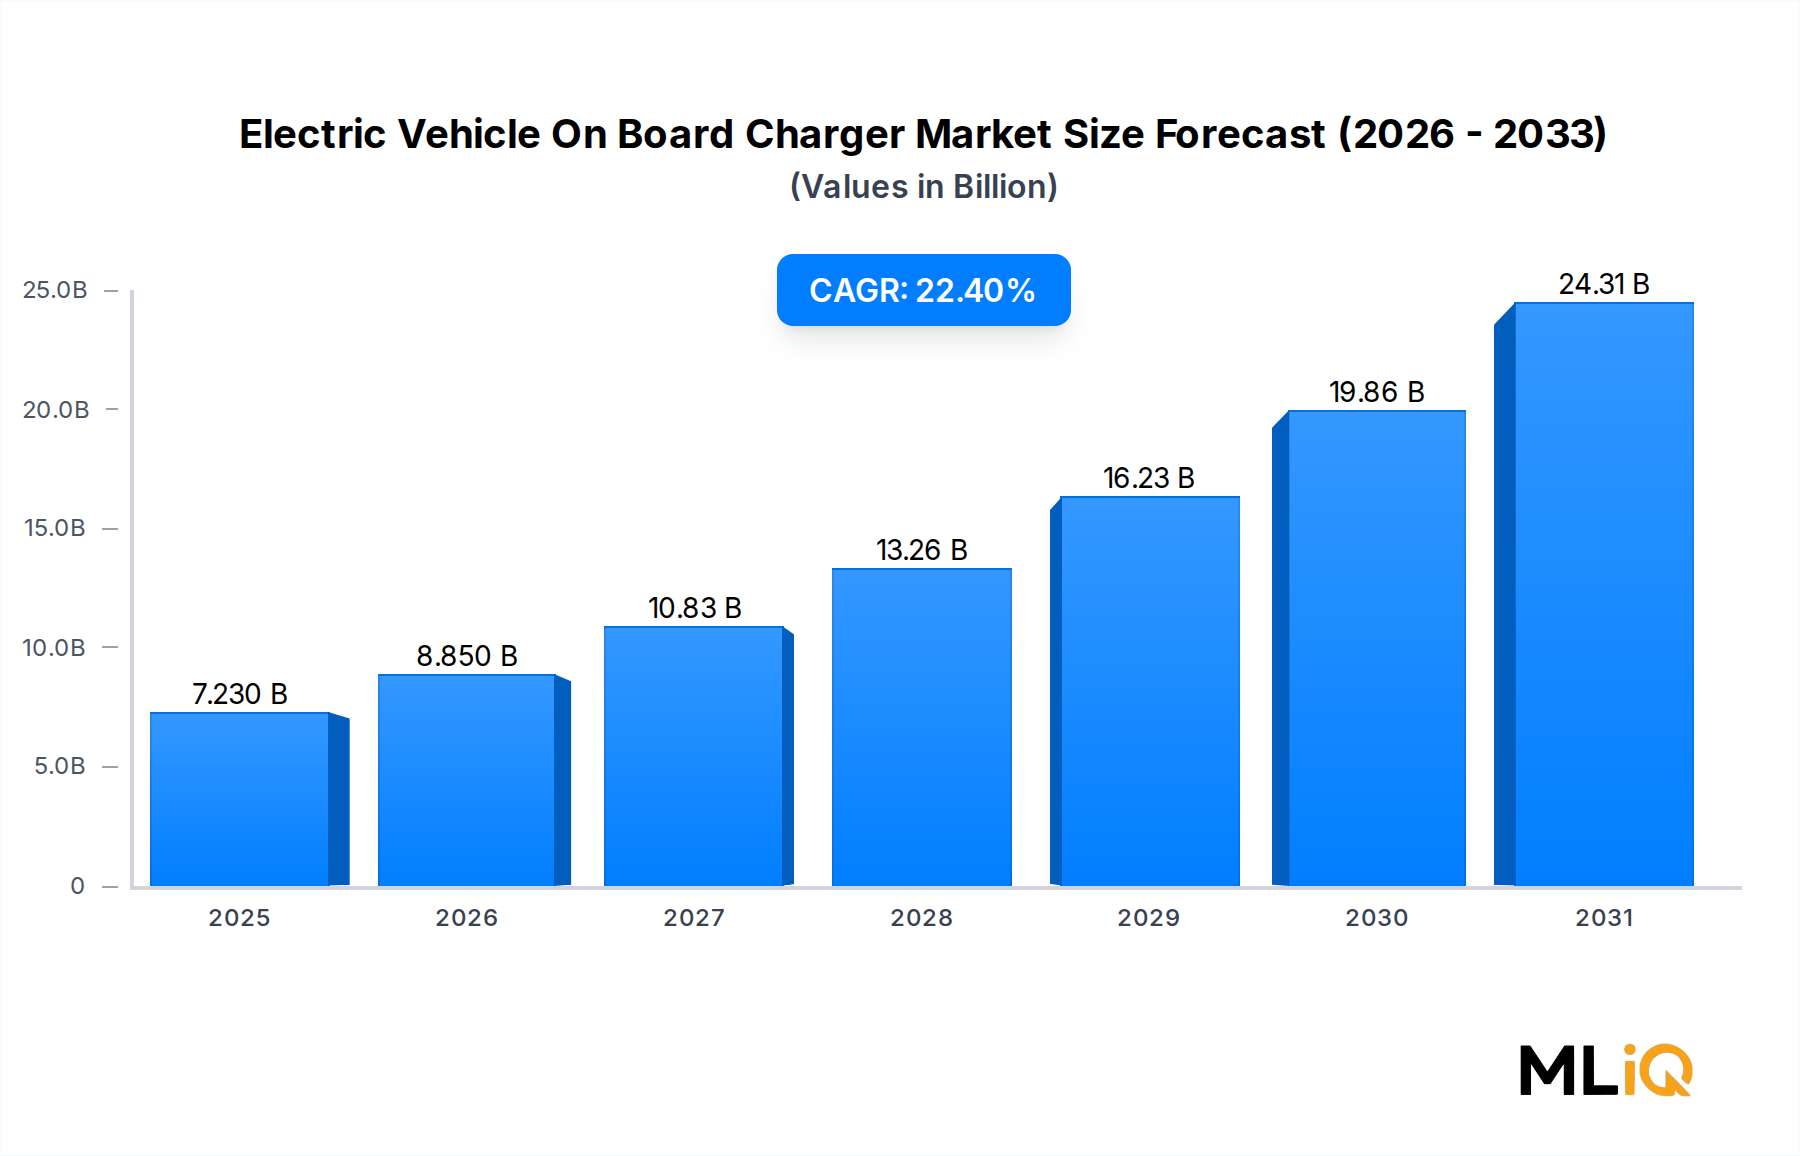
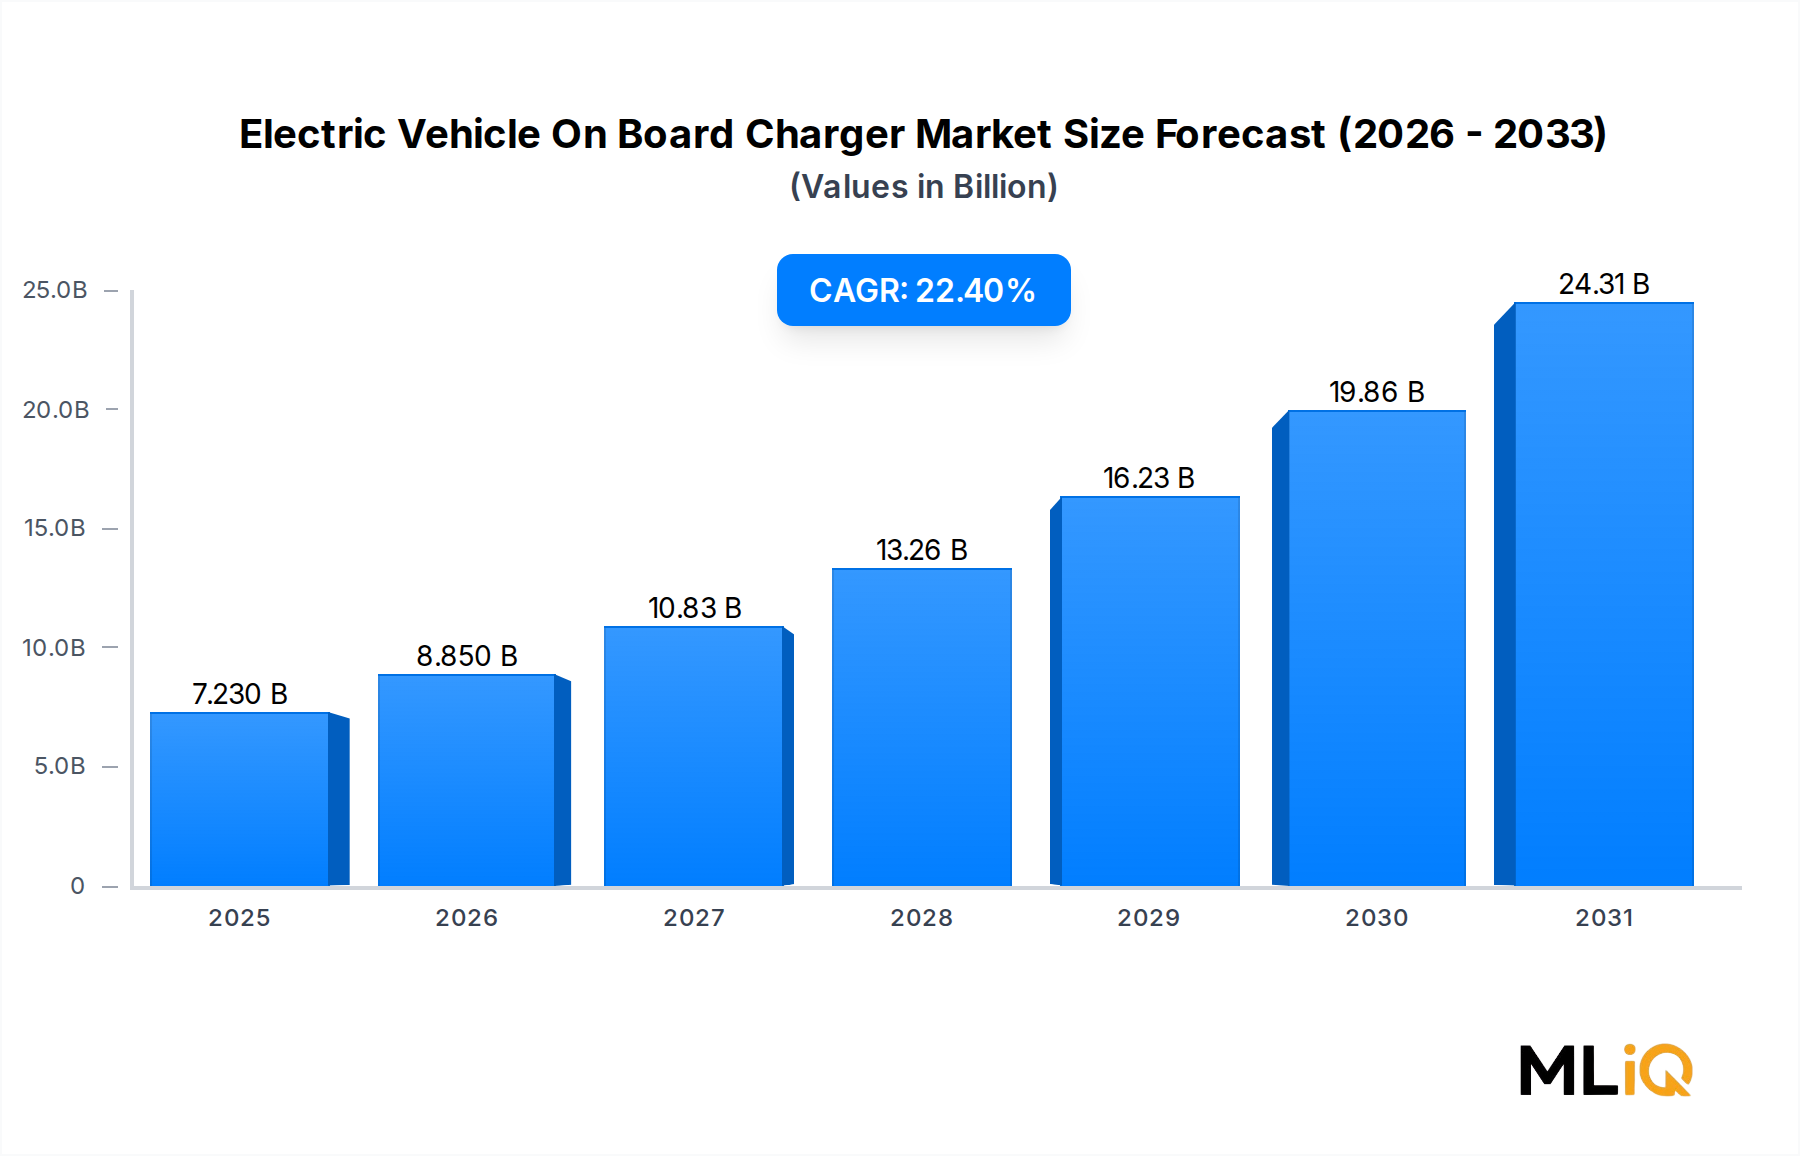
The global Electric Vehicle On Board Charger Market is valued at $7.23 billion as of the base year and is projected to expand at a compound annual growth rate of 22.4% over the forecast period, reflecting one of the most accelerated adoption curves within the broader automotive electrification ecosystem. On-board chargers (OBCs) are mission-critical power conversion units embedded within electric vehicles that condition AC power from external charging infrastructure into DC power suitable for battery storage. Their proliferation is directly correlated with surging EV penetration rates worldwide.
The market's primary demand tailwind is the sweeping global commitment to decarbonizing road transport. Governments across North America, Europe, and Asia Pacific have enacted binding zero-emission vehicle mandates, fleet electrification targets, and subsidy schemes that are compressing the total cost of EV ownership and accelerating OBC demand across all vehicle categories. The European Union's landmark 2035 internal combustion engine ban and the United States Inflation Reduction Act's EV tax credit provisions are structurally reshaping procurement pipelines for OBC manufacturers.
From a technology perspective, the transition from 3.3 kW and 6.6 kW first-generation chargers to high-power 11 kW, 22 kW, and beyond-20 kW architectures is a defining inflection point. Consumers and fleet operators increasingly demand faster home charging cycles, pushing OEMs and Tier-1 suppliers to qualify higher-density designs. The integration of bidirectional charging capability — enabling vehicle-to-grid (V2G) and vehicle-to-home (V2H) functionality — is emerging as a key product differentiator, adding significant value per unit and broadening addressable revenue.
On the component side, the ongoing migration from silicon-based power devices to silicon carbide (SiC) and gallium nitride (GaN) semiconductors is enabling higher switching frequencies, reduced thermal losses, and greater power density in increasingly compact OBC form factors. This is catalyzing sustained investment across the semiconductor and passive component supply chains.
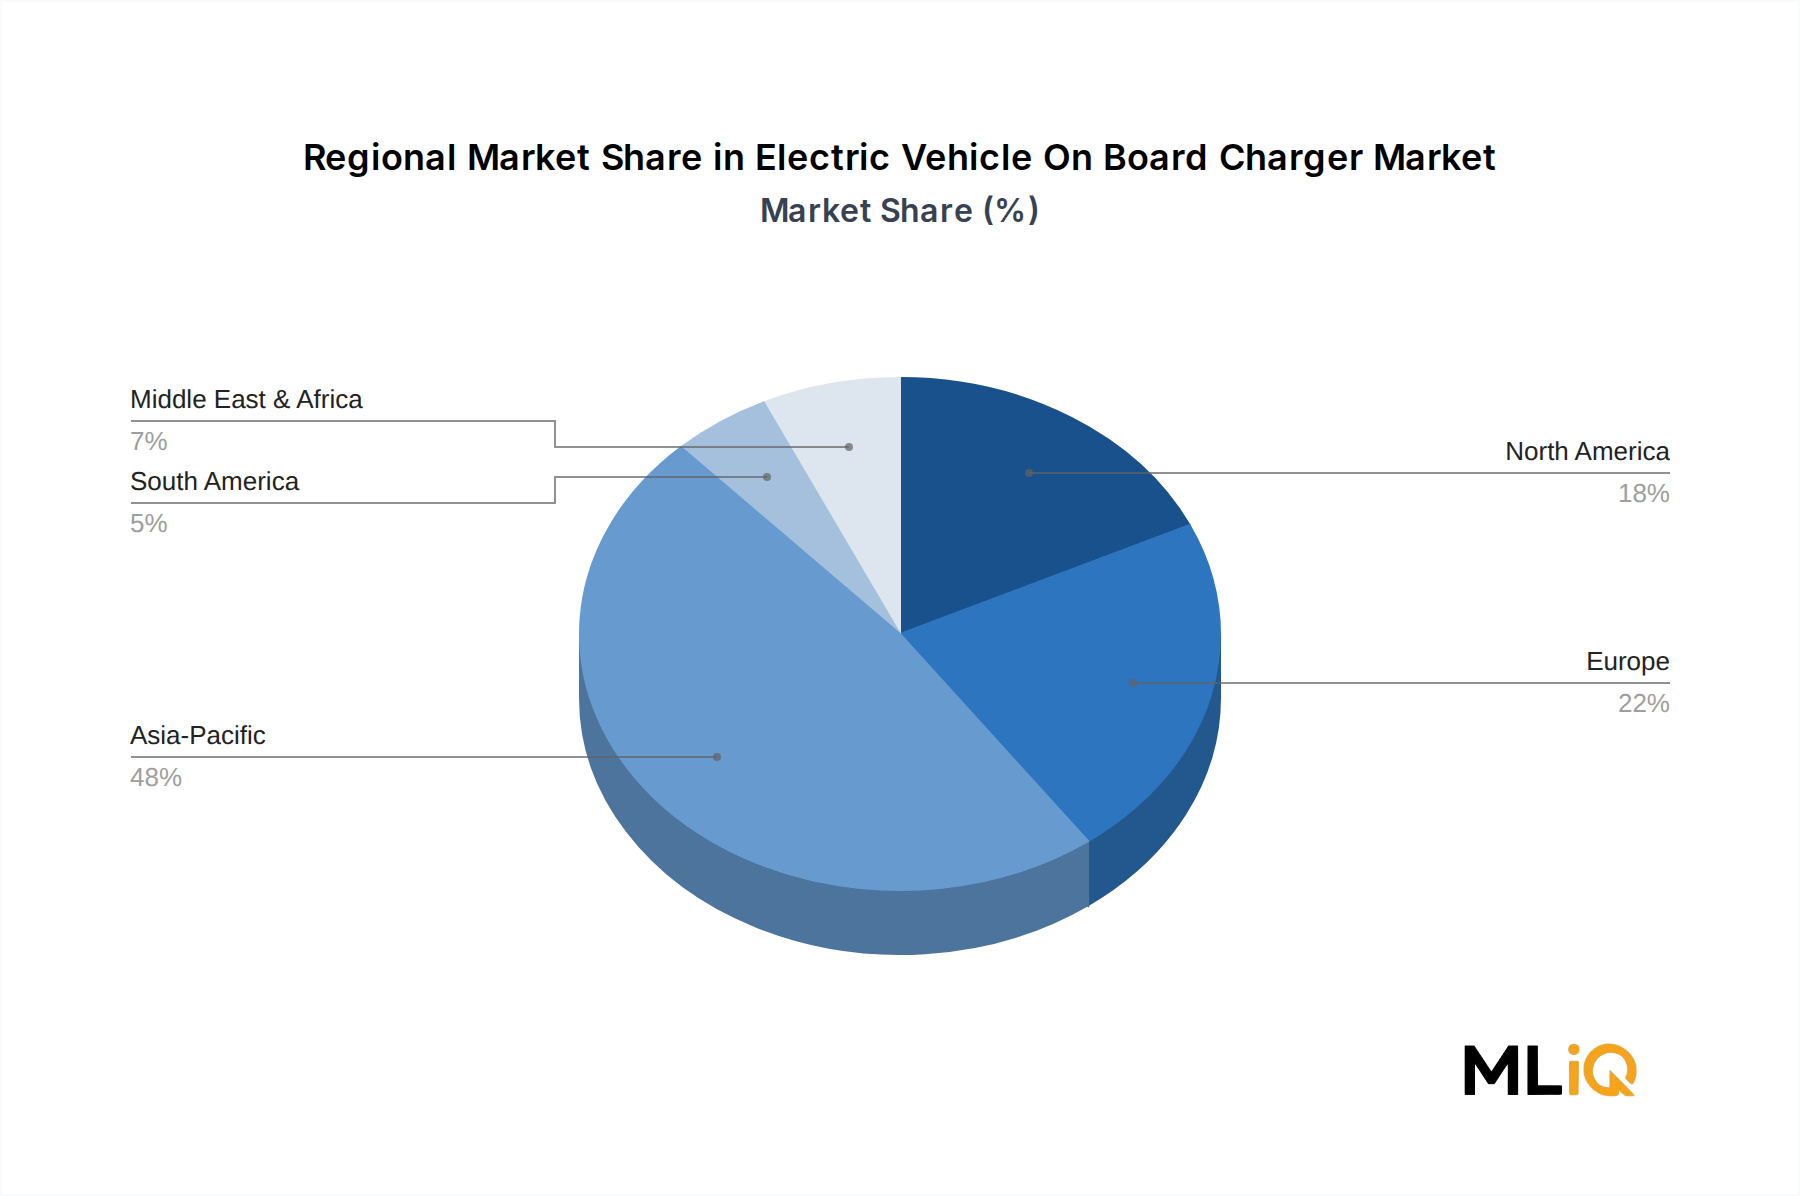
The competitive landscape is bifurcating between vertically integrated automotive suppliers seeking to bundle OBC systems with broader e-axle platforms and specialist power electronics firms offering modular, scalable solutions. China remains the single largest production and consumption geography, but European and North American supply chain localization efforts are reshaping trade dynamics.
Looking ahead through 2031, demand is expected to be particularly pronounced in the electric passenger car and electric commercial vehicle segments, with high-power OBC variants capturing a disproportionate share of incremental revenue as fleet electrification programs scale globally.