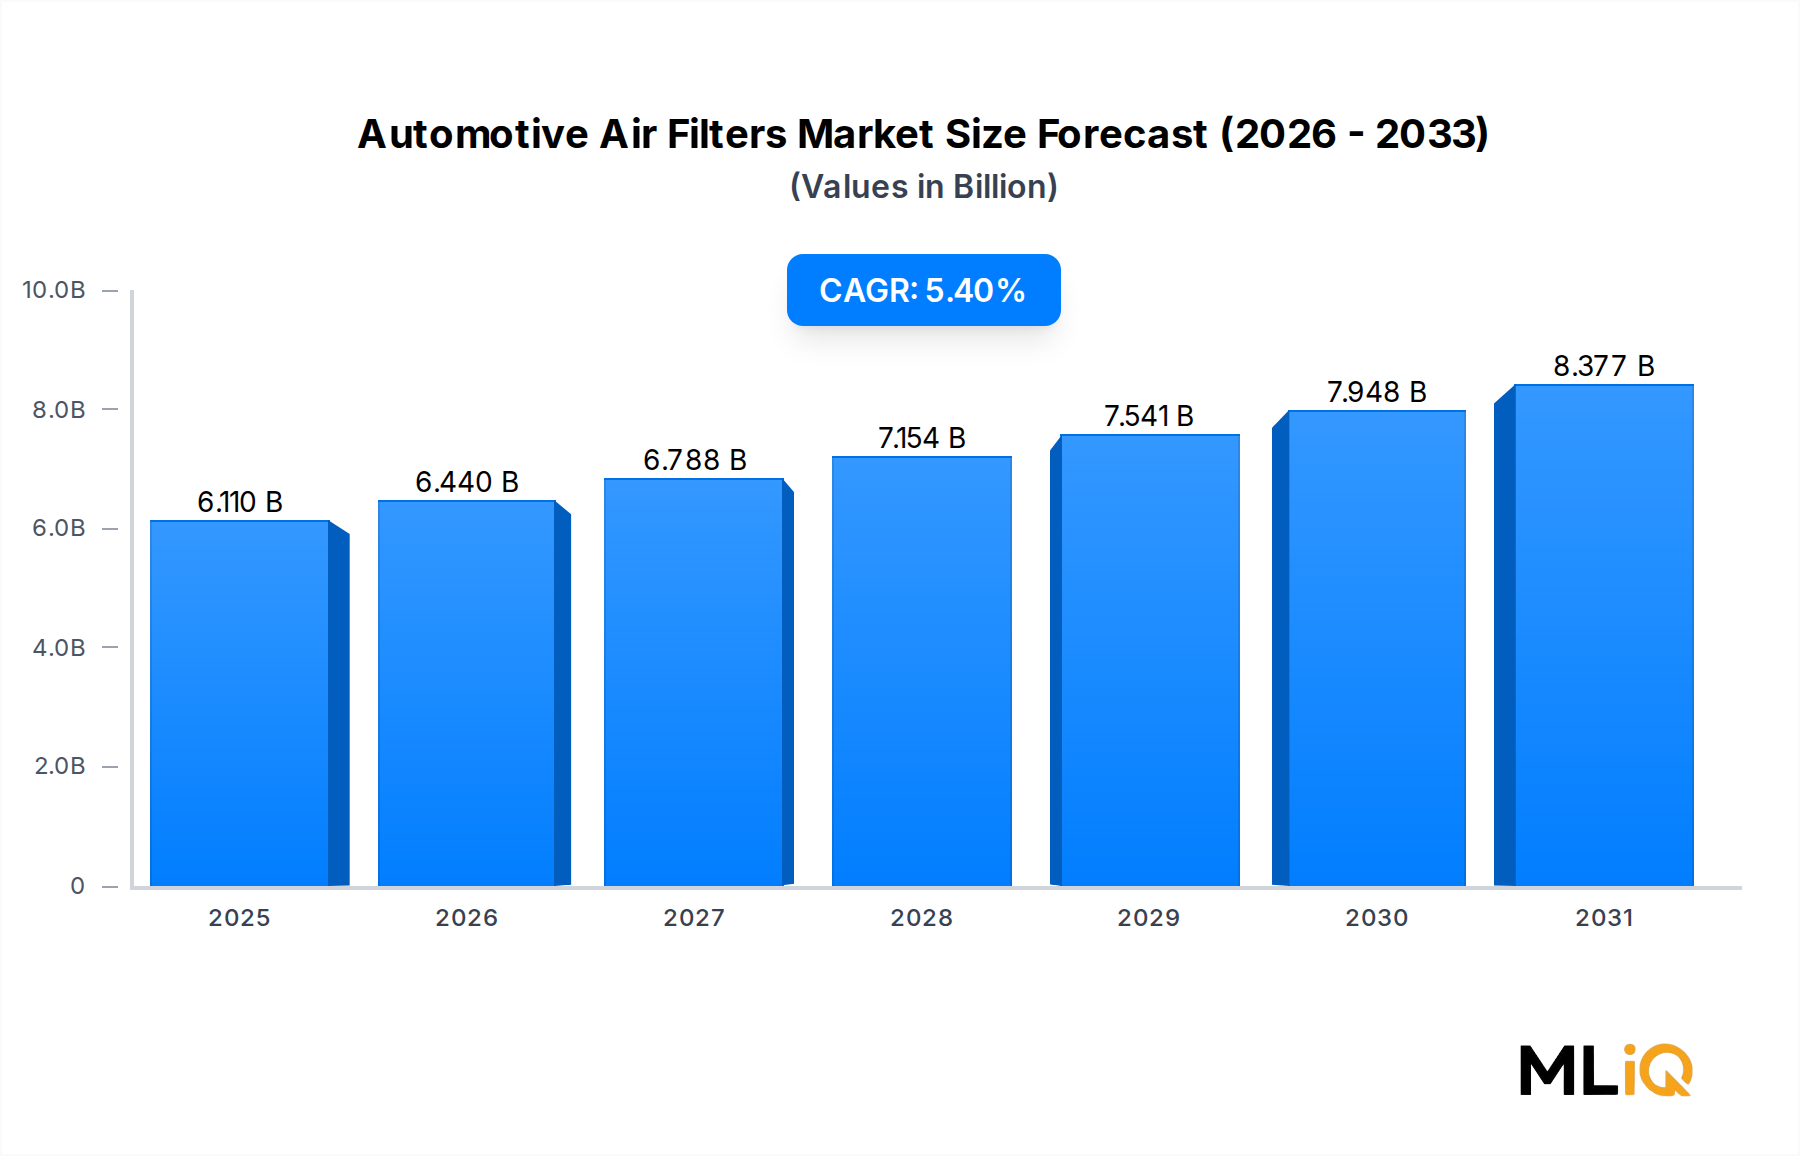
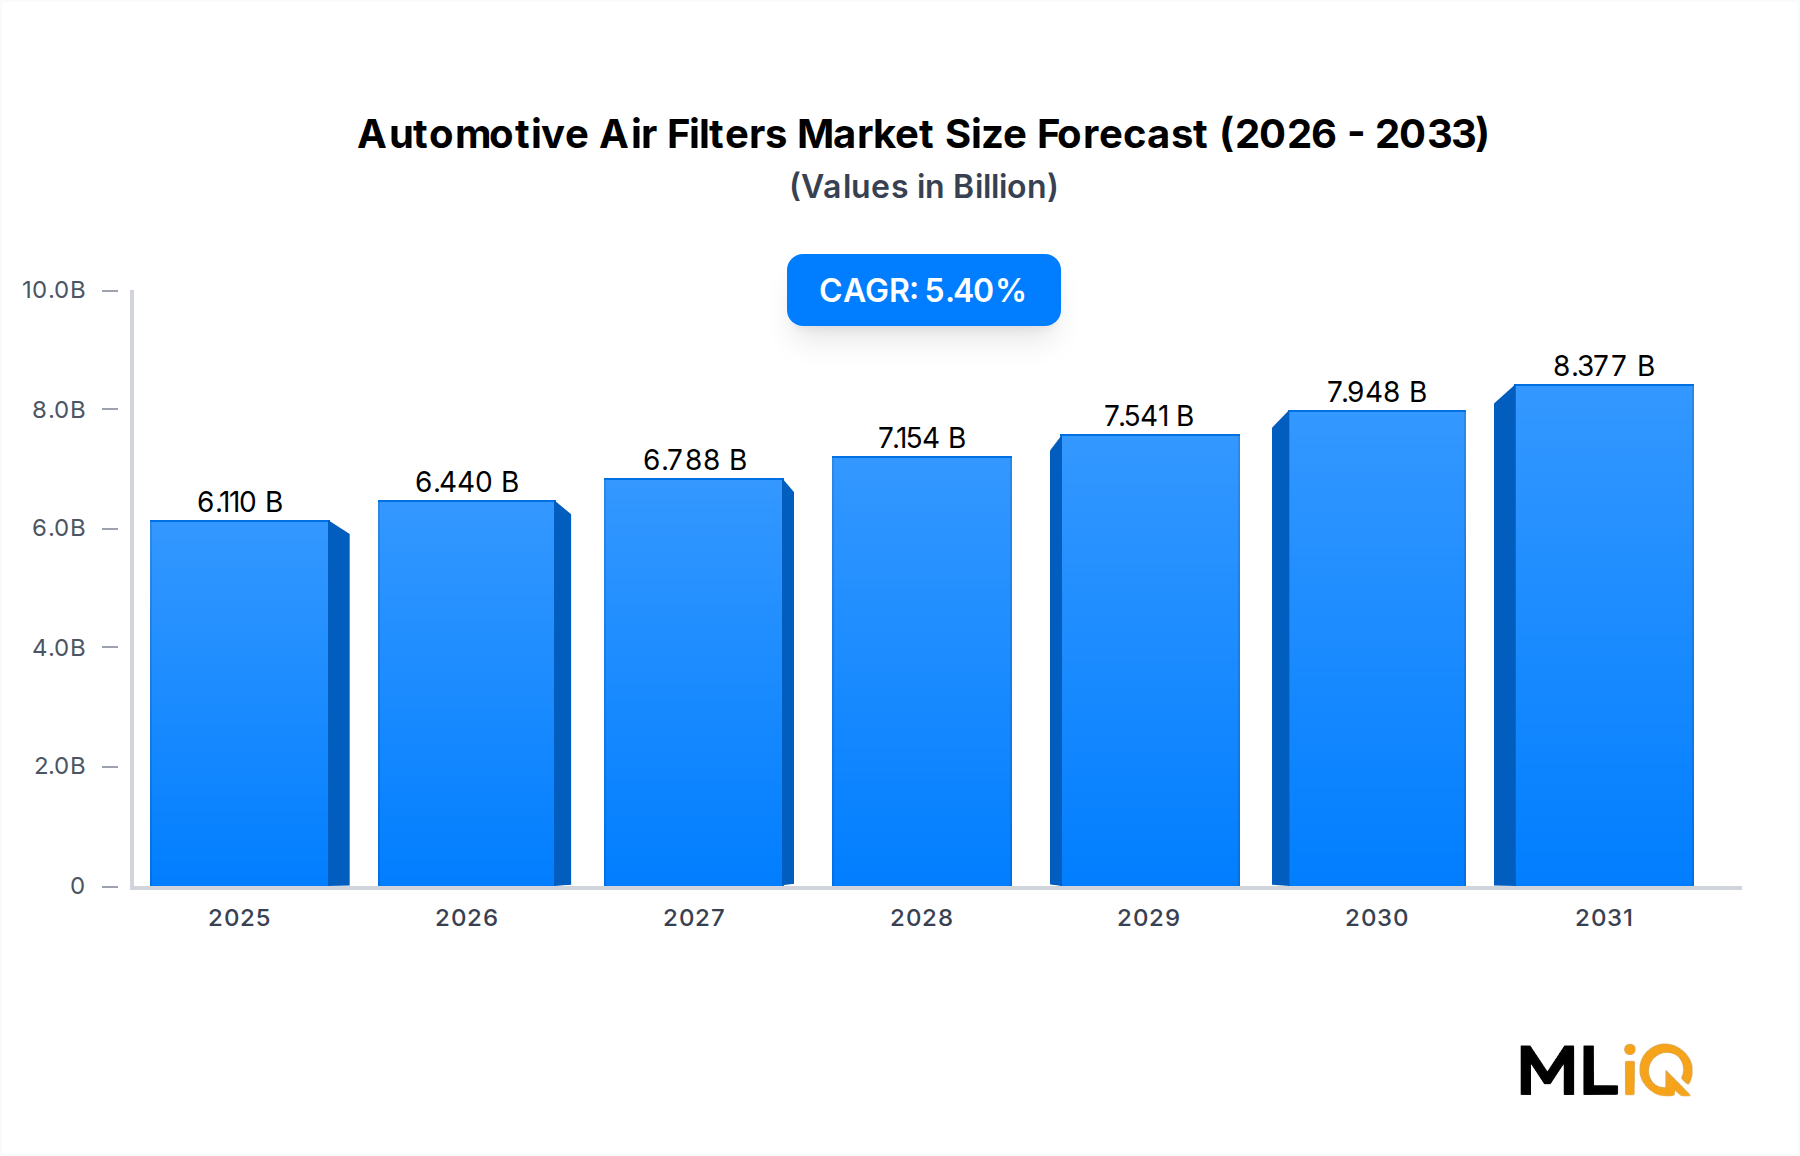
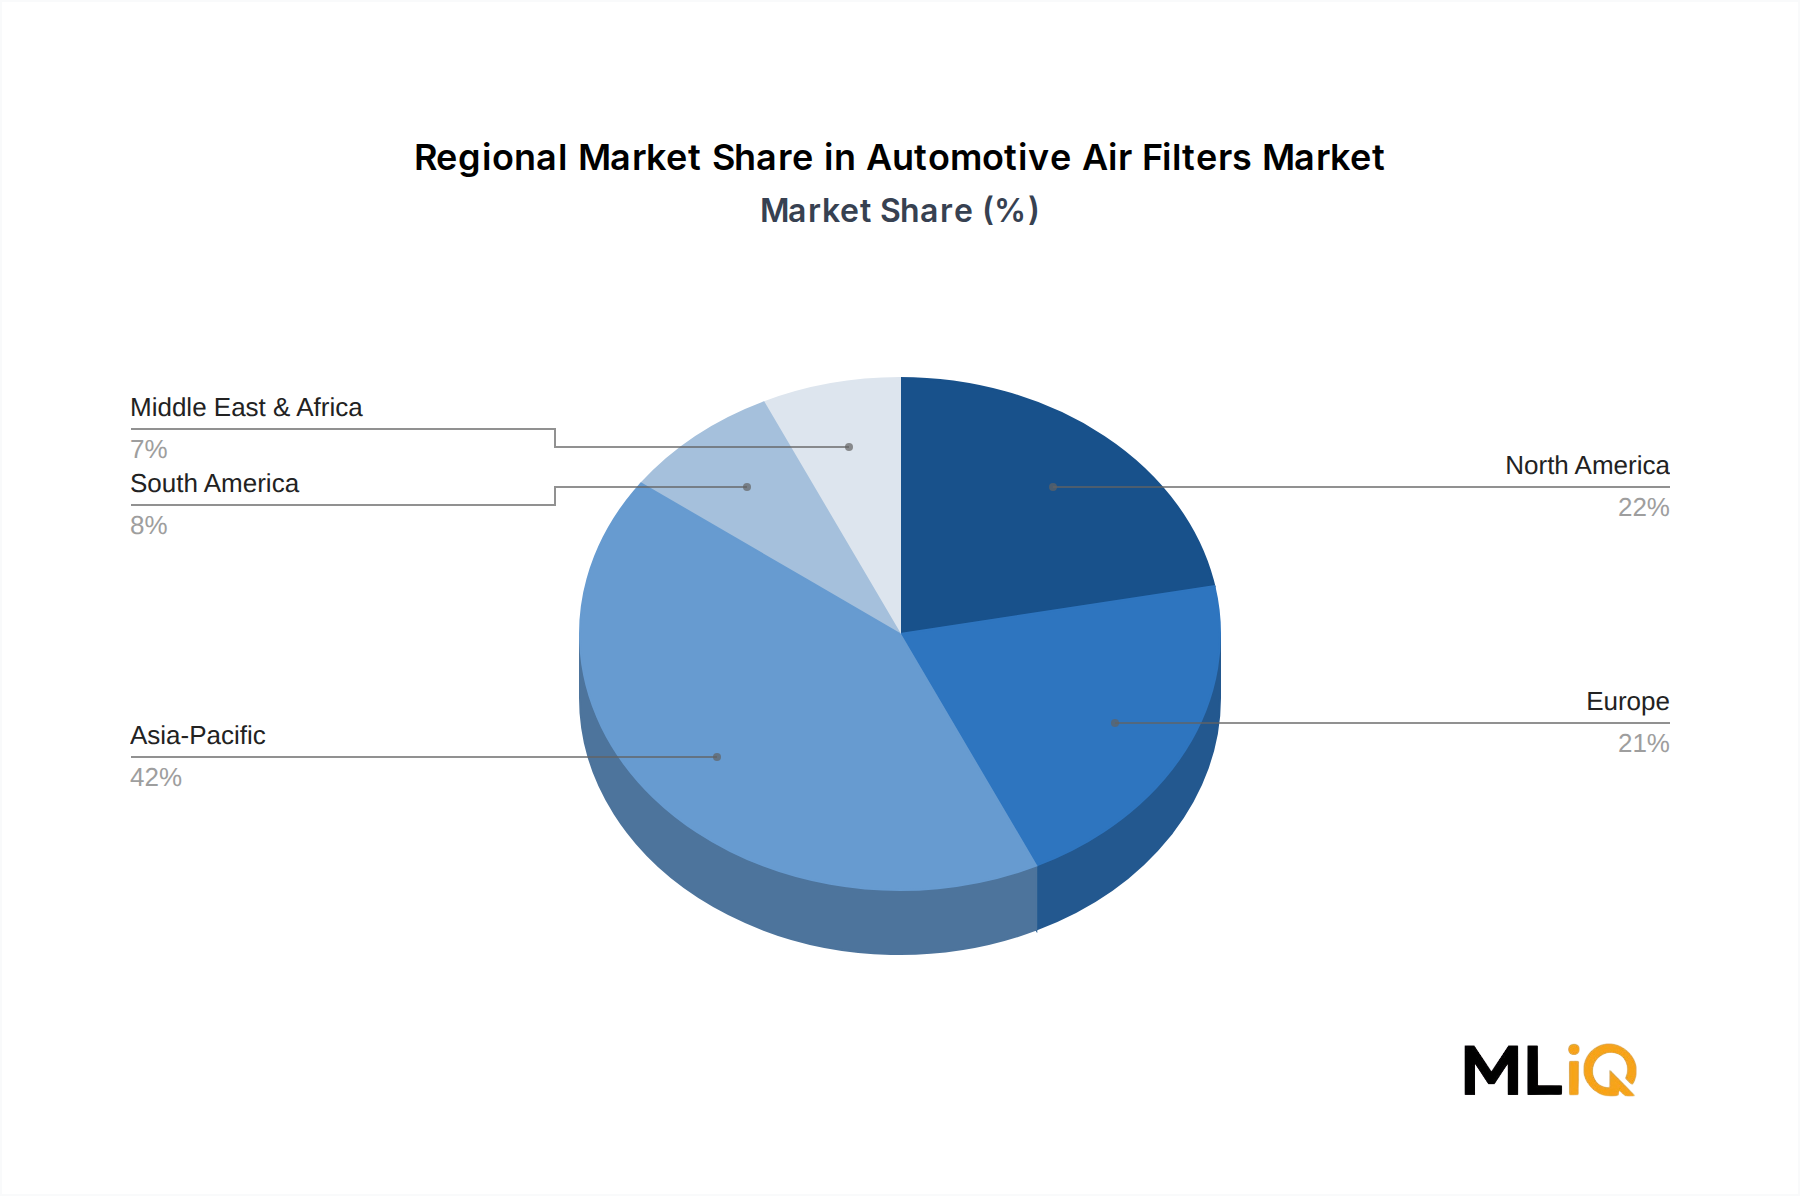
The Automotive Air Filters Market exhibits pronounced regional heterogeneity in terms of growth velocity, demand composition, and competitive dynamics, reflecting differences in vehicle fleet composition, regulatory environments, urbanization trajectories, and consumer purchasing behavior.
Asia Pacific is unequivocally the largest and fastest-growing regional market, accounting for an estimated 42–45% of global revenue. China alone contributes the single largest national share, driven by its position as the world's largest automotive production and sales market, combined with China 6b emission standards enforcing stringent intake filtration specifications. India represents the highest-growth sub-market within the region, with a vehicle parc growing at approximately 7–8% annually and cabin filter penetration rates that remain materially below global averages, creating substantial addressable whitespace. The Asia Pacific region is projected to sustain a regional CAGR of approximately 6.5–7.0% through 2033, outpacing all other geographies.
Europe constitutes the second-largest regional market, with Germany, France, the United Kingdom, Italy, and Spain as primary demand centers. The region is characterized by a mature vehicle parc with high average filter specification quality, driven by Euro 7 compliance requirements and elevated consumer health consciousness. European demand growth is moderate, estimated at a regional CAGR of approximately 3.5–4.5%, with value growth outpacing volume growth due to premium filter adoption. The region serves as the primary innovation hub for nanofiber, electrostatic, and multi-functional cabin filtration technologies.
North America represents the third-largest market, with the United States accounting for the bulk of regional revenue. North American demand is driven by a large light-truck and SUV-dominant vehicle fleet, stringent EPA particulate standards, and a well-developed independent aftermarket distribution network. Regional CAGR is estimated at 4.0–4.8%, supported by replacement cycle demand and growing premium cabin filter adoption. Canada and Mexico contribute secondary demand, with Mexico benefiting from its role as a key automotive manufacturing hub supplying North American OEMs.
The Middle East and Africa region, while smaller in absolute terms, exhibits above-average growth potential, particularly in GCC countries where high vehicle ownership rates and dusty operating environments drive accelerated engine air filter replacement cycles. South Africa represents the most developed filtration aftermarket on the African continent.
South America, led by Brazil and Argentina, presents a mid-tier growth opportunity, constrained by macroeconomic volatility but supported by a large and aging vehicle parc with consistent replacement filter demand. Brazil's local automotive manufacturing base provides an anchor for OEM-channel filter supply activity.