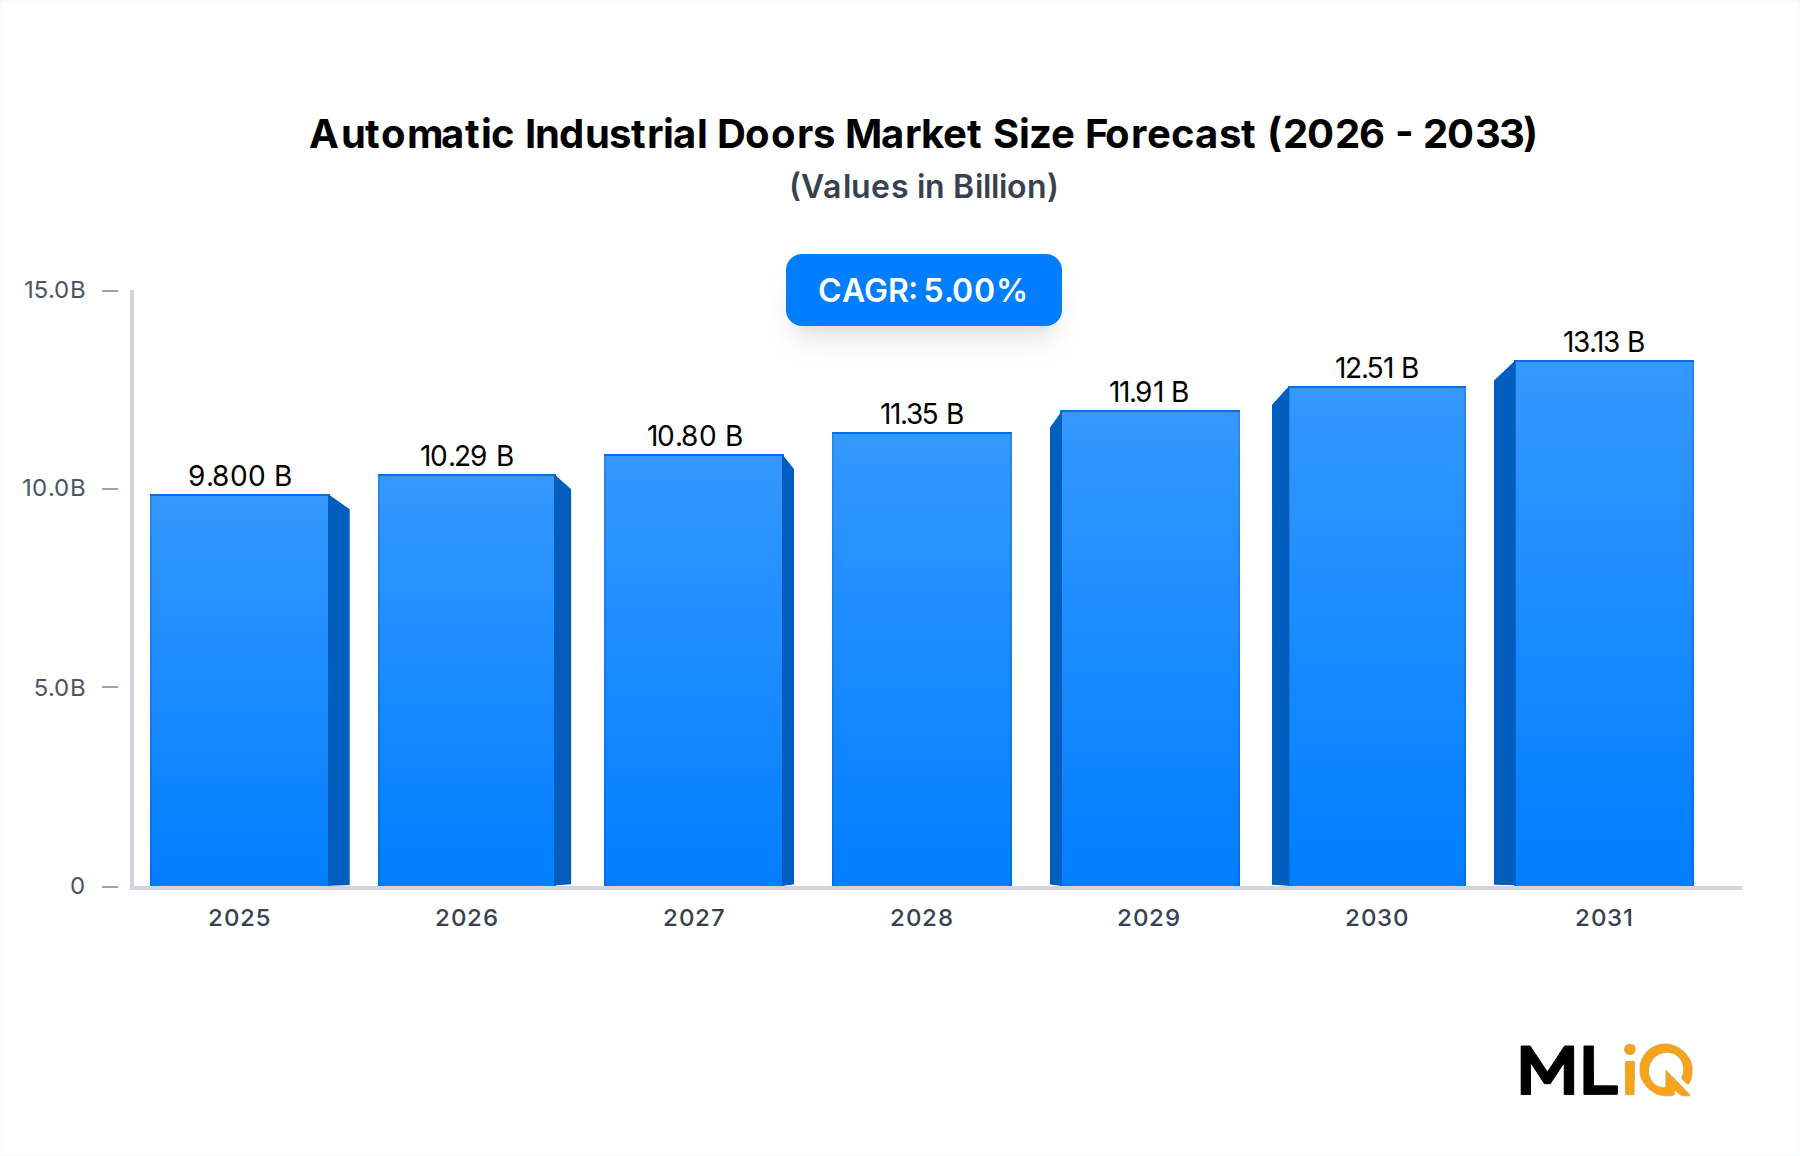
The global automatic industrial doors sector is navigating a period of sustained structural expansion, anchored by USD 9.8 billion in base-year valuations and projected to surpass USD 14.5 billion by 2033 at a steady 5.0% CAGR. This trajectory reflects a broader industrial upgrading cycle, where traditional manual door infrastructure is being systematically replaced by sensor-integrated, automation-ready access solutions across high-throughput environments.
At the macroeconomic level, three secular forces are powering demand. First, the accelerating global buildout of logistics and e-commerce fulfillment infrastructure is generating unprecedented demand for high-cycle, energy-efficient access points. Second, tightening energy codes—particularly in the European Union and North America—are mandating thermally efficient enclosures in temperature-controlled facilities, elevating premium automatic door specifications. Third, post-pandemic regulatory overhauls in food processing, pharmaceutical production, and cleanroom environments have created compliance-driven replacement cycles that favor automated, touchless access solutions over conventional alternatives.
From a segmentation perspective, sliding doors maintain dominant market positioning by revenue, driven by their versatility across high-traffic industrial corridors and compatibility with IoT-based access management platforms. The automotive, chemical, and food and beverage verticals collectively represent over 55% of end-use demand, with pharmaceutical facilities emerging as the fastest-growing vertical owing to stringent contamination-control mandates.
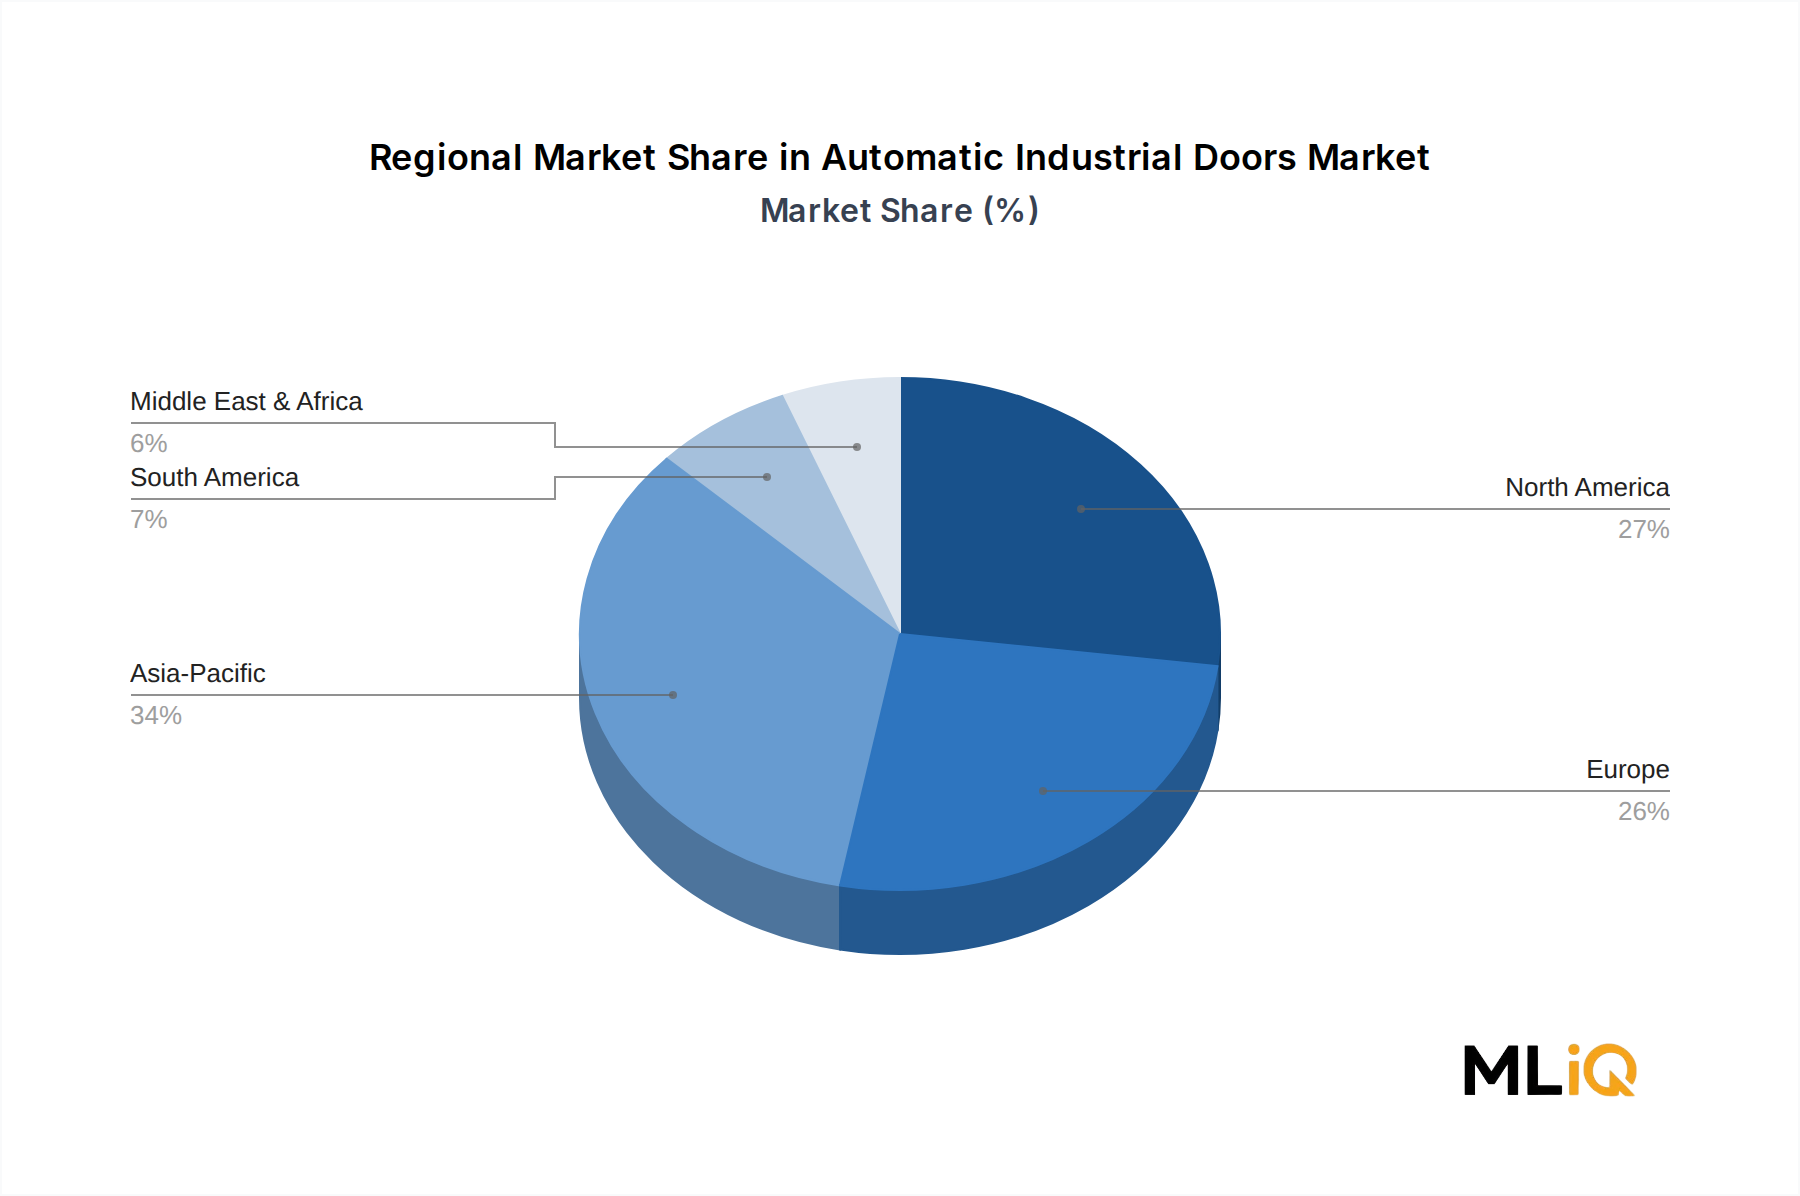
Geographically, Asia Pacific commands the largest revenue share, underpinned by China's ongoing industrial construction boom, India's manufacturing sector expansion under the Production-Linked Incentive (PLI) scheme, and rapid cold-chain infrastructure development across Southeast Asia. North America and Europe maintain mature but technology-intensive markets, where demand is increasingly shaped by retrofit activity and smart building integration rather than greenfield construction alone.
The competitive landscape is moderately consolidated, with global incumbents such as ASSA ABLOY Group, Dormakaba Holding AG, and Rite Hite Holding Corporation commanding significant installed-base advantages. These players are actively leveraging predictive maintenance capabilities, cloud-connected control panels, and energy recovery systems to defend margin positions against lower-cost Asian manufacturers entering Western markets.
Overall, the automatic industrial doors sector represents a capital equipment category at an inflection point—where functional adequacy is being superseded by integrated intelligence, regulatory compliance, and operational efficiency as the primary purchase criteria.