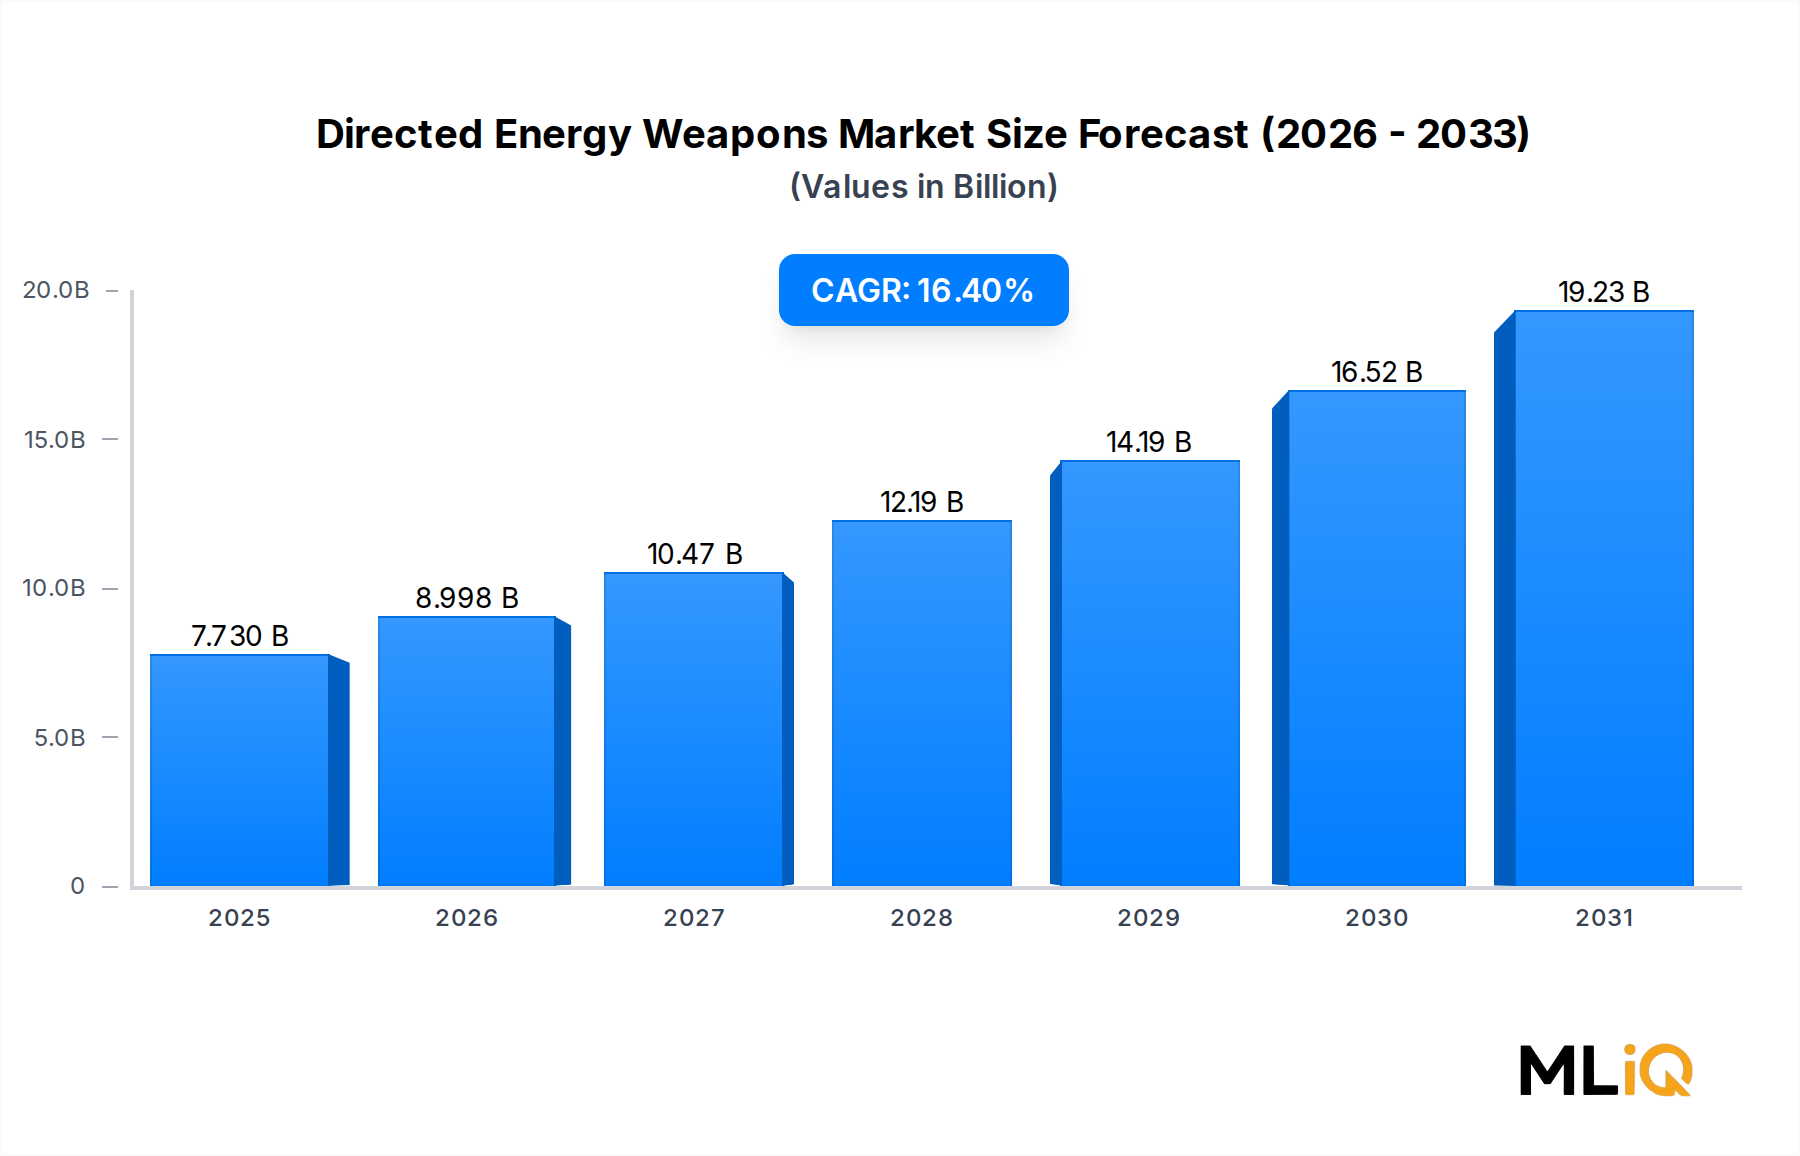
Within the Directed Energy Weapons Market, the High Energy Laser (HEL) segment commands the largest share of revenue and investment activity, a position expected to consolidate further through 2033. HEL systems have achieved the most advanced technology readiness levels among directed energy modalities, with multiple programs transitioning from technology demonstrators and limited fielding experiments into full-rate production and operational deployment across land, naval, and airborne platforms.
The dominance of HEL systems stems from several compounding advantages. First, the precision engagement capability of a coherent laser beam — with near-instantaneous travel time and no requirement for projectile ballistics correction — makes it uniquely suited to counter fast-moving threats including cruise missiles, rocket artillery, mortars, and unmanned aerial vehicle swarms. Second, the magazine-depth advantage is structurally compelling: as long as the host platform has access to power generation, a high-energy laser can sustain engagements indefinitely, contrasting sharply with finite conventional missile inventories. Third, HEL systems generate minimal collateral damage risk in complex urban or maritime environments, broadening their operational permissibility under rules of engagement.
Key programs driving HEL segment revenue include the U.S. Army's Directed Energy Maneuver Short-Range Air Defense (DE M-SHORAD) system, which achieved milestone fielding of a 50-kilowatt class laser on a Stryker combat vehicle. The U.S. Navy's High Energy Laser with Integrated Optical-dazzler and Surveillance (HELIOS) system, developed by Lockheed Martin Corporation, represents a 60-kilowatt class capability deployed aboard surface combatants to counter unmanned systems and small boats. The U.S. Air Force's Self-protect High Energy Laser Demonstrator (SHiELD) program explores airborne HEL integration for fighter aircraft self-defense.
Beyond the United States, Israel has demonstrated operational HEL capability through the Iron Beam system developed by Rafael Advanced Defense Systems, designed to intercept short-range rockets, mortars, and anti-tank missiles at a fraction of the cost of conventional interceptors. The system's operational validation during regional conflict engagements has significantly boosted international procurement interest. The United Kingdom's DragonFire program, a collaborative effort involving Leonardo S.p.A., MBDA, and QinetiQ, achieved first firing in early 2024, demonstrating a multi-kilowatt capable system with potential naval and land applications.
The HEL sub-segment is also the primary beneficiary of advances in the High Energy Laser Market, which encompasses the power scaling, beam quality, and thermal management technologies that underpin system performance. Fiber laser architectures have largely supplanted chemical laser designs due to their electrical efficiency, compact footprint, and reduced logistical burden, enabling integration across a wider variety of military platforms.
Competitively, Lockheed Martin Corporation, Northrop Grumman, and Boeing collectively account for the majority of HEL program prime contract value in North America, while Thales Group, Leonardo S.p.A., and Rheinmetall AG lead European development. The HEL segment's growth is not consolidating among incumbents alone — specialized photonics firms and power electronics companies are entering the supply chain as critical subsystem providers, creating a more distributed competitive ecosystem than traditional defense prime contracting structures.
Market share within HEL is growing rather than merely being maintained, as new platform integration programs across naval vessels, ground vehicles, and fixed installations open fresh procurement opportunities. The shift from experimental to programmed acquisition budgets across multiple NATO and allied nations signals a structural demand inflection point for the HEL segment through the forecast horizon.