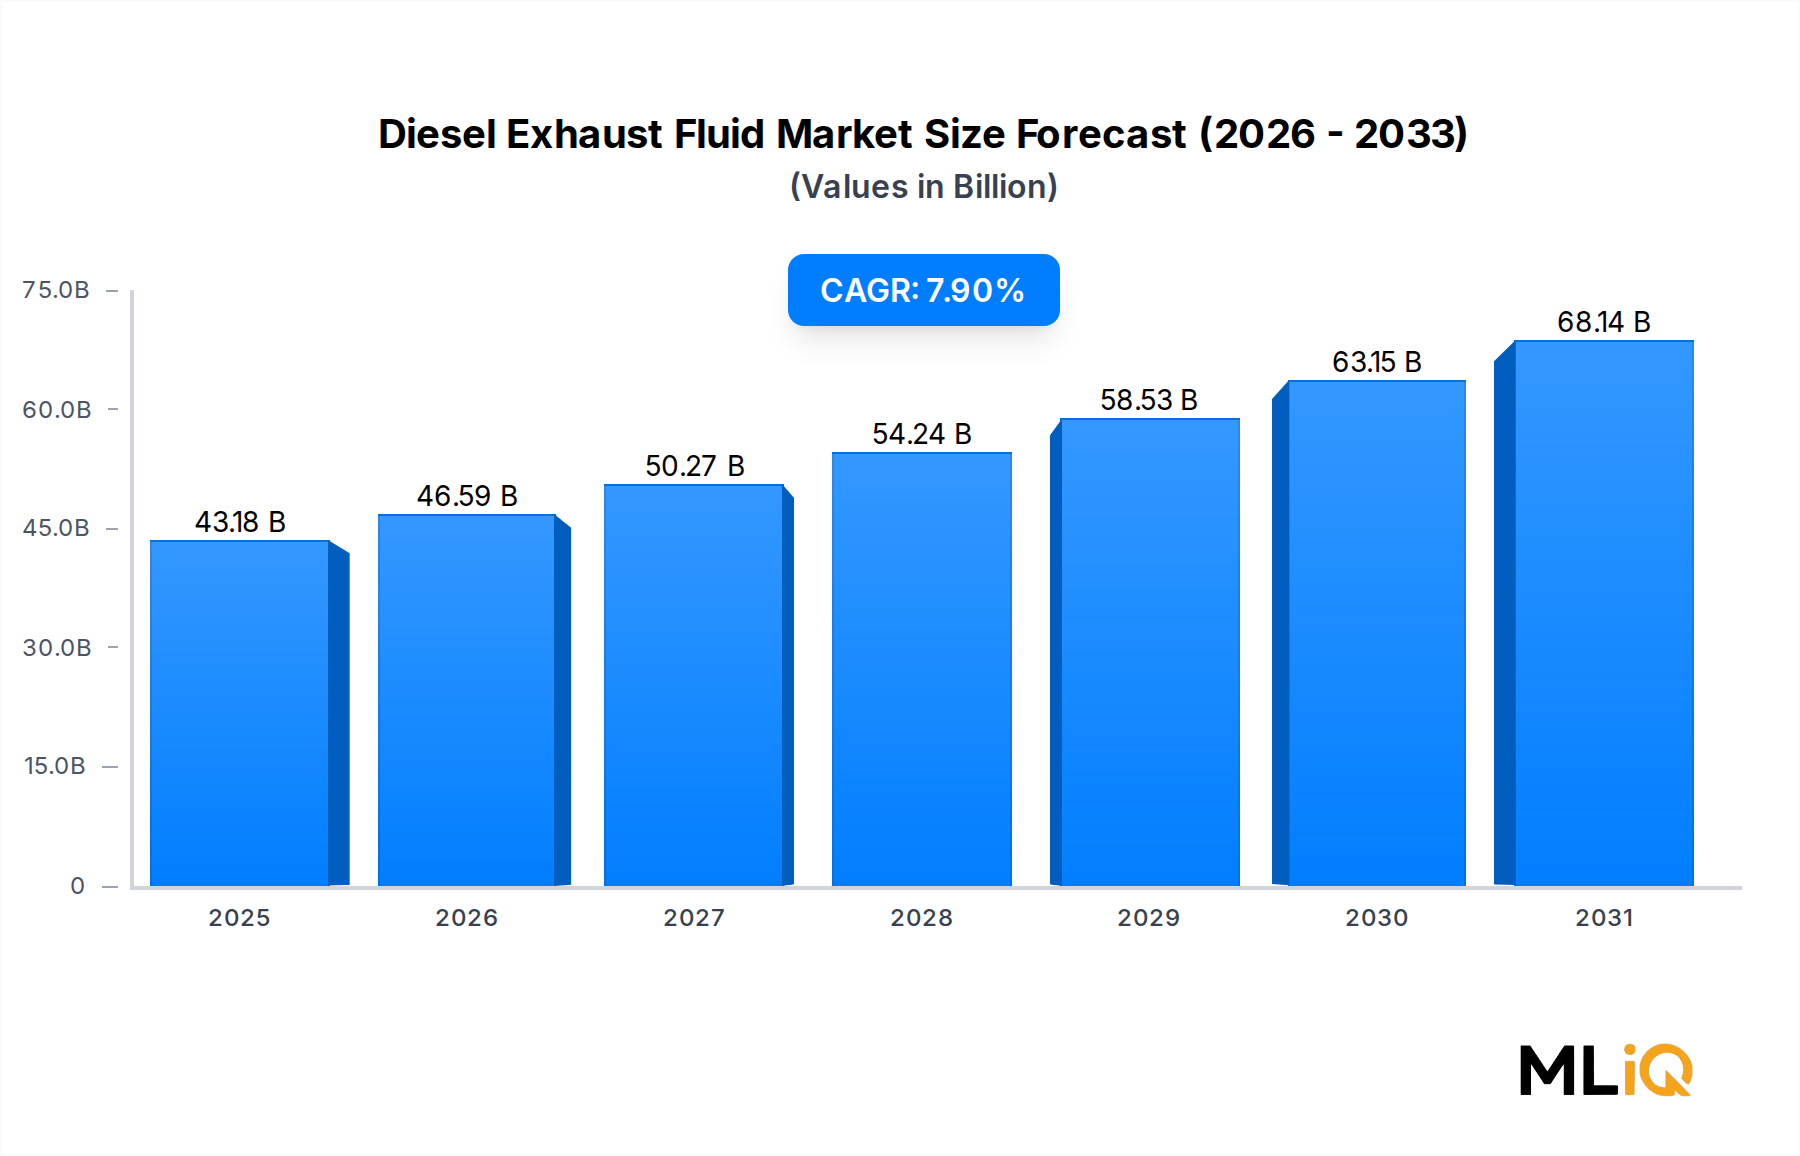
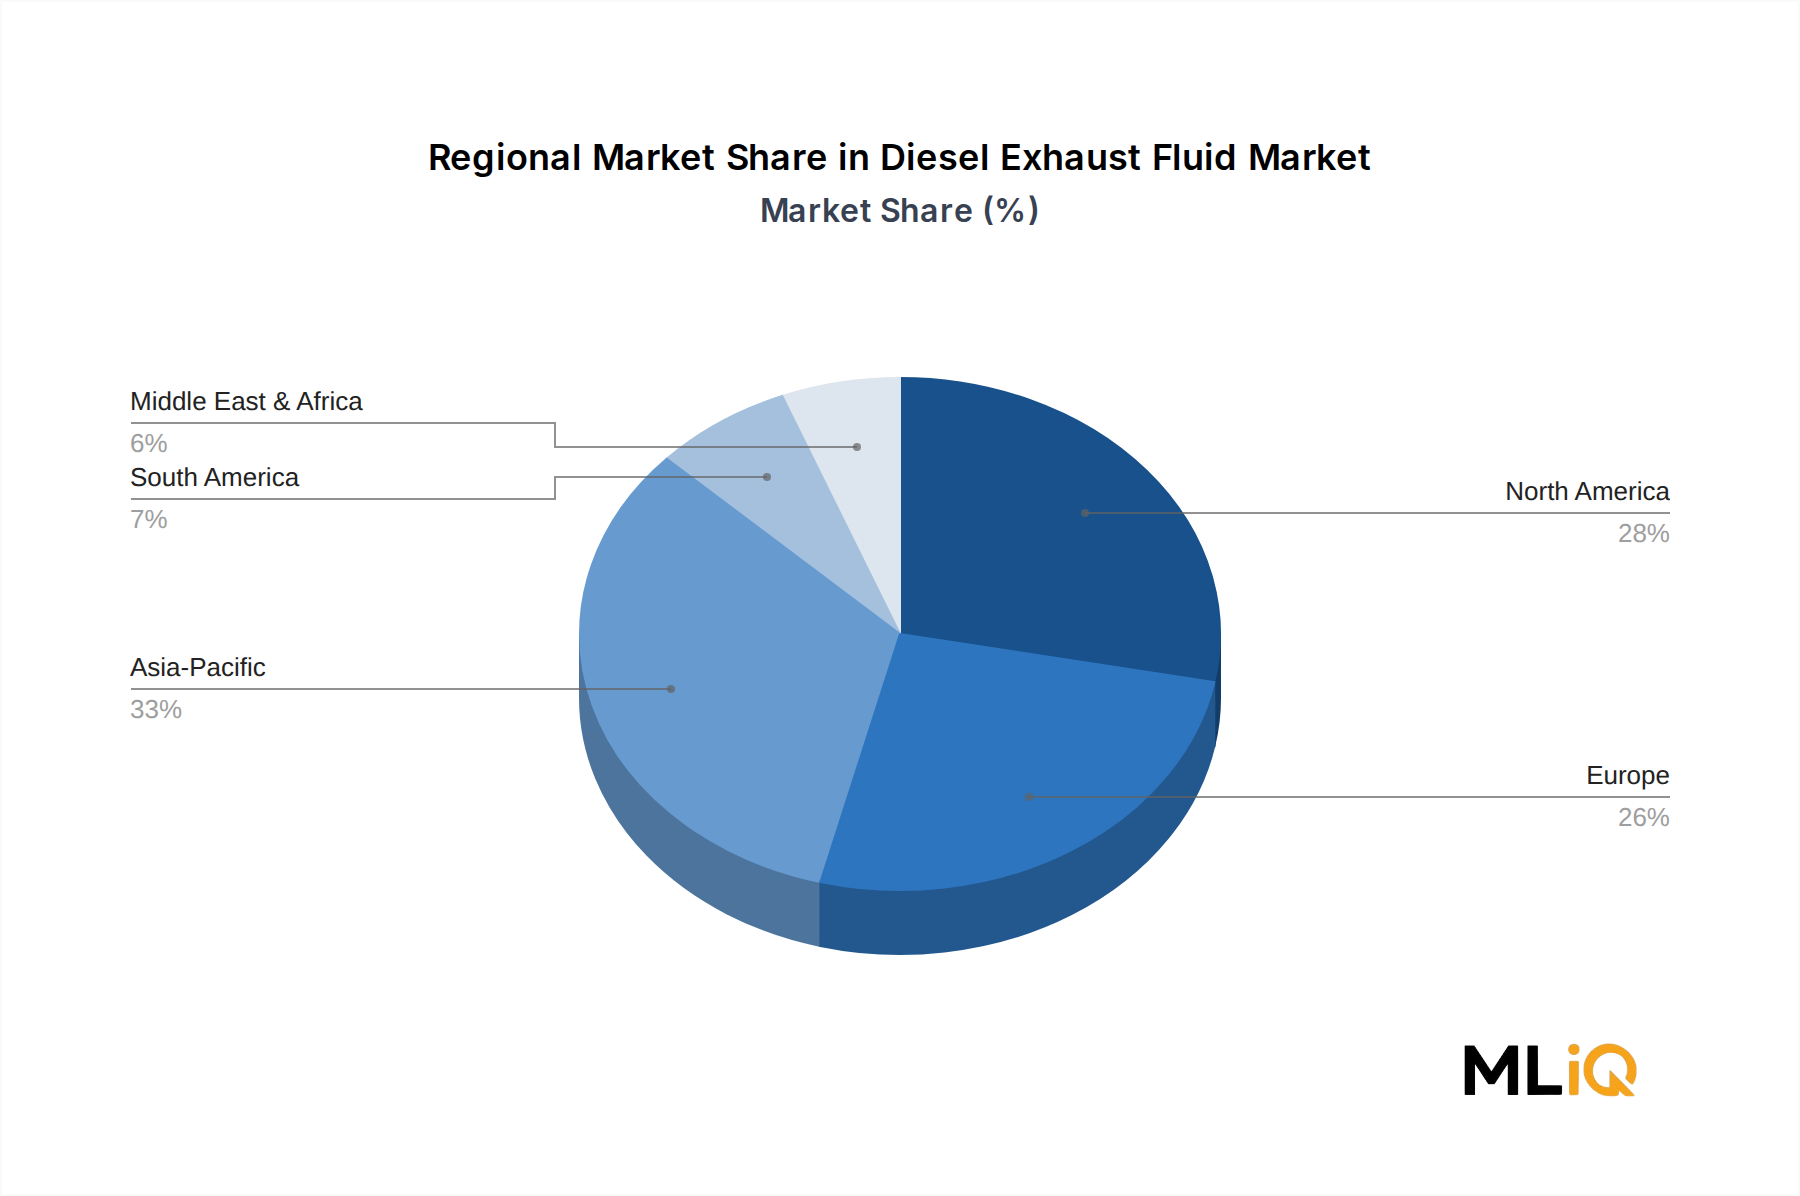
The Diesel Exhaust Fluid Market exhibits pronounced regional differentiation across both growth velocity and market maturity, shaped by the timing and stringency of emissions regulatory frameworks.
North America remains the most established regional market, accounting for approximately 32–35% of global DEF revenue in 2025. The United States, Canada, and Mexico collectively represent a mature consumption base anchored by EPA Tier 4 Final compliance across on-road Class 6–8 trucks and non-road construction and agricultural equipment. The U.S. market is characterized by high per-vehicle DEF consumption rates, well-developed retail and fleet distribution infrastructure, and competitive multi-brand dynamics. Regional CAGR is estimated at approximately 5.5–6.0% through 2033, reflecting steady but moderating growth in a compliance-saturated environment.
Europe holds a comparable revenue share, approximately 28–30% of the global market, underpinned by Euro VI enforcement across all member states and the origin of AdBlue as a standardized DEF brand. Germany, France, the United Kingdom, and the Benelux nations anchor European demand, with Nordics and Eastern Europe representing incremental growth vectors. The Euro VII regulation finalization positions Europe for a secondary demand acceleration from 2027 onward. Regional CAGR is estimated at 6.0–6.5%.
Asia Pacific is the fastest-growing regional market, projected at a CAGR of approximately 10.5–11.0% through 2033, driven by China's China VI rollout, India's BS VI enforcement, and infrastructure-driven construction equipment demand across ASEAN and Oceania. China alone represents the largest single-country incremental DEF demand pool globally, with an estimated heavy-duty vehicle fleet exceeding 10 million units now requiring SCR-compliant DEF consumption.
Latin America is an emerging growth market, with Brazil's PROCONVE P-8 standard driving adoption primarily in São Paulo and Rio de Janeiro freight corridors. Argentina and the Rest of South America exhibit nascent but expanding DEF demand tied to agricultural mechanization. Regional CAGR is estimated at 8.5%.
Middle East and Africa represent the most nascent regional cluster, with GCC nations adopting Euro V-equivalent standards and South Africa implementing BS VI-aligned regulations. Infrastructure gaps in DEF dispensing remain a key constraint across Sub-Saharan Africa, tempering the regional CAGR to approximately 7.0%.