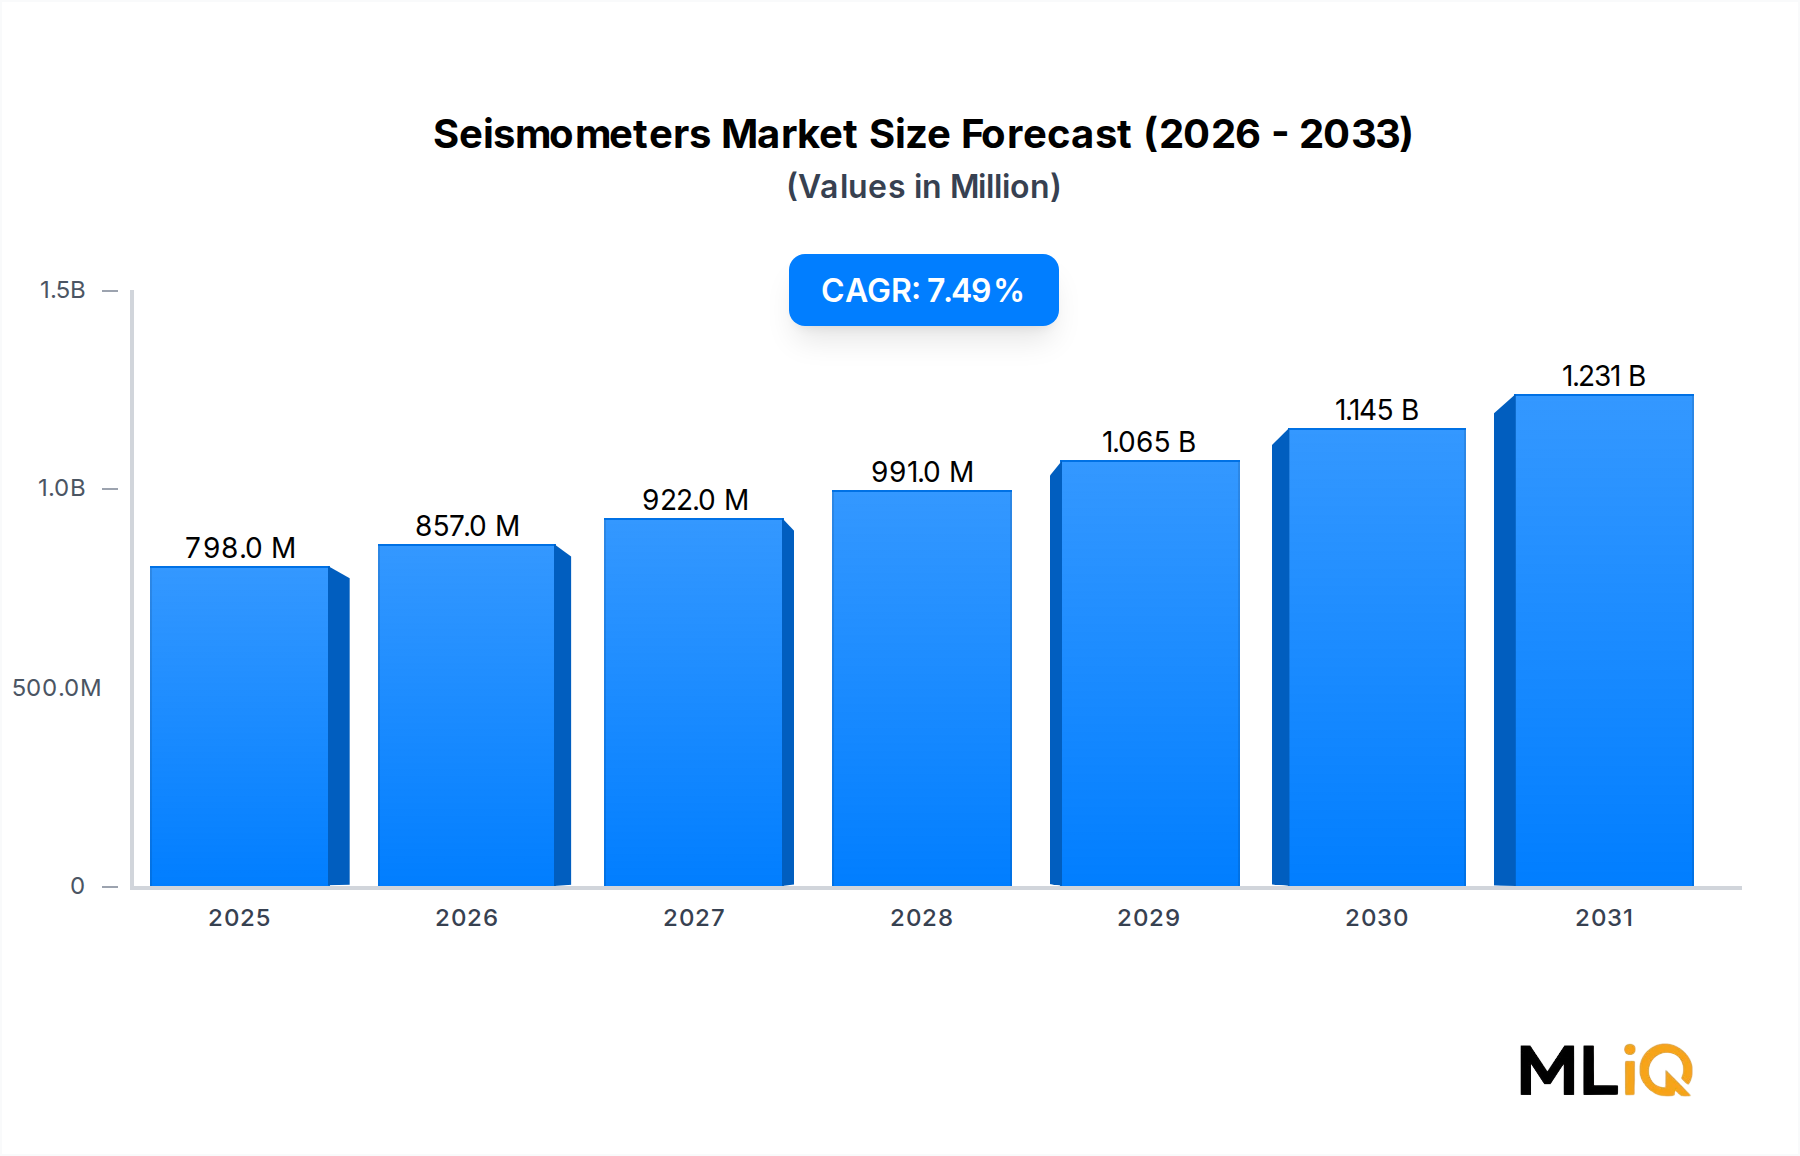
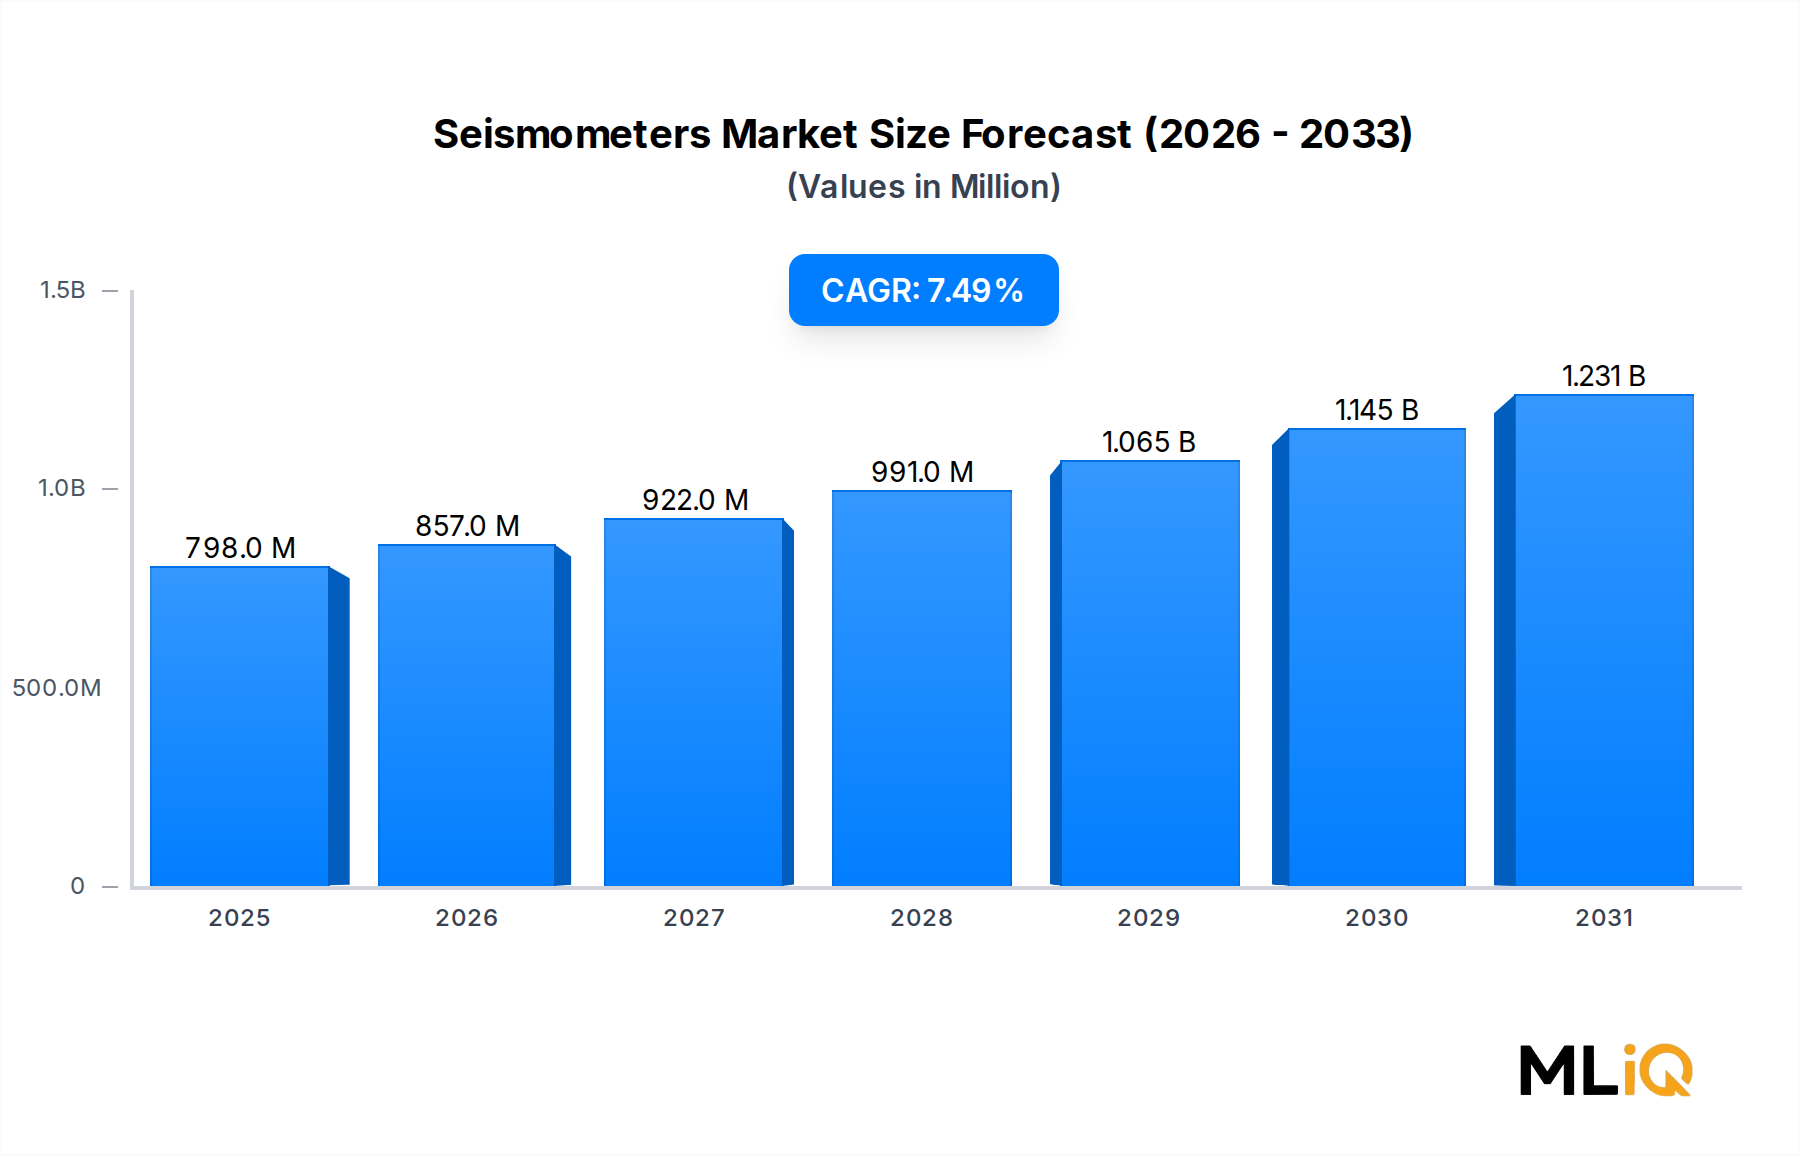
The global Seismometers Market is valued at $797.6 million in 2025, projected to expand at a compound annual growth rate (CAGR) of 7.5% through the forecast period. This trajectory reflects a broad convergence of seismic risk awareness, infrastructure investment, and advancements in sensor miniaturization that are collectively reshaping the demand landscape.
At the macro level, the increasing frequency and intensity of seismic events worldwide has elevated seismometry from a niche academic discipline to a critical public safety and industrial tool. Governments in seismically active nations — including Japan, the United States, China, Indonesia, and Turkey — have significantly expanded national seismic monitoring networks, driving procurement of next-generation instruments. The alignment of seismometer adoption with disaster risk reduction frameworks, particularly the Sendai Framework for Disaster Risk Reduction 2015–2030, has further institutionalized public spending in this domain.
On the industrial side, sectors such as oil and gas exploration, mining, and large-scale civil infrastructure are deploying seismometers for micro-seismic monitoring, site characterization, and structural integrity assessments. The energy transition is also creating new demand vectors: geothermal energy development and carbon capture and storage (CCS) projects both require dense seismic monitoring arrays to manage induced seismicity risks.
Technologically, the shift from analog to digital seismometers, the proliferation of broadband sensors, and the integration of IoT-enabled real-time data transmission are accelerating replacement cycles and expanding total addressable markets. Cloud-based seismic data analytics platforms are emerging as complementary growth drivers, pulling hardware sales alongside subscription software revenues.
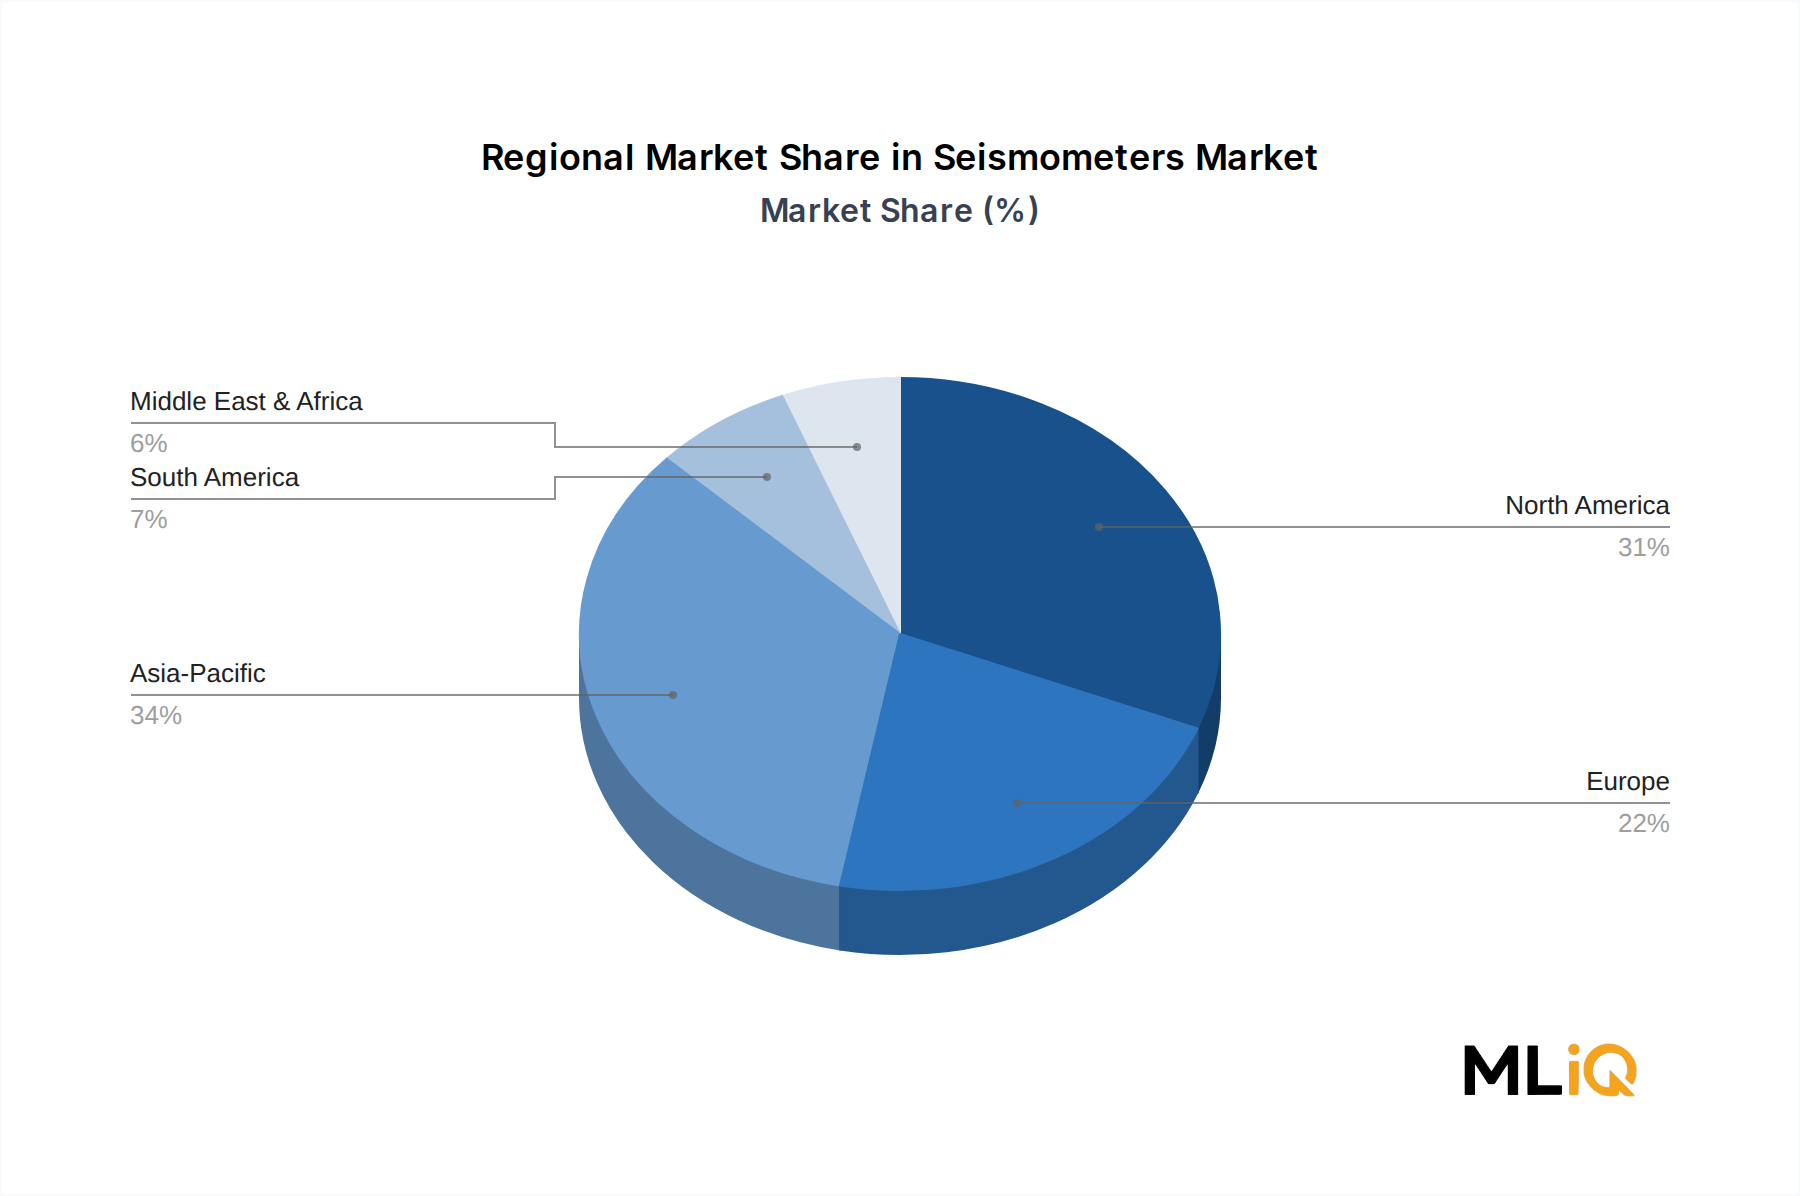
North America and Asia Pacific remain the most significant regional markets, together accounting for a dominant share of total revenue in 2025. However, emerging economies in Southeast Asia and the Middle East & Africa are demonstrating above-average growth rates as infrastructure buildout and disaster preparedness investments intensify.
Key market participants including Geometrics, Seistronix, and a range of diversified sensor and geophysical instrumentation firms are actively investing in product innovation to address requirements across teleseismic, strong-motion, and portable seismometer segments. The competitive landscape is moderately fragmented, with technology differentiation and calibration accuracy serving as primary competitive axes.
Looking ahead, the Seismometers Market is expected to benefit from urban resilience planning, smart city initiatives, and the expansion of global seismic hazard assessment programs. The integration of machine learning in seismic signal processing is anticipated to create premium pricing opportunities for differentiated sensor platforms, reinforcing the market's upward growth trajectory through the end of the decade.