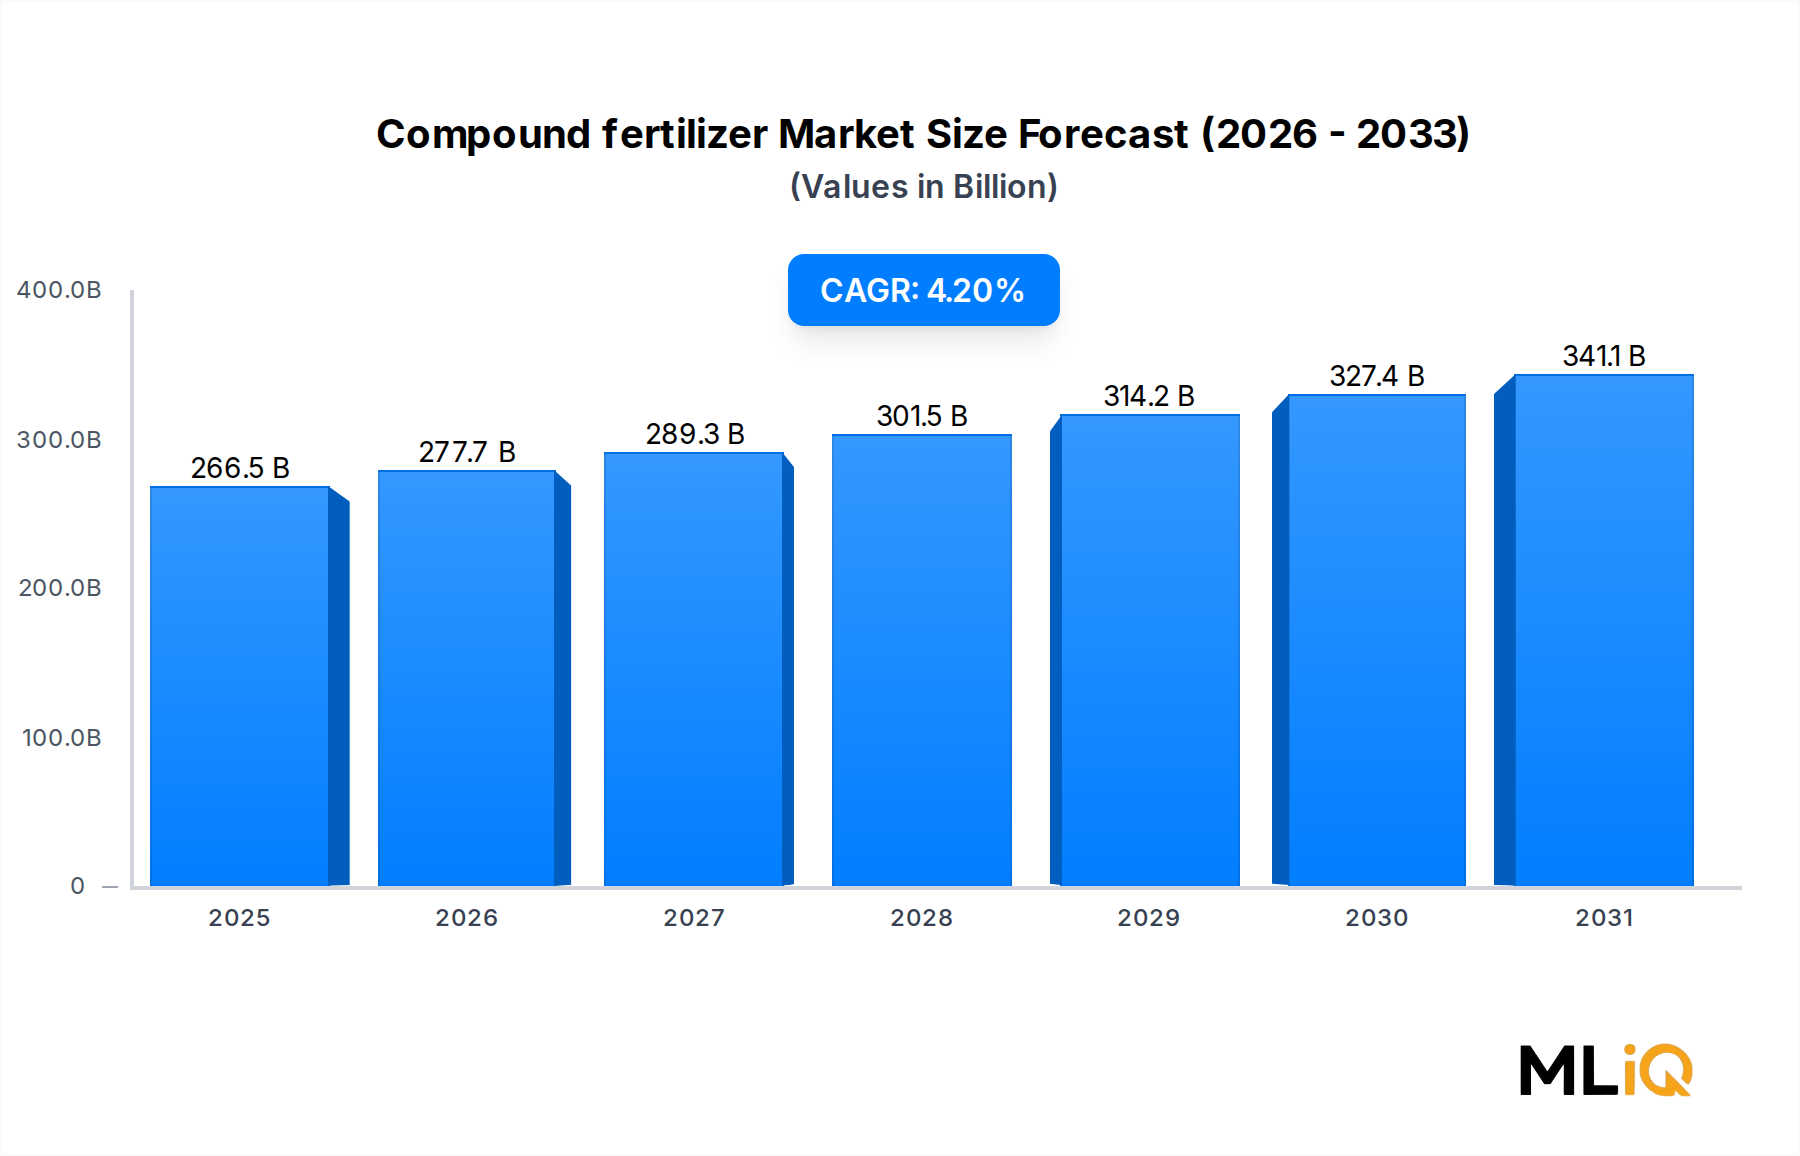
The global compound fertilizer market was valued at $266.49 billion in 2024 and is projected to expand at a compound annual growth rate (CAGR) of 4.2% over the forecast period, driven by escalating global food demand, intensification of agricultural practices, and a structural shift toward nutrient-balanced crop management. As the global population inches toward 10 billion by 2050, the pressure on arable land to deliver higher yields per hectare has never been greater, positioning compound fertilizers as indispensable inputs for modern agriculture.
Compound fertilizers, which combine two or more essential macro-nutrients — nitrogen (N), phosphorus (P), and potassium (K) — in a single granule or liquid formulation, offer agronomic and logistical advantages over straight fertilizers. Their ability to deliver balanced nutrition in a single application reduces labor costs, minimizes soil disturbance, and improves nutrient use efficiency. These characteristics are central to their accelerating adoption across cereal crops, fruit orchards, and vegetable cultivation globally.
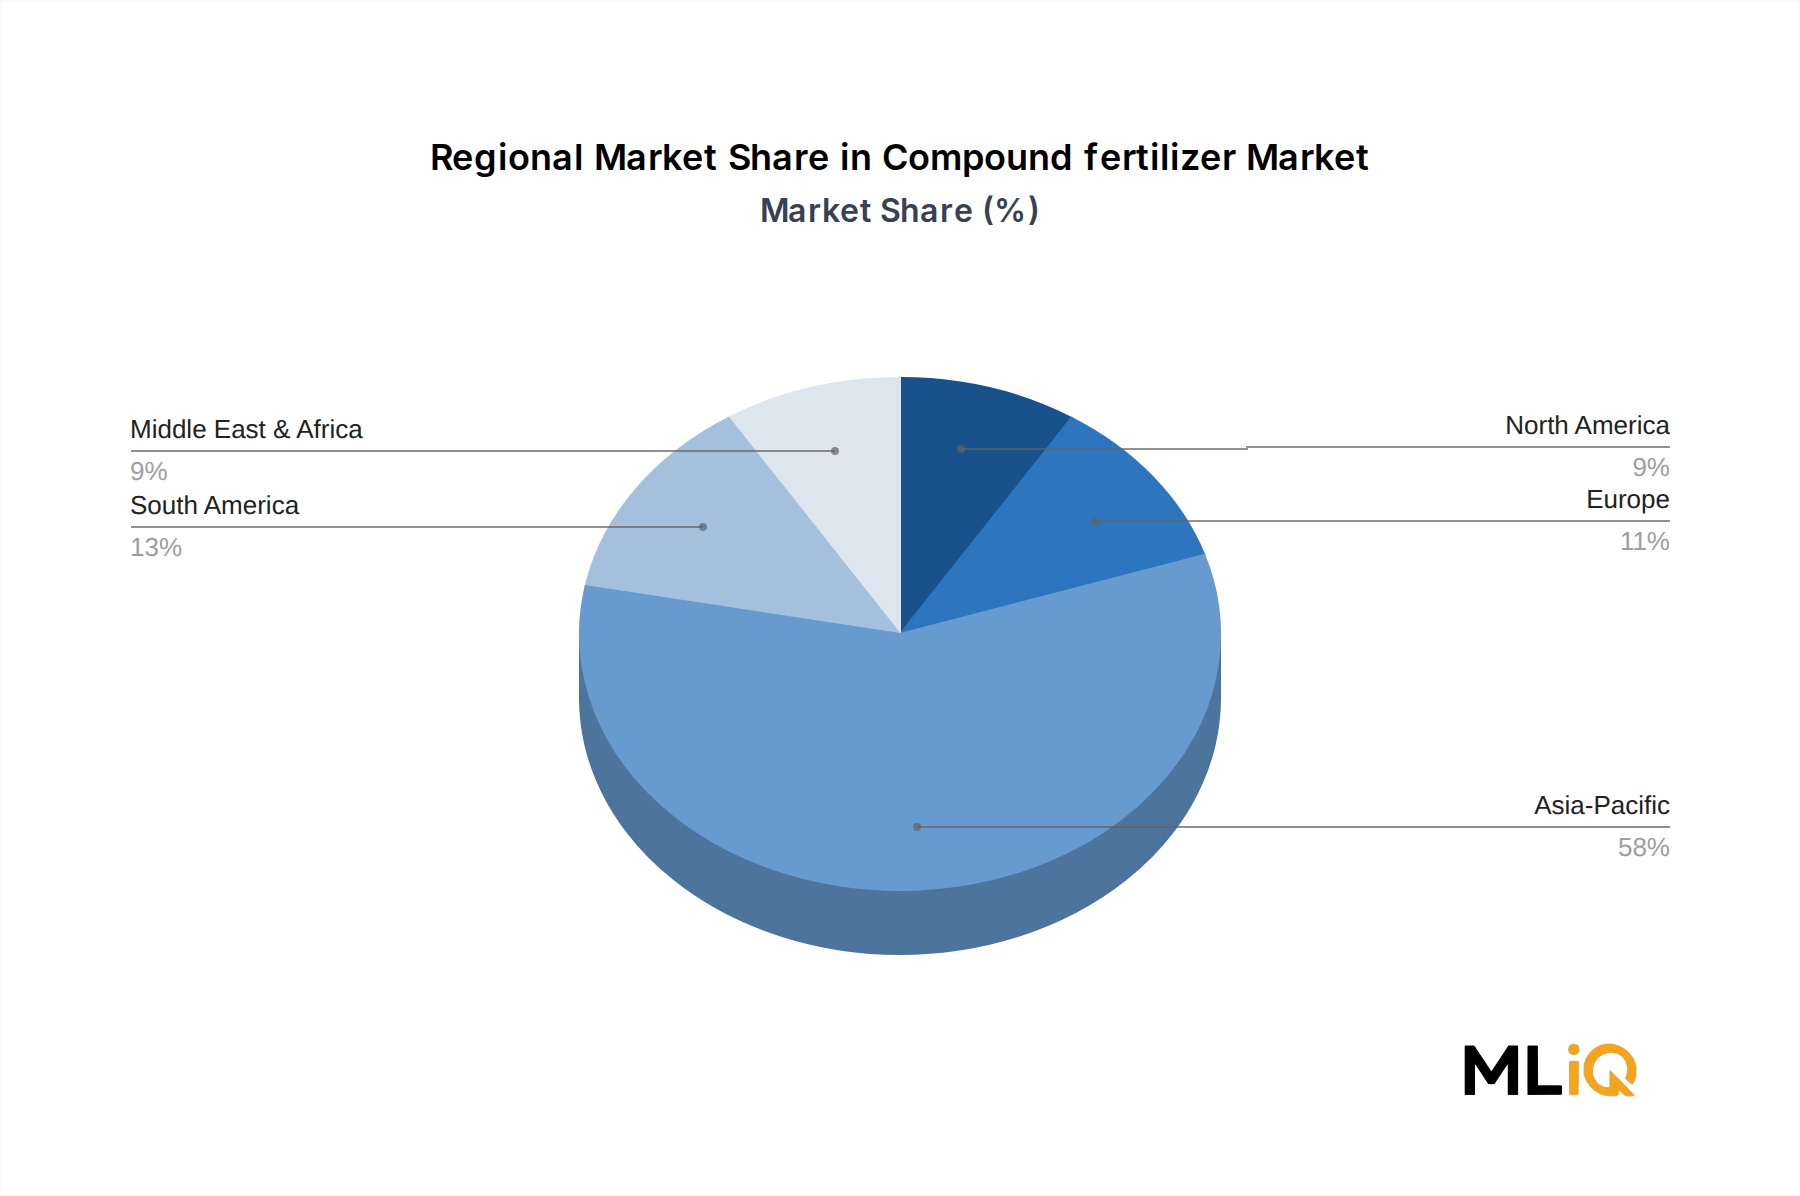
Key demand drivers include rising food security concerns amplified by climate volatility, government subsidy programs across Asia Pacific and South America, and increased penetration of precision agronomic advisory services. In the Asia Pacific region, particularly in China and India, state-backed fertilizer distribution programs continue to provide structural volume support, accounting for a disproportionately large share of global consumption. Meanwhile, in North America and Europe, agronomic innovation is pushing demand toward slow-release and enhanced-efficiency compound formulations.
Macro tailwinds include the expansion of irrigated agricultural land, crop diversification programs, and growing adoption of contract farming models that mandate standardized nutrient inputs. The rise of NPK Fertilizer Market solutions with micronutrient fortification — including zinc, boron, and sulfur — is creating a premium sub-segment within the broader compound fertilizer landscape, enabling manufacturers to improve margins while serving specialty crop producers.
The competitive landscape remains fragmented at the regional level but is consolidating at the global tier, with multinational producers aggressively expanding production capacity in emerging markets. Strategic investments in controlled-release formulations, water-soluble compounds, and fertigation-compatible products are redefining the product architecture of the industry. Environmental compliance obligations — particularly nitrogen and phosphorus runoff restrictions in the EU and parts of North America — are accelerating R&D into next-generation low-emission compound fertilizer technologies.
Looking ahead, the compound fertilizer market is expected to generate substantial incremental revenue through 2031, supported by increasing farmer awareness, digital soil mapping, and integration with smart irrigation systems. The market's trajectory reflects both macroeconomic necessity and agronomic evolution, positioning it as a cornerstone of the global agricultural inputs supply chain.