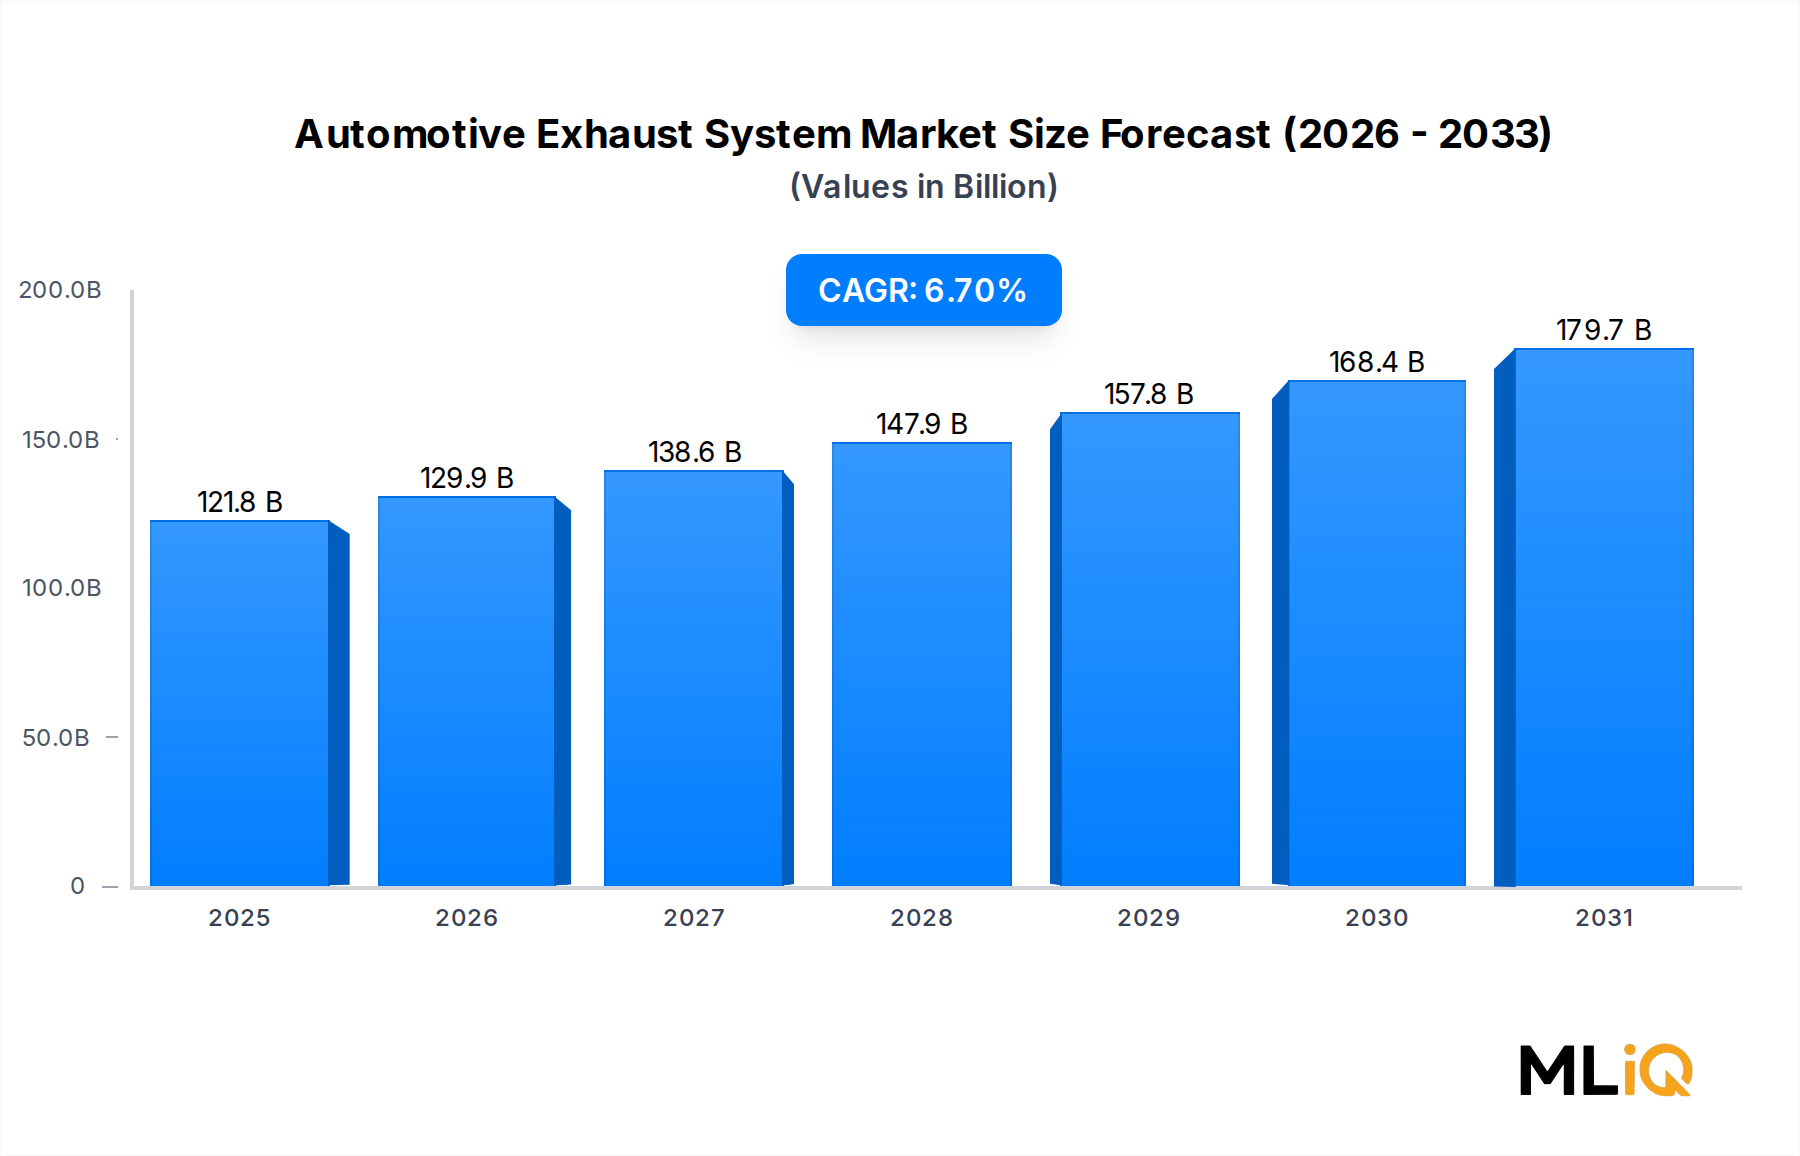
The global Automotive Exhaust System Market is valued at $121.76 billion and is projected to expand at a compound annual growth rate (CAGR) of 6.7% through the forecast period, reflecting robust demand driven by tightening global emission regulations, rising vehicle production volumes, and accelerating adoption of advanced after-treatment technologies. The market's momentum is underpinned by a convergence of regulatory pressure and technological transformation that is reshaping how original equipment manufacturers (OEMs) and Tier-1 suppliers approach exhaust architecture.
The primary demand catalyst is the global enforcement of increasingly stringent emission norms, including Euro 7 in Europe, BS-VI in India, and updated EPA standards in the United States. These regulations mandate the integration of sophisticated after-treatment components such as diesel particulate filters, selective catalytic reduction systems, and gasoline particulate filters, effectively raising the per-unit content value of every exhaust assembly sold. As a result, average system selling prices are trending upward even as light-weighting initiatives apply downward pressure on component mass.
Macroeconomic tailwinds include recovering global vehicle sales following post-pandemic supply chain normalization, expanding commercial vehicle fleets in Asia Pacific and Africa, and sustained consumer preference for internal combustion engine (ICE) vehicles in emerging markets where EV infrastructure remains underdeveloped. While long-term electrification trends present a structural headwind, the ICE fleet is expected to remain the dominant platform through at least 2035 in volume terms, preserving a long runway for exhaust system demand.
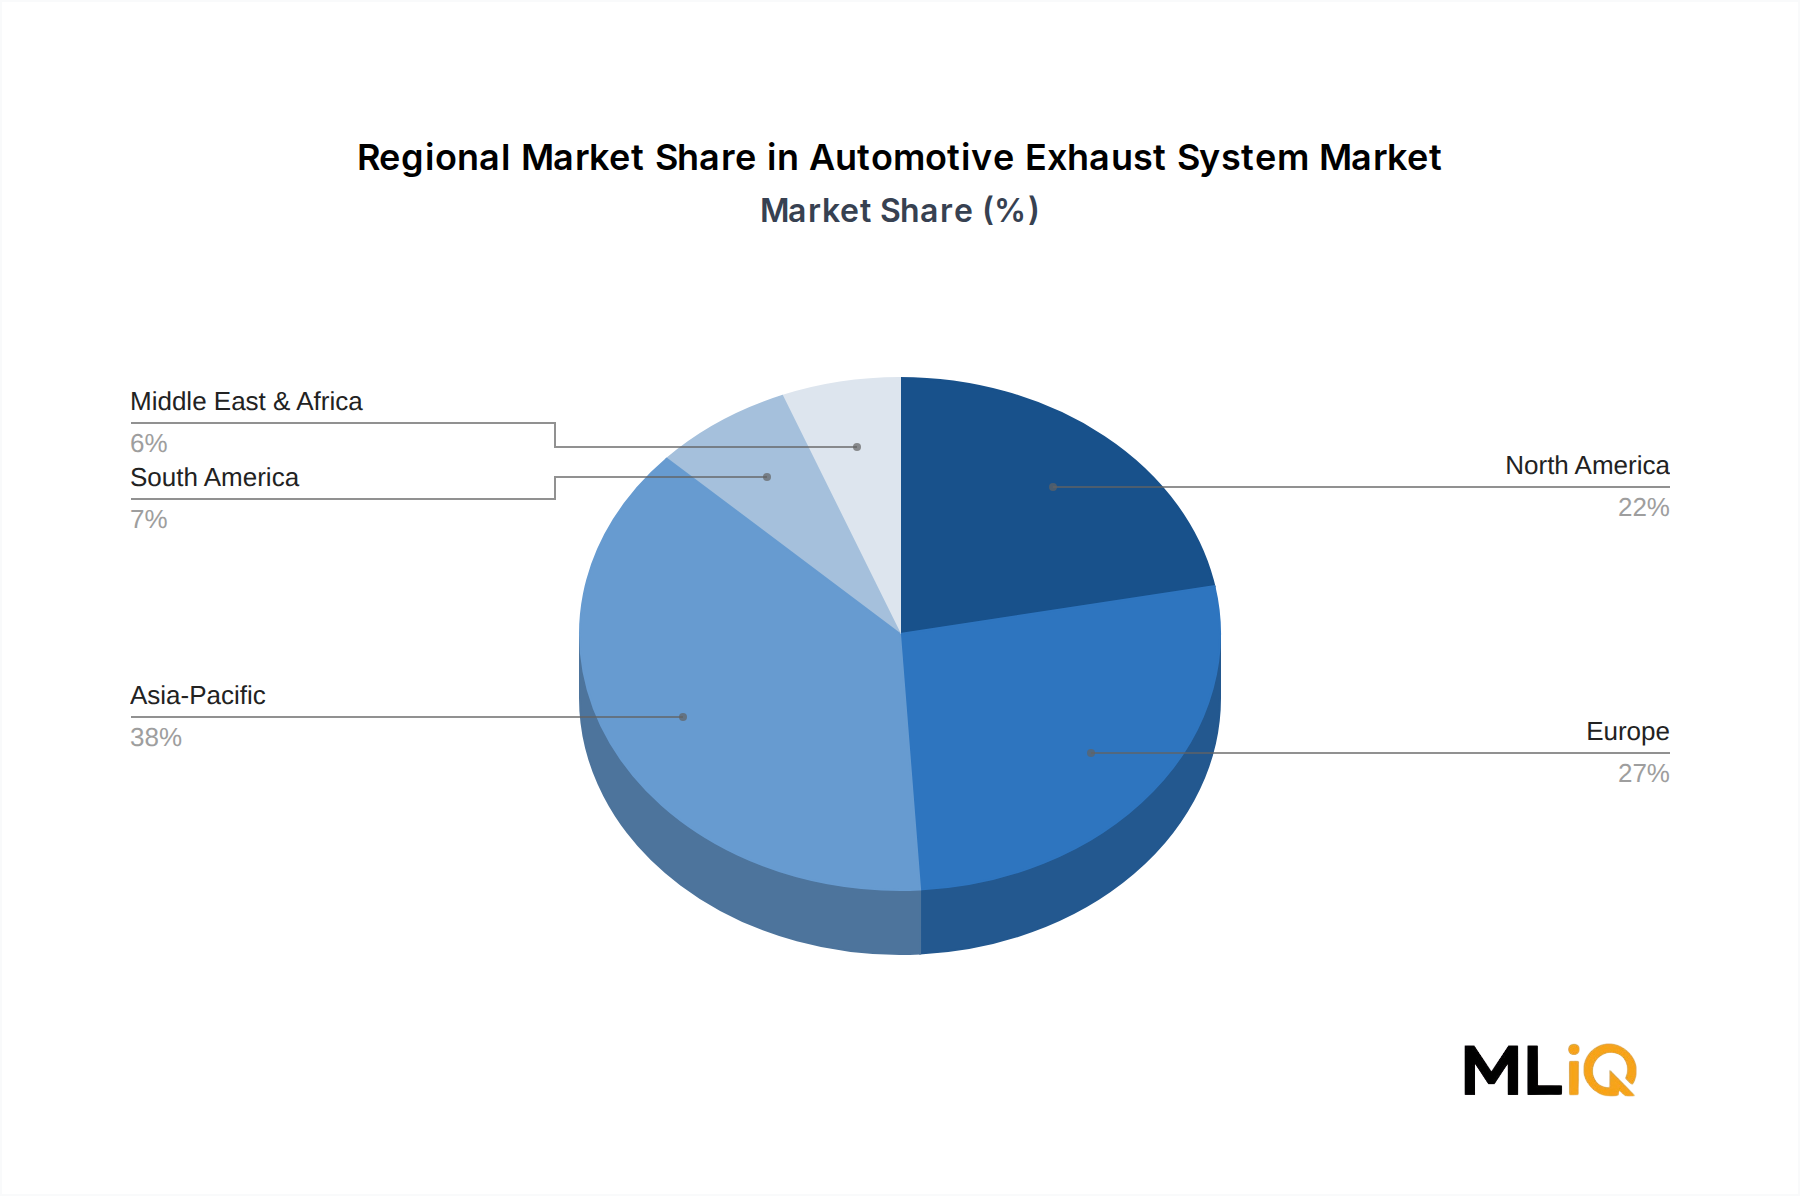
The aftermarket segment is emerging as a significant revenue contributor, particularly in mature markets such as North America and Western Europe, where aging vehicle fleets require replacement components. The average vehicle age in the United States has exceeded 12 years, creating consistent replacement demand for mufflers, catalytic converters, and flex pipes.
From a technology standpoint, the market is transitioning from passive pipe-and-muffler configurations to fully integrated thermal management and emissions control modules. Investments in electric heating elements for cold-start catalyst activation and 48V mild-hybrid compatible exhaust architectures are gaining traction among leading suppliers.
Key players including Tenneco Inc, Faurecia, Eberspächer, and BENTELER International are scaling their product portfolios to address both OEM and aftermarket channels simultaneously. The competitive landscape is consolidating through strategic mergers and technology licensing agreements, reinforcing scale advantages for top-tier incumbents.
Looking ahead, the market's trajectory through 2030 will be shaped by the pace of hybrid vehicle adoption, the stringency of Tier 4 and equivalent off-road emission standards, and the ability of suppliers to integrate digital diagnostics and onboard monitoring into exhaust system assemblies.