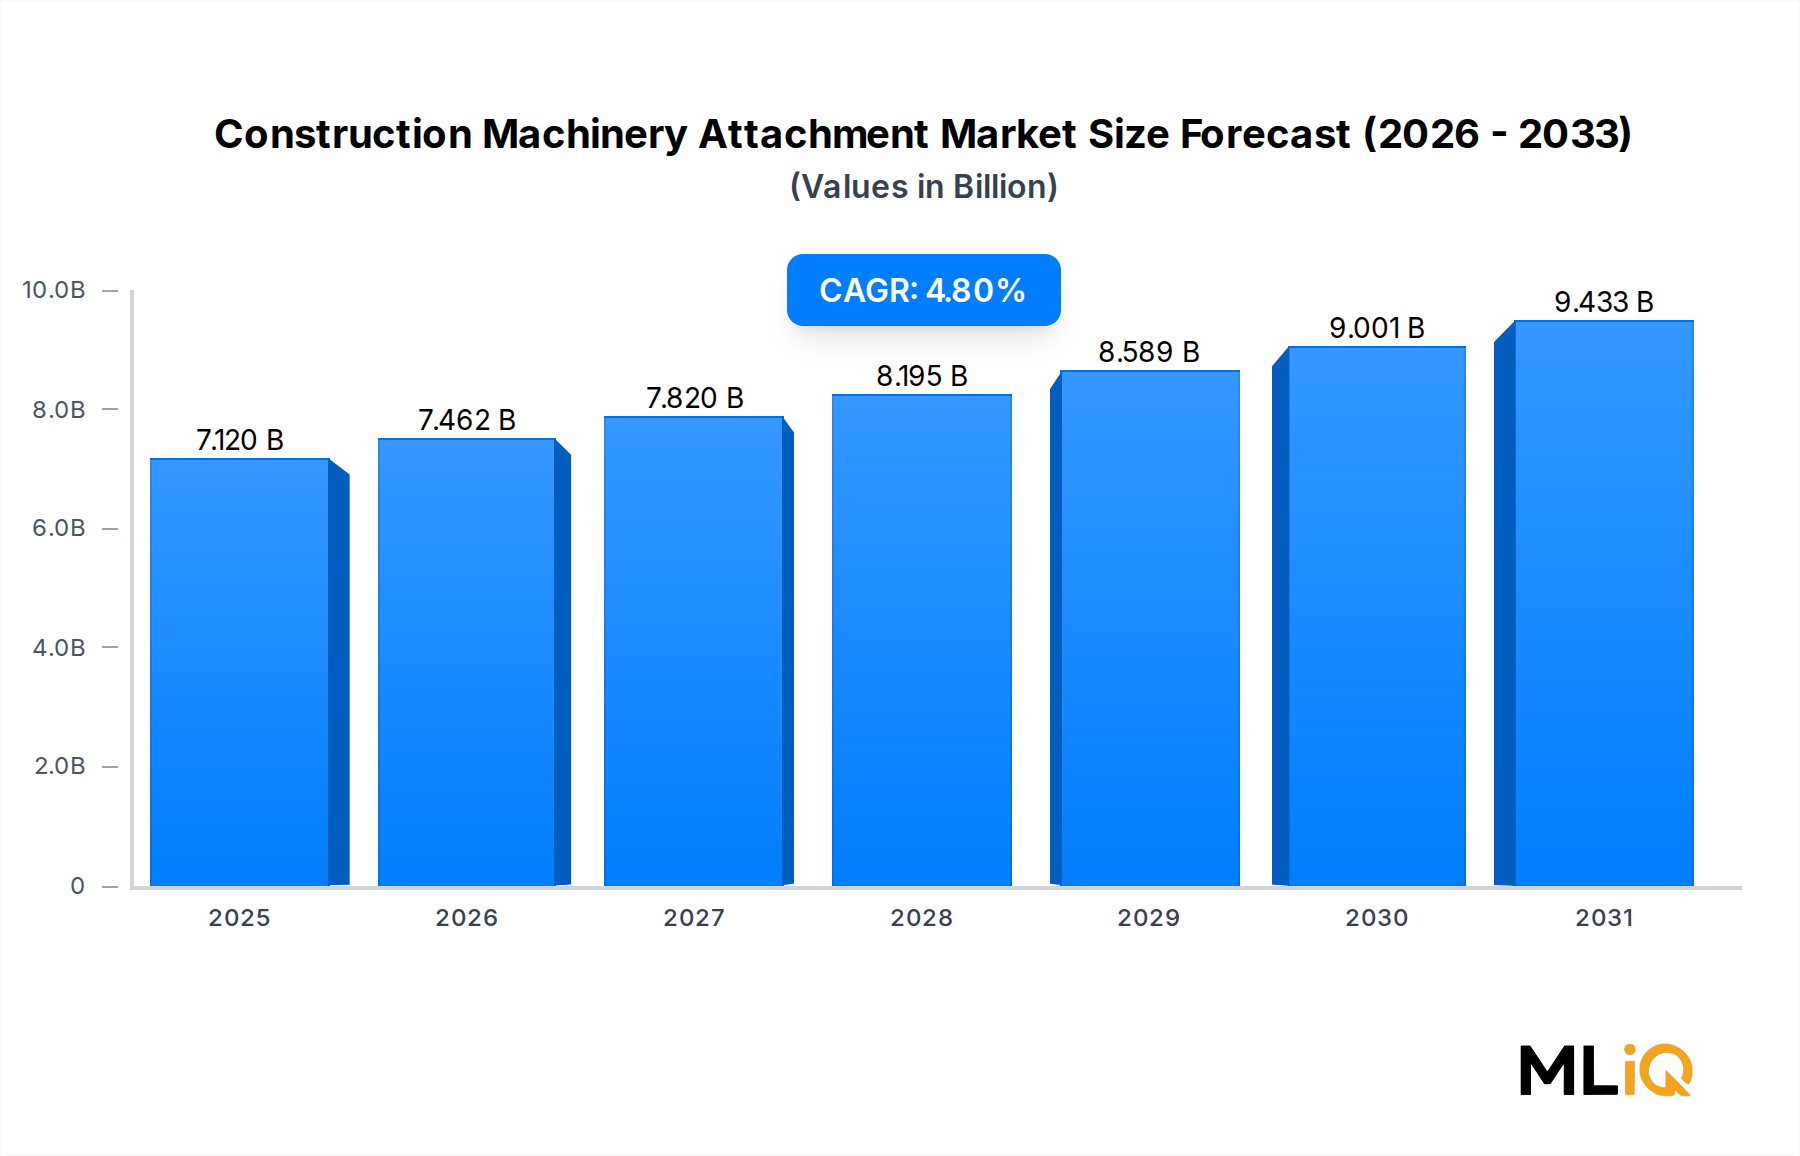
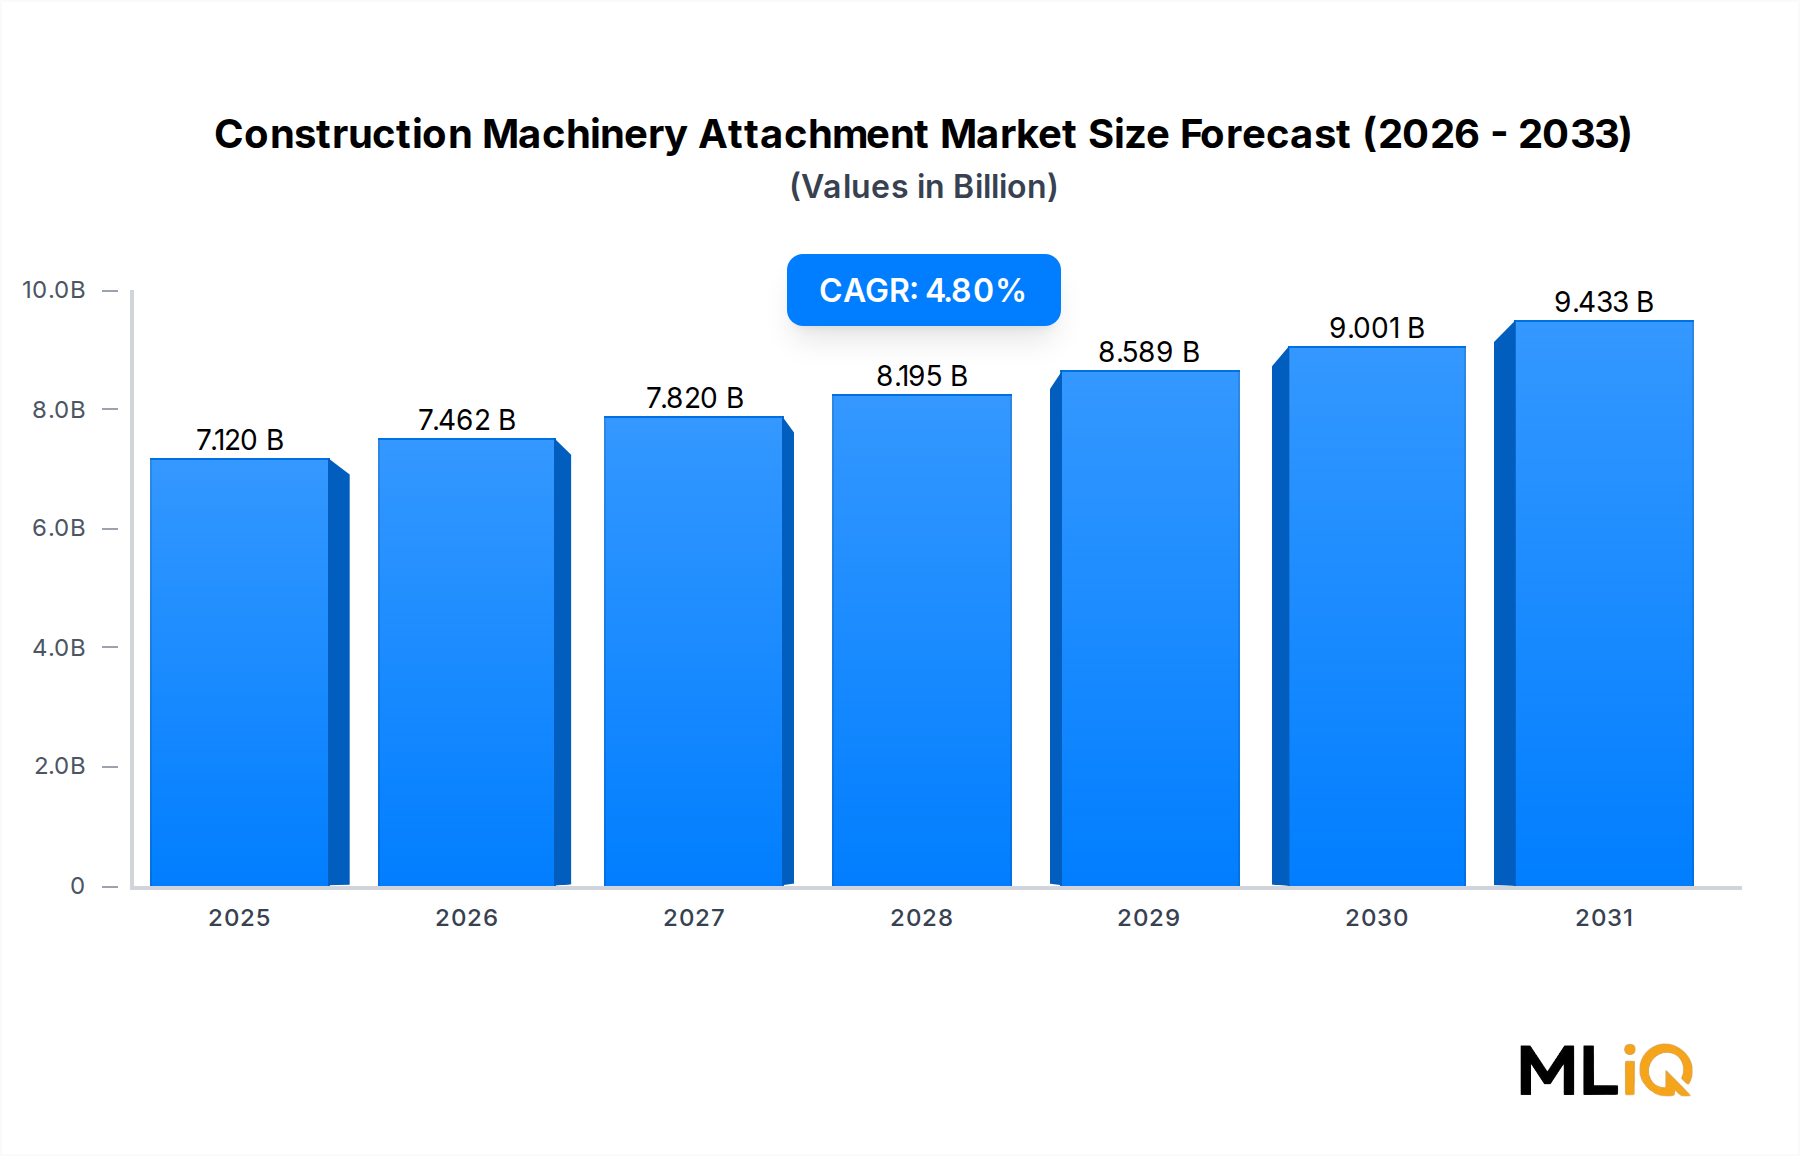
The Construction Machinery Attachment Market is valued at $7.12 billion in the base year and is projected to expand at a compound annual growth rate of 4.8% through 2025–2033, reflecting sustained momentum driven by accelerating infrastructure investments, urbanization trends, and the growing adoption of multi-functional machinery across diverse end-use verticals. By 2033, the market is expected to surpass $10.5 billion, underlining the structural importance of attachments as force-multipliers for base machine productivity.
Construction machinery attachments — encompassing excavator buckets, grapples, quick couplers, concrete pulverizers, rakes, forks, and specialty tools — enable a single base machine to perform a wide variety of tasks, dramatically reducing capital expenditure for contractors and rental fleet operators. This versatility is the central commercial proposition driving consistent aftermarket and OEM demand worldwide.
Key macro tailwinds include multi-trillion-dollar national infrastructure programs in the United States (the Infrastructure Investment and Jobs Act), China's sustained Belt and Road-linked construction pipeline, and the European Union's cohesion fund disbursements across Central and Eastern Europe. In developing economies across South and Southeast Asia, rapid urbanization is pushing demand for compact and mid-size excavators, loaders, and skid-steers, all of which require compatible attachments across earthmoving, demolition, landscaping, and roadwork applications.
On the demand-driver side, the replacement cycle for aging attachment fleets, particularly in North America and Western Europe, continues to generate a reliable aftermarket revenue stream. Meanwhile, technological upgrades — including tiltrotator systems, hydraulic quick-coupler mechanisms, and sensor-integrated attachments — are creating premium replacement and upgrade cycles that expand average selling prices.
The mining sector's robust capital expenditure cycle, solid waste management modernization programs, and the expansion of agricultural mechanization in emerging economies represent incremental growth verticals layered atop the foundational construction end-use segment. Across all these verticals, safety regulations mandating quick-coupler safety locks and load-sensing hydraulics are adding compliance-driven procurement momentum.
Looking forward, the convergence of autonomous machine platforms, electrification of compact equipment, and digitized fleet management systems will reshape attachment design standards, with smart attachments embedded with IoT sensors becoming a meaningful revenue contributor by 2030. OEM integration strategies and aftermarket channel partnerships will remain the twin pillars of competitive positioning throughout the forecast horizon.